Best Lawn Care Business Insurance Companies

I compared average rates for policies that cover common lawn care risks, such as your mower sending debris into a customer’s car or equipment being stolen from your trailer. However, the lowest rate won''t give you the best value if post-purchase experience isn't good, so I also considered self-service policy management. Being able to update coverage or download a certificate of insurance (COI) matters when you need proof of coverage before you can start and you’re already out on your route. 

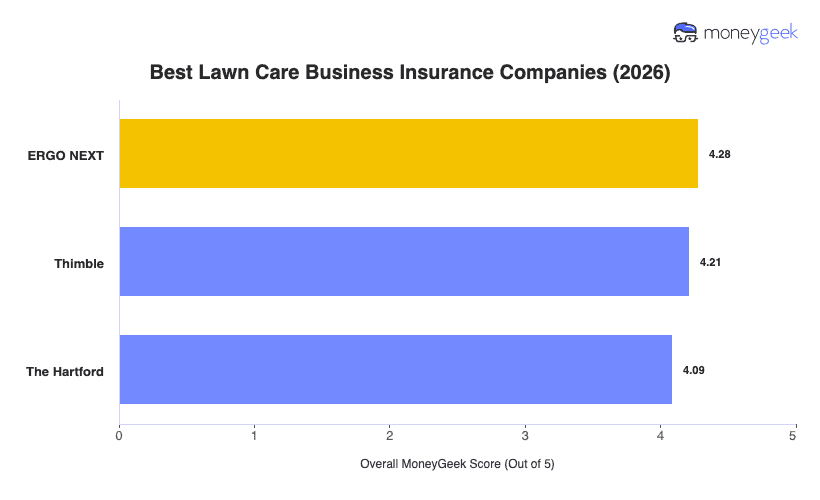
Based on my analysis, my top three picks are:

  • Choose if you want the best overall value: ERGO NEXT
  • Choose if you need on-demand coverage: Thimble
  • Choose if you need comprehensive lawn care coverage: The Hartford

We scored lawn care insurers on costs, customer experience and coverage options to get these rankings. Our pricing analysis focuses on lawn care businesses with one to four employees across all 50 states and Washington, D.C. Overall scores combine affordability (50%), customer experience (30%) and coverage options and policy terms (20%). We also reviewed over one million business profiles, more than 100,000 customer experience data points and coverage contracts and endorsements across 408 sub-industries.

See our full methodology.

ERGO NEXT

ERGO NEXT: Best for Overall Value

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT is the best overall insurer for most small lawn care companies, especially owner-operated businesses that prefer to manage insurance themselves. You can access COIs 24/7 and make policy changes through its mobile app, which helps when a property manager or HOA requires proof of insurance before work starts. This access comes with a monthly rate that’s 18% lower than the industry average, and saves you about $26 per month.

ERGO NEXT's policies common risks from mowing, maintenance and routine residential lawn care. It has tools and equipment coverage, but if you start using more expensive equipment like commercial mowers, it's $5,000 cap per item limit might not be enough. It isn't the ideal provider either if you offer lawn treatments or if you handle commercial clients.

Learn More: ERGO NEXT Business Insurance Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

I’d recommend Thimble if you only do seasonal lawn care work or booked one job at a time. It’s the only carrier in my study with on-demand coverage, which you can buy for as short as an hour or for a full month. That flexibility makes sure that you're financially protected during a weekend cleanup or a short contract without paying for the months when you aren’t working.

Thimble also has the lowest average premium in our study. Its rates are 19% below the industry average, saving you around $28 per month. However, its limited coverage lineup may still suit solo operators focused on mowing and routine yard maintenance. Once you hire employees or invest in a business-owned vehicle, however, you’ll need another provider for workers’ compensation or commercial auto.

Learn More: Thimble Business Insurance Review

The Hartford

The Hartford: Best for Comprehensive Lawn Care Coverage

On The Hartford's site
COMPANY HIGHLIGHTS

Our third provider is The Hartford, which I'd recommend for lawn care businesses with more complex coverage needs. Because of its coverage portfolio, it's provides more extensive financial protection when you're managing crews, using commercial equipment, applying pesticides or herbicides, or taking on seasonal property-maintenance work.

Some policies require a phone call instead of an instant online quote, but that extra step could be worth it if you need help sorting through layered risks. While you can't get same-day coverage or proof of insurance, you get access to stronger risk management resources. Larger lawn care companies can spot safety issues tied to employees, trucks, equipment and job sites before the same problems turn into repeat claims. Its premiums are higher than most competitors, so The Hartford's a better fit you value coverage depth and hands-on support more than finding the lowest price.

Learn More: The Hartford Business Insurance Review

Best Types of Insurance For Lawn Care Businesses

What you need in your coverage mix depends on the lawn care work you do. A mower can damage an irrigation head, and a stolen trimmer can stop you from finishing the day’s route, which is you're most likely to start with general liability and tools coverage. That said, your policy mix should expand when you hire workers or add services. 

Use our table as a checkpoint. Once a trigger applies to your business, include that coverage when requesting quotes.

Costs if your work injures someone or damages customer property, including legal fees
Before your first paid job on customer property
Tools and equipment
Mowers and other equipment stolen or damaged while traveling or at a job
Equipment you take to jobs would cost $2,500 or more to replace
Accident claims and covered repairs involving a work vehicle
You use a vehicle mainly to haul equipment between customers
Medical care and part of an employee’s missed wages after a work injury
You hire employees and your state requires coverage
Customer claims, plus your building and items stored at the address on your policy
You start using a shop or storage unit for equipment
Herbicide and pesticide coverage
Injuries or property damage caused by spilled or drifting chemicals
You begin offering weed or pest treatments
Liability costs above your general liability or auto policy limits
A contract requires more liability coverage than your policies provide
Costs after customer data is stolen or your business systems are attacked
You store customer records or take payments online

Best Lawn Care Insurance Buying Checklist

To make sure you get the best business insurance for your lawn care business, I've prepared a checklist to help you sort through the different things you need to do. There's also a downloadable version that you can save, print or use as you go through the process.

Download: Lawn Care Business Insurance Buying Checklist

  1. 1

    Assess Your Lawn Care Businesses’ Risks

    Risks come from different areas of your lawn business, so start with the jobs you do regularly. Do you mow residential lawns or maintain commercial properties? Commercial clients and and recurring service contracts often bring more paperwork and require higher limits. If you haul equipment between jobs, store gear, manage a crew or apply lawn treatments, you have more exposure than a solo operator who only handles basic mowing and trimming for homeowners.

  2. 2

    Match Risks to Coverage Types

    Match each risk to the policy that covers it. General liability applies if your mower throws a rock through a customer’s window, and tools and equipment coverage protects the mowers, trimmers, blowers and other gear you bring to each job. Most states require you to carry workers’ comp you hire a crew member, and covers injuries they can get from lifting equipment, trimming for long stretches or working in heat. Accidents caused by your truck or van can be costly, which commercial auto helps with.

  3. 3

    Check Requirements and Set the Right Limits

    Homeowners may only ask whether you’re insured [confirm if they even do], but HOAs, property managers and commercial clients usually require certificates, additional insured wording, workers’ comp proof or higher liability limits. Check state rules, client contracts and job requirements before choosing limits. Treat those requirements as the floor, then adjust based on your equipment value, crew size, vehicle use and service mix.

  4. 4

    Compare Provider Fit

    When narrowing down provider options, look at price, customer experience and coverage options together. A low premium isn’t always the better deal. Even with lower rates, an insurer that's slow with certificates, hard to reach during a claim or missing coverage for the lawn care work you do can cost you time, delay jobs or leave gaps in your policy.

  5. 5

    Request Quotes and Review Policy Details

    Request each quote using the same business details so you’re comparing the policies fairly. Tell each provider what lawn care work you do, how much your equipment is worth, whether you have employees and how you use vehicles for work. Before buying, review the quote and pay attention to limits or exclusions that could affect common lawn care situations, such as stolen equipment, trailer use, chemical application or subcontracted work. If a quote leaves out something you regularly do, ask the provider to update it before you compare price.

Best Lawn Care Business Insurance: Bottom Line

My analysis of seven major insurers showed that ERGO NEXT, Thimble and The Hartford are your top choices for lawn care business insurance. But “best” doesn’t mean the same thing for every lawn care business. If you look at the decision through cost, one provider may rise to the top. If you look through work complexity, growth stage or client paperwork, another may be the better fit. The key question isn’t “Which insurer is best overall?” It’s “Which insurer fits what matters most to my lawn care business right now?” That could be the work you do, the size of your operation or the documents your clients require before service starts.

Best Lawn Care Business Insurance Chart

Best Lawn Care Business Insurance: FAQ

About Connor Bolton


Connor Bolton, Senior SEO and Content Manager (Business & Pet), MoneyGeek

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.

The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.

Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.

Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.