Cheapest Massachusetts General Liability Insurance Companies

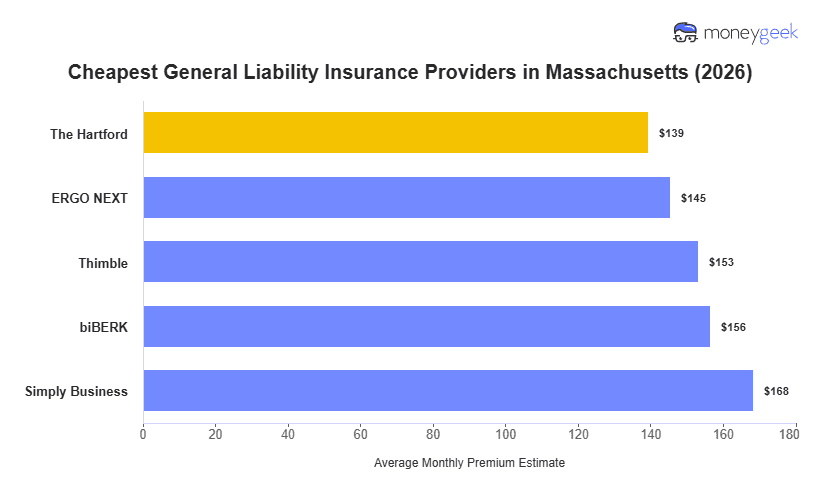
Rates for general liability insurance in Massachusetts vary widely by insurer and business type. I gathered and compared quotes for 25 general industries to determine the most affordable general liability coverage providers in the state. Four insurers consistently topped my list:

  • The Hartford: Lowest rates for creative professionals and health care providers, including photography, DJ services, massage therapy and holistic health practices
  • ERGO NEXT: Most affordable for hands-on trades and personal services, including carpentry, HVAC contracting, beauty salons and estheticians
  • Thimble: Cheapest for heavy construction and specialty contractors, including roofing, electrical work, pest control and lawn care
  • biBerk: Most affordable for cleaning services and fitness businesses, including janitorial work, house cleaning, yoga studios and personal training

Your final general liability premium varies based on your specific industry, business size, claims history and location within Massachusetts. It's better to treat my findings as a starting point rather than a guaranteed price.
The Hartford$139$1,67217%
ERGO NEXT$145$1,74614%
Thimble$153$1,8389%
biBerk$156$1,8767%
Simply Business$168$2,0190%
Coverdash$174$2,094-3%
Progressive Commercial$180$2,164-7%
Hiscox$190$2,280-12%
Chubb$190$2,285-13%
Nationwide$191$2,294-13%

For Massachusetts, we used more than 20,000 standardized general liability estimates from 10 major insurers. The dataset spans 408 business types across 25 industries and includes businesses with zero to 49 employees. All estimates assume $1 million per occurrence/$2 million aggregate limits and factor in modeled revenue and payroll.

We use the data differently depending on the comparison:

  • Overall rankings: Average pricing for Massachusetts businesses with one to four employees across industries.
  • Industry recommendations: Rates for businesses with one to four employees, keeping company size consistent when comparing business types.
  • Employee-size comparisons: Pricing aggregated across industries to show how rates change by workforce size.

These Massachusetts rates are estimates rather than personalized quotes. Actual premiums can vary based on business classification, claims history, revenue or payroll, coverage limits, deductibles and endorsements. Compare quotes using the same coverage terms.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Creative and Health Care Professionals

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford is most often cheapest for creative professionals and health care providers throughout Massachusetts, ranking first across 32% of business types analyzed. Most small businesses pay an average of $139 per month for general liability coverage, 15% below the Massachusetts average. The Hartford offers savings for health care practices like home health care agencies and audiology clinics, beauty and wellness businesses, including nail salons and hair salons, and creative services such as photography and music instruction.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Beauty, Body and Wellness Services, Education, Financial Services, Health Care and Medical, Nonprofit and Associations, Retail and Product Rental, Tech/IT
  • Employee count: One to 49 employees

Not a fit? Jump to: ERGO NEXT or Thimble or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Trades and Personal Services

On ERGO NEXT's site
COMPANY HIGHLIGHTS

Small businesses pay about $145 a month for general liability coverage with ERGO NEXT, which works out to roughly $281 a year less than the Massachusetts average. ERGO NEXT is the cheapest insurer for 31% of business types in the state, most often for hands-on trades and personal services. The savings are especially strong for food and beverage businesses like food trucks and mobile caterers. Hospitality businesses such as hostels also save, as do service-based businesses like beauty salons and HVAC contractors.

Most often cheapest for these business profiles:

  • General industries: Agriculture and Natural Resources, Childcare Services, Consulting Services, Food and Beverage, Manufacturing, Marketing and Communications, Other Professional Services, Pet Care Services, Repair and Maintenance, Transportation and Logistics, Wholesale and Distribution

Not a fit? Jump to: The Hartford or Thimble or biBerk

Thimble

Thimble: Cheapest for Heavy Construction and Specialty Contractors

COMPANY HIGHLIGHTS

Thimble is most often the cheapest option for heavy construction and specialty contractors in Massachusetts, at $153 a month for general liability. That's 9% below the state average, a savings of about $189 a year. It ranks first for 5% of business types analyzed, concentrated in roofing, electrical, pest control and lawn care.

Not a fit? Jump to: The Hartford or ERGO NEXT or biBerk

biBerk

biBerk: Cheapest for Fitness Centers and Cleaning Companies

COMPANY HIGHLIGHTS

Solo operators save around $154 annually with biBerk, paying $70 monthly for general liability coverage that runs 10% below typical state pricing. Most small businesses have a slightly higher premium of $156 monthly, saving around $151 annually. 

biBerk is the most affordable provider for a fourth of the business types analyzed throughout Massachusetts and offers the best rates for cleaning services like janitorial work and house cleaning, fitness businesses, including yoga studios and personal training. It's also a cheap alternative for health care practices, hospitality operations and real estate services.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Recreation and Sports
  • Employee count: Sole proprietors

Not a fit? Jump to: The Hartford or ERGO NEXT

Is the Cheapest General Liability Insurance Right for Your Massachusetts Business?

A cheap general liability policy may handle common claims, such as a customer injury or accidental property damage. But the lowest-priced option still needs to fit how your business operates. Risks can look different for a coastal business, a company working in older buildings or a seasonal operation. These four examples show where coverage details can matter.

  • Winter liability and seasonal closures: A Salem tour company's budget insurer took six weeks to respond after a guest slipped on ice. The business missed prime March bookings and paid legal fees out of pocket in the meantime.
  • Maritime and waterfront operations: A Newburyport marina operator discovered his cheap policy excluded slip rentals and harbor services. When a boat was damaged during docking, he was personally liable for $180,000.
  • College town event liability: An Amherst landlord's $1 million policy didn't cover a graduation party deck collapse that injured eight guests. He paid $200,000 out of pocket, beyond his policy limit.
  • Historic district building constraints: A Beacon Hill shop owner's budget insurer covered standard repairs after a customer injury. It refused to pay the $40,000 in historic preservation upgrades the city required.

Low-cost policies can suit your business if it covers all the work you do. But if you have more layered coverage requirements, I'd consider looking for the best business insurance policy for your business, rather than just focusing on the cheapest one.

How to Get Cheaper General Liability Insurance in Massachusetts

Affordable general liability insurance in Massachusetts doesn't require bare-minimum coverage that leaves you exposed to claims. Pricing strategies and risk management practices that insurers reward can cut your costs without cutting your protection.

  • swipe icon

    Compare general liability quotes using the same limits

    Ask one insurer for $1 million and another for $2 million, and you're comparing two different products. You won't learn who has the best price. When you compare business insurance quotes, give every insurer the same limits, like the standard $1 million per occurrence and $2 million aggregate. That way the lowest quote really is the lowest rate for the same protection.

  • loanReview icon

    Ensure your business classification (class code) is correct

    The class code on your policy drives your base rate, and the wrong one can mean hundreds or thousands in extra premiums. Picture a coffee shop in Worcester coded as a "restaurant with full kitchen" when it's really a "café with limited food prep." Insurers assume more burn and slip risk with full cooking, so that shop overpays. Check with your agent that your code fits your real operations. A home-based graphic designer and a design firm with a commercial studio and walk-in clients shouldn't pay the same rate.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Don't buy the highest limits just because they're available. Base them on what could realistically go wrong in your work and what your contracts demand. A Somerville photographer shooting small events probably won't need more than $1 million per occurrence, because the usual claims are damaged equipment or a minor injury to a client. If a venue asks for $2 million, though, that's your minimum no matter how low your risk is. Weigh your real exposure against any general liability requirements and buy limits that satisfy both, with nothing extra.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    A higher deductible can lower your premium, but only raise yours if you can afford the out-of-pocket cost when a claim happens. A consulting firm in Newton with $20,000 in cash reserves might save $400 a year by moving from a $1,000 deductible to a $2,500 one. That's a smart trade if the firm rarely files claims and can cover the higher amount without strain.

    The same move could backfire for a landscaping crew in Cambridge that runs month to month on tight cash flow. A $2,500 deductible on a slip-and-fall claim could force them to delay payroll or skip equipment repairs. Weigh your annual savings against the added risk, and raise your deductible only when you have the money on hand to cover it.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Bundling general liability and property coverage into a business owner's policy (BOP) can save 15% to 25% compared with buying each one separately. It works best for businesses that need both, like a retail shop in Salem with its own building and inventory.

    A marketing consultant in Boston who works from a co-working space would be paying for property coverage they don't need, which can cost more overall than the liability discount saves. Compare the price of a BOP with standalone general liability to see whether you're actually saving money or paying for coverage you won't use.

  • takingNotes icon

    Lower your claim risk in ways Massachusetts insurers reward

    Insurers price policies on how likely a claim is, so showing that you take safety seriously can earn you a lower rate. Massachusetts businesses can cut their claim exposure with steps insurers pay attention to during underwriting:

    • Winter maintenance protocols: Keep a written snow and ice removal schedule, stock salt and save records showing your sidewalks stayed clear during nor'easters and freezing weather.
    • Historic building compliance: Keep fire suppression systems maintained, document structural inspections and keep permits current for renovations. This matters most in the older buildings common in Boston and Cambridge.
    • Coastal weather preparedness: Secure outdoor equipment before storms, keep backup power running for critical systems and write down your storm-readiness procedures if you're on Cape Cod or the North Shore.
    • Seasonal staffing safety: Train temporary workers hired for the summer tourist season or the fall on the hazards of the job, and keep records of the training and every safety orientation.
    • Maritime operation standards: If you run a waterfront or harbor business, inspect life jackets, keep vessel maintenance schedules, verify captain credentials and log your safety equipment.

    Some insurers give discounts for these practices. Others build them into your overall risk assessment and pricing

Affordable General Liability Insurance in Massachusetts: Bottom Line

Which insurer has the best price comes down to what you do and where you do it. A Salem tour operator, a Framingham IT consultant and a Lowell roofing contractor will all get different rates. Start with the industry breakdowns to find carriers that treat your kind of work fairly, then ask each one for a quote with the same limits and compare.

Cheapest General Liability Insurance in Massachusetts Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

Consider which providers price different coverage types lowest to better manage y our insurance costs. While general liability addresses more business risks, it doesn't cover everything. The more policies you have in your mix, the higher your costs become. Use this resources to see our recommended carriers.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com