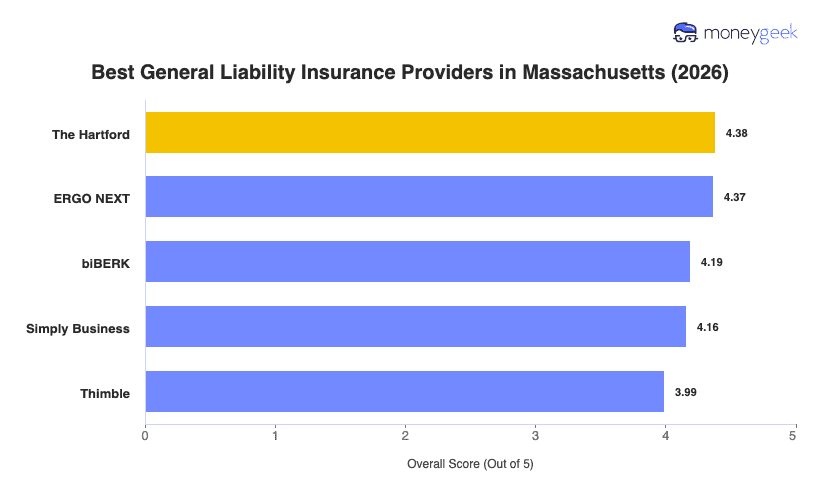
Best General Liability Insurance Companies in Massachusetts

Quotes from 10 insurers across 25 industries and their respective average rates helped me determine the best general liability providers in Massachusetts. Cost, however, wasn't my only basis. I also researched how each insurer deals with different businesses. That means looking at how much they ask about work to produce an accurate estimate and whether they provide resources help manage risks.

At the top of my list are:

  • Choose if you offer professional services: The Hartford
  • Choose if you prioritize customer experience: ERGO NEXT
  • Choose if your business has lower risks: biBerk
  • Choose if you want to compare carriers: Simply Business
  • Choose if you want on-demand coverage: Thimble

For our Massachusetts general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Massachusetts's small businesses, while weighting results to ensure broader industry and location representation across Boston, Worcester, Springfield, Cambridge and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 2,000 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Massachusetts businesses consistently across different industries and regions. We then rated each company across categories of affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Massachusetts, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

2,059

Customer Experiences Analyzed

The Hartford

The Hartford: Best Overall, Best for Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks first overall in our analysis of the best general liability insurance companies in Massachusetts, with the lowest rates across 17 of 25 general industries. Professional services, tech, education and health care businesses save 14% to 31% under the state benchmark. The Hartford is also the top choice for all small businesses with employees.

The insurer leads in policy servicing and claims handling, though coverage requires working through an agent instead of buying online instantly. Massachusetts businesses say the slower buying process pays off. The Hartford's local agents in Boston and Worcester have deep familiarity with Massachusetts coverage requirements.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Customer Experience

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT leads customer experience with instant online quotes that take 10 minutes or less and same-day certificate downloads. That’s a buying process Massachusetts sole proprietors and small teams report as significantly faster than traditional agent-based models. It also has top-ranking digital policy management tools for certificate generation and account changes, though customer support relies on chat and email rather than dedicated phone reps or account managers.

It ranks second for affordability at $143 monthly, saving hands-on businesses like construction, repair, food service and hospitality 22% to 32% compared to the state benchmark. It’s also the best option for sole proprietors, giving them 14% savings. Coverage options rank lower, as its streamlined policies focus on standard endorsements rather than specialized options, and claims resulting in lower settlement fairness scores and communication gaps that two Massachusetts businesses in the Boston area specifically flagged.

Learn More: ERGO NEXT Business Insurance Review

biBerk

biBerk: Best for Lower-Risk Service Businesses

COMPANY HIGHLIGHTS

biBerk costs $156 a month, or $1,876 a year, making it the fourth most-affordable insurer for Massachusetts small businesses. It ranks third overall. Most businesses save around 9% under the state benchmark. Sole proprietors do slightly better, at 10%. Hospitality, fitness services, real estate, cleaning and recreation businesses save the most: 17% to 30% under benchmark rates.

Berkshire Hathaway backs biBerk with an AM Best A++ rating, and biBerk's endorsement options cover most common requests. Getting a policy takes little effort. Coverage can start the same day or the next. Policy management and claims handling land closer to average: BBB and Trustpilot reviews cite slow endorsement turnaround and claims service that gets the job done without excelling.

Learn More: biBerk Review

Simply Business

Simply Business: Best for Comparing Carriers

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business operates as an online broker, matching businesses with carriers instead of underwriting policies itself. Coverage options rank fourth here for one reason: actual limits, sublimits and endorsements depend entirely on which carrier ends up underwriting the policy. Businesses get instant quotes from three to five Massachusetts-licensed insurers through the platform, then manage certificates from one dashboard.

Pricing tells a different story. At $168 a month, Simply Business sits at the state benchmark, and most businesses save just 3%. Professional services, construction, agriculture and marketing businesses actually pay 11% to 16% above the Massachusetts average.

Learn More: Simply Business Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

Thimble offers instant online quotes, immediate certificate downloads and flexible policy terms. Unlike traditional insurers, it offers monthly and per-project/on-demand coverage rather than annual-only policies, but endorsement options are limited to basic additional insured and waiver of subrogation. BBB and Trustpilot reviews back up lower customer ratings for claims handling, citing low settlement offers and slow processing.

Thimble is the most affordable option in only one industry: construction. Construction companies pay an average of $153 monthly and can save as much as 22%. More than half of the industries in our analysis, including hospitality, marketing, nonprofits and retail, pay 3% to 31% above state benchmarks.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Massachusetts Businesses

An insurer may quote your business but still fall short of the requirements in your lease or client contracts. As you look for the best general liability insurance, consider what the policy will cost over time and how the provider handles the requests you’ll make after buying it.

How to Choose the Best General Liability Insurance in Massachusetts

Six steps lets you get general liability insurance that's best for your business without going through every provider on the market. Our guide makes sure you cover multiple angles and not jut go with the carrier with the lowest cost.

  1. 1
    Optimize your payment and coverage structure

    Decide how you'll pay for coverage and how much liability protection your Massachusetts business needs. Your payment schedule sets when premiums come out of your cash flow. Your limits set the most the insurer can pay on a covered claim.

    Ask yourself:

    • Can you pay annually upfront, or do you need monthly payments to match revenue cycles?
    • Will seasonal work, such as landscaping or tourism, require flexible payments during slow months?
    • Do clients visit your location, or do you work on their property?
    • Will contracts require proof of insurance with specific limits before projects start?

    Annual payment costs 5% to 10% less, while monthly payment breaks the cost into smaller pieces and usually suits seasonal revenue better. Limits of $1 million per occurrence and $2 million aggregate work for most operations and meet common general liability requirements. Consider higher limits if you regularly take on large commercial contracts.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority
    • What matters most to you comes down to your cash flow, how much help you'll need from your insurer and how much liability risk you carry. When providers look about even, that priority makes the call.
    • Affordability comes first if your margins are thin or a past claim pushed your rates up. New businesses often land here too, because steady insurance costs make hiring and expansion easier to plan.
    • Customer experience comes first if vendor contracts have you requesting COIs often, or if seasonal staff means frequent policy changes.
    • Coverage options come first if you face risks beyond what a standard policy covers, like client contracts that call for specific endorsements.
  3. 3
    Shortlist two to three providers

    You don't need to research every general liability insurer in Massachusetts. Some won't fit your business size or industry, and others won't cater to your priority area. Narrowing the field to two or three lets you focus on the details that affect your operations.

    Look for providers that work regularly with businesses like yours and offer the payment and coverage structure you need. Before you dig into the details, confirm each finalist meets your baseline requirements.

  4. 4
    Double-check for dealbreakers before investing more time

    Before you spend more time on the details, make sure each finalist can meet your non-negotiables. Common examples include:

    • Certificate turnaround time: Some insurers issue certificates within 24 to 48 hours, while others take a week. Construction firms and event planners often can't wait that long once a contract deadline hits.
    • Additional insured endorsements: Ask whether the insurer can add landlords, clients or municipal agencies as additional insureds. Many Massachusetts commercial leases and public project contracts require this before work starts.
    • Payment flexibility: Find out whether monthly payments are available or only annual billing. Seasonal businesses need payments that line up with when revenue comes in.
    • Coverage for your industry: Not every carrier writes policies for every business type. Some won't cover restaurants with fryers or outpatient medical practices.
  5. 5
    Compare your finalists using the same three lenses

    Line up your finalists side by side before you pick one. Judging all three areas is how you find the provider that really stands out.

    • Affordability: Find out how premiums change at renewal and whether a payroll audit could raise your costs unexpectedly. Make sure the payment schedule fits a seasonal business, and see how clearly the insurer explains rate changes.
    • Customer experience: See how quickly each insurer issues certificates. Ask how easy it is to adjust coverage for seasonal workers or new locations, and whether you can get a live person fast when you file a claim.
    • Coverage options: Look at whether each insurer offers the endorsements your contracts call for. Check that the limits can scale as you grow, and watch for features like automatic coverage for new equipment or locations.
  6. 6
    Use quotes as the final confirmation step

    Ask for business insurance quotes that use your actual details: industry classification, payroll, revenue and location. Your research up to this point relied on general estimates. A real quote shows whether your own profile triggers rate adjustments, and it can surface coverage restrictions or eligibility issues your earlier research missed.

Best Small Business General Liability Insurance in Massachusetts: Bottom Line

The strongest Massachusetts general liability insurer balances competitive pricing with fast certificate turnaround and scalable coverage, rather than excelling in just one area. The Hartford, ERGO NEXT, biBerk, Simply Business and Thimble lead our rankings, but fit varies by your industry risks, employee count and how often you need policy changes. Use this framework to match coverage to your actual operations and how you'll interact with your insurer.

Best General Liability Insurance for Small Business in Massachusetts Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

The best small business insurance in Massachusetts include more than just general liability coverage. Use the resources below to see which providers we recommend for other coverage types you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com