Cheapest Louisiana General Liability Insurance Companies

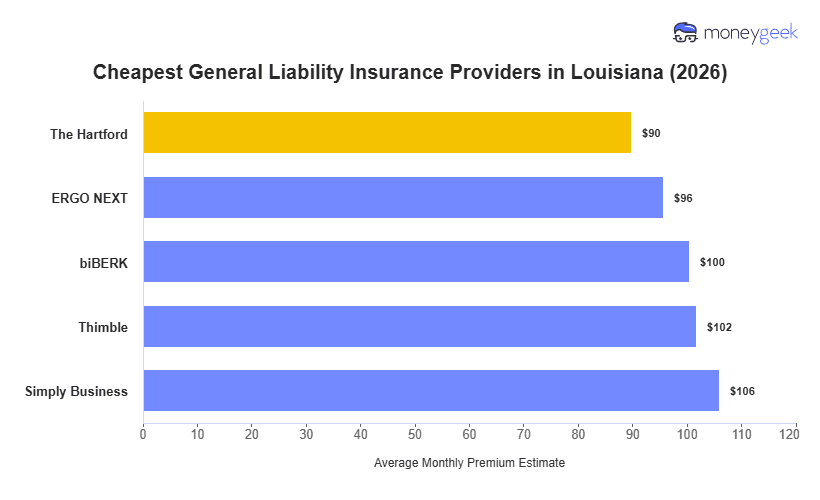
My analysis comprised of general liability quotes for over 400 industries across Louisiana with standard liability limits of $1 million per-occurrence (per claim)/$2 million aggregate (total). The three providers that consistently offer the cheapest general liability insurance in the state are:

  • The Hartford: Cheapest for creative professionals, educators and health care providers (photography, videography, financial advisors, dentists, physical therapists)
  • ERGO NEXT: Most affordable for hands-on trades and customer-facing operations (construction contractors, repair shops, hospitality businesses, transportation services)
  • biBerk: Lowest rates for service businesses with physical locations (cleaning services, fitness studios, yoga instructors, real estate agencies, recreation facilities)

Your actual general liability rate depends on your industry, revenue, employee count and claims history. Use this as a starting point, then compare quotes built for your business.
The Hartford$90$1,07715%
ERGO NEXT$96$1,1489%
biBerk$100$1,2045%
Thimble$102$1,2214%
Simply Business$106$1,2720%
Coverdash$114$1,371-8%
Progressive Commercial$116$1,386-9%
Hiscox$121$1,454-15%

Louisiana’s cheapest general liability rankings use average rates for businesses with one to four employees across industries. Industry recommendations keep that employee range constant to make business type the main variable, while employee-size comparisons combine pricing across industries to show how costs change as workforce size increases. The analysis draws on more than 20,000 standardized estimates from 10 major insurers, covering 408 business types across 25 industries and businesses with zero to 49 employees.

All estimates assume $1 million per occurrence/$2 million aggregate coverage and incorporate modeled revenue and payroll. These Louisiana figures are estimates, not personalized quotes. Actual premiums can vary based on business classification, claims history, revenue or payroll, coverage limits, deductibles and endorsements, so compare quotes using the same coverage terms.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Creative Professionals and Health Care Providers

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford delivers the lowest rates most often for Louisiana creative professionals, educators and health care providers. Businesses like photography studios, financial advisors, dental practices and physical therapy clinics save an average of $16 monthly (10% below Louisiana's average) with The Hartford. For small operations with one to four employees, monthly premiums start around $90.

Most often cheapest for these business profiles:

  • General industries: Arts, Media & Entertainment, Education, Financial Services, Health Care and Medical
  • Employee count: One to 49 employees

Not a fit? Jump to: ERGO NEXT or biBerk

ERGO NEXT

ERGO NEXT: Cheapest for Hands-On Trades and Customer-Facing Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT offers the lowest rates across the widest range of Louisiana industries, ranking first in 146 out of 408 business types. Most businesses pay about $96 per month for general liability insurance, 10% lower than Louisiana's average. Businesses in hands-on trades and customer-facing operations like construction contractors, repair shops, hospitality businesses and transportation services see the biggest savings at 40%. 

Most often cheapest for these business profiles:

  • General industries: Construction and Contracting, Consulting Services, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Nonprofit and Associations, Other Professional Services, Pet Care Services, Repair and Maintenance, Transportation and Logistics, Wholesale and Distribution

Not a fit? Jump to: The Hartford or biBerk

biBerk

biBerk: Cheapest for Service-Based Businesses

COMPANY HIGHLIGHTS

biBerk delivers strong savings for service businesses with physical locations. Cleaning services, fitness studios, real estate agencies and recreation facilities save between $13 and $17 monthly. Solo operators, like massage therapists, yoga instructors and sports coaches, see especially low rates, with monthly premiums starting around $52, 9% below Louisiana's average. Outside of these, most Louisiana businesses pay monthly premiums starting around $100, saving an average of $5 monthly compared to the state average.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Real Estate and Property Services, Recreation and Sports
  • Employee count: Sole proprietors

Not a fit? Jump to: The Hartford or ERGO NEXT

Is the Cheapest General Liability Insurance Right for Your Louisiana Business?

The lowest premium only works if the policy covers your actual risks. For example, Lafayette contractors installing HVAC systems in refineries deal with equipment damage and worker injury exposure that generic policies might not adequately cover. Your industry and operations determine what protection you need, not what costs the least.

Before buying based on price, check these four factors:

  • Policy limits that cover your highest-risk scenarios and any coverage requirements in client contracts
  • A deductible you can afford to pay without disrupting cash flow when a claim happens
  • Add-on coverages that fit your industry as your business expands and takes on new work
  • Strong claims support when you need it, not just attractive rates during the buying process

Don't trade adequate coverage for a lower premium. If money's currently tight, buy basic coverage that meets your contracts, then add broader limits as revenue grows. If you find that your coverage needs are more complex, however, I suggest you focus on finding the best general liability insurance policy, rather than just the cheapest.

How to Get Cheaper General Liability Insurance in Louisiana

  • swipe icon

    Compare general liability quotes using the same limits

    You can't tell which insurer charges less if you're comparing different coverage amounts. A $500 annual premium for $500,000 in coverage isn't cheaper than $800 for $2 million. You're just buying less protection.

    Pick your coverage limits first, then get and compare business insurance quotes for those exact amounts from multiple Louisiana insurers. For example, contractors working at Louisiana refineries and chemical plants often need $2 million aggregate to qualify for jobs. Once you know that's your floor, request $1 million per occurrence/$2 million aggregate from every carrier you're evaluating. The insurer quoting $720 annually costs less than one quoting $850 only when both quotes cover the same exposure.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers assign classification codes to your work based on risk levels. The wrong code means you're paying premiums for risks you don't actually have.

    Pull out your policy and read the business description. If you run a Shreveport HVAC repair shop but the policy lists you as a general contractor, you're paying for liability exposure from construction work you don't do. Contact your Louisiana insurer with documentation showing your actual operations, like service invoices, your website and licensing paperwork. Correcting your classification from broad contractor codes to specialized trade codes typically drops premiums 20% to 30%.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    Base your limits on your general liability requirements. That's from what client contracts require, what damage your operations could realistically cause and what you can afford. Don't automatically buy $2 million aggregate because it sounds safer.

    Check your contracts first. Most Louisiana clients requiring insurance specify $1 million per occurrence. If you work from home in Metairie doing design or consulting, that's probably enough. If you're installing equipment at Lake Charles refineries or Baton Rouge chemical plants, those facilities set higher minimums. Buy what your contracts demand, then evaluate whether your actual work creates exposure beyond that.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    Higher deductibles cut your premium but mean you pay more out of pocket when claims happen. Choose a deductible based on what you can actually access in cash without disrupting operations.

    Paying annually instead of monthly saves 5% to 8% with most Louisiana insurers, but timing matters. A Slidell contractor with strong spring revenue can pay upfront in April. A New Orleans restaurant dependent on festival seasons needs to avoid locking up cash right before Jazz Fest or French Quarter Fest when they're stocking inventory and hiring extra staff. Pick your payment schedule based on when your business has money available, not just when the policy renews.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Bundling multiple policies with one Louisiana insurer can save 10% to 25%, but only when the package actually costs less than buying coverage separately.

    Calculate what you'd pay for each coverage individually first. Add those numbers together. Then get quotes for bundled packages like a Business Owner's Policy (BOP) that combines general liability with property coverage. The cost of a BOP makes sense when the total cost is lower than what you'd pay separately. But if you're paying extra on individual coverages just to qualify for a bundle discount, you're not saving money. Instead, you're subsidizing the package with higher premiums. Compare the math before committing to one carrier for everything.

  • takingNotes icon

    Lower your claim risk in ways Louisiana insurers reward

    Louisiana carriers track which businesses in your industry file claims and why. Prove you've addressed those specific risks through training, equipment or procedures, and you'll see premium reductions of 10% to 20%. Consider the following:

    • Document alcohol service training for staff: Louisiana's hospitality and festival economy means many businesses serve alcohol. Documented responsible vendor training and checking procedures reduce over-service liability claims that lead to injuries.
    • Maintain food safety certifications and procedures: Louisiana's seafood restaurants, catering operations and food vendors face contamination risks in hot, humid conditions. Dated temperature logs, storage protocols and certified food handler training reduce illness claims.
    • Require contractor licensing and safety documentation: Louisiana's post-hurricane reconstruction and coastal restoration work requires proper licensing verification. Documented subcontractor insurance, safety meetings and job site protocols reduce third-party injury claims from your contracted work.
    • Install commercial security systems in retail and hospitality areas: New Orleans, Baton Rouge and other Louisiana cities see property crime that affects businesses. Monitored alarms, cameras and documented security procedures lower customer theft accusations and false injury claims.

Affordable General Liability Insurance in Louisiana: Bottom Line

Insurers don't price all Louisiana businesses the same way: a Thibodaux seafood distributor gets quoted differently than a Shreveport IT consulting firm because the risks differ. Your best rate depends on what you do, where you operate and how large your business is.

Use these rankings to identify carriers that price your industry competitively in Louisiana, then request quotes with identical coverage limits from multiple insurers. Buy adequate protection at the best available price. Don't overpay for the same coverage or choose insufficient limits just to save money.

Cheapest General Liability Insurance in Louisiana Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

Each policy type you add to your insurance is increases your total cost. Use the page below to see which providers have the cheapest rates for other coverages you might need on top of general liability.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com