Best Business Insurance Companies For Electrical Contractors

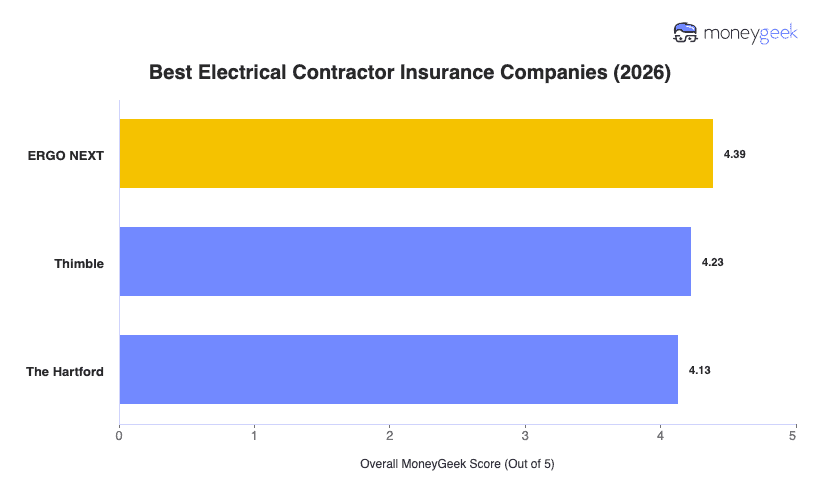
These three providers topped my analysis for the best business insurers for electrical contractors:

  • Choose if you have straightforward coverage needs and want affordable premiums: ERGO NEXT
  • Choose if you want per-project coverage or short-term policy options: Thimble
  • Choose if you want risk-management resources and have complex coverage requirements: The Hartford

A low rate doesn’t tell me whether an insurer will be easy to work with once an electrical job is underway. A general contractor may need updated proof of insurance before work starts, or the business may need to adjust its policy as the type of work changes. I accounted for both price and how practical the insurer is to use.

Affordability makes up 50% of my score, customer experience 30% and coverage options 20%. I give price the largest share because it affects your recurring insurance costs, while the other two categories help me judge whether the insurer can support the way electrical contractors operate.

  • Affordability: I used the same electrical contractor profile and equivalent coverage assumptions for every insurer. That gives me a like-for-like rate comparison rather than rewarding a company because the quote was built on different inputs.
  • Coverage Options: I focused on how well an insurer can support electrical contracting risks and job requirements, not simply how many policy types it sells. I also considered whether the setup can adapt as the work your business takes on changes.
  • Customer Experience: I looked at the service you may rely on once you have a policy, including COIs, additional insured changes, online policy updates and claims support. For contractors moving between jobs, those day-to-day interactions can matter as much as the initial buying process.

I used AI to assist with parts of the research, but I made the final conclusions and judgments in my analysis.

See our full methodology.

ERGO NEXT

ERGO NEXT: Best for Straightforward Coverage Needs and Low Premiums

On ERGO NEXT's site
checkmarkpros
  • Lowest rates for electrical businesses with employees

  • Fast COIs and additional insured updates

  • Easy online policy management between jobs

closecons
  • Expensive for solo electricians

  • Limited support for complex contested claims

  • Tools coverage limit low for high-value equipment

COMPANY HIGHLIGHTS

ERGO NEXT is the best insurer for electrical contractors who regularly work with general contractors or property managers that want proof of insurance before a job starts. You can get a quote and bind coverage entirely online, then access your certificate of insurance as soon as the policy's active. The entire process takes about 10 minutes. It also has a COI Analyzer, where you can upload a sample certificate and ERGO NEXT uses it to generate a customized COI, which can save time when different jobs require different certificate wording or details. This provider is also the cheapest provider in my study, with rates 24% below the industry average. That saves about $541 per year, which you could use to replacing worn tools or buying safety equipment.

Learn More: ERGO NEXT Business Insurance Review

Thimble

Thimble: Best for Per-Project Coverage and Short-Term Policy Terms

checkmarkpros
  • Flexible coverage for short or irregular projects

  • Monthly policies can pause during downtime

  • Fast COIs for same-day jobs

closecons
  • Low limits for high-value tools

  • No professional liability for advisory work

  • No workers’ comp or commercial auto

COMPANY HIGHLIGHTS

If you take short projects or seasonal overflow work, including one-off subcontracting jobs, I’d recommend Thimble. It’s the only provider in my study offering coverage by the hour, day, job, month or year. Monthly policyholders can pause general liability coverage for up to 30 days, which helps if you finish a commercial rewiring project and have a few weeks before the next contract starts. Thimble is affordable and easy to buy from, but its coverage is narrower. Besides general liability, it also offers inland marine for electricians, but businesses with employees or more complex needs have to get additional coverage elsewhere.

Learn More: Thimble Business Insurance Review

The Hartford

The Hartford: Best for Risk-Management Resources and Complex Coverage Requirements

On The Hartford's site
checkmarkpros
  • Broad coverage for larger electrical projects

  • Protects owned and rented contractor equipment

  • Contractor-focused risk management support

  • Affordable rates for solo electricians

closecons
  • Less suited to same-day coverage needs

  • More than simpler electrical businesses need

COMPANY HIGHLIGHTS

Your insurance needs get more complex when you move beyond residential service calls into larger commercial projects or crews with more equipment. In that case, I’d consider The Hartford. Its contractor’s equipment insurance can protect owned and rented gear, which fits electricians moving costly tools between multiple jobsites. The Hartford also offers construction-specific risk engineering, including jobsite surveys and safety guidance, making it a stronger fit for contractors managing crews or higher-risk projects. It costs more in my study, but if you want hands-on claims support, you'll appreciate its specialized claims team when a loss becomes complicated.

Learn More: The Hartford Business Insurance Review

What Types of Insurance Do Electrical Contractors Need?

Electrical work can create problems during a job and after you’ve finished the installation or repair. General liability’s products-completed operations (PCO) coverage responds if faulty wiring later starts a fire or an installed fixture injures someone. Your starting insurance bundle should also protect the tools you rely on between jobs, from multimeters to power tools. ools and equipment insurance can cover them if they’re damaged or stolen, including from your work vehicle, which is the most common claim for this coverage.

After that, add policies to your mix depending on the services you offer and how your business is set up.

Third-party injuries and property damage, such as damaging a customer’s wall while running new wiring
Before your first paid job
A routine service call can still leave you responsible for someone else’s injury or damaged property. Clients and general contractors may also ask for proof of GL before letting you onto a jobsite.
Tools and equipment
Portable gear damaged or stolen away from your shop, including meters, testers and power tools
Once you carry valuable tools between jobs

Fluke’s 117 electrician’s multimeter sells for about $305. Lose a few core tools at the same time and replacement costs climb fast. It also causes delay if your work depends on having that gear ready for the next job.

Accidents involving business-owned vehicles, such as a service van hitting another car between jobs
Once you use a company vehicle for work

Your driving exposure starts before you reach the jobsite. Light trucks, including pickups and vans, were the striking vehicle in about 245,000 injury-producing rear-end crashes.

Employee injuries and illnesses, including shocks, falls or strains on the job
When you hire workers, subject to state rules

BLS recorded 59 fatal occupational injuries in the electrical contracting and wiring installation industry in 2024. One serious jobsite accident can mean medical costs, lost wages and survivor benefits that workers’ comp helps cover.

Contractors’ E&O (professional liability)

Financial losses from design or professional mistakes, such as an electrical plan that fails code
Once you provide design or technical recommendations

One Travelers claim shows how expensive a design mistake can get. An electrical contractor designed a stadium scoreboard that failed code inspection, forcing the system to be completely rewired.

Property kept at your business location, such as stored wire, fixtures and equipment
Once you have a shop, office or storage space
A shop or storage space can hold materials and equipment for several jobs at once. Commercial property helps you replace those after a covered loss so one incident doesn’t disrupt multiple projects.
Installation floater
Materials awaiting installation, such as panels, fixtures or electrical equipment in transit or at a jobsite
When projects involve higher-value materials
If you buy materials before the job starts, you could be stuck replacing them if they’re damaged or stolen before installation. An installation floater can cover that gap while the materials are in transit or being stored for the project.

How Much Does Electrical Contractor Insurance Cost?

Electrical contractor insurance costs can range from $27 per month for tools and equipment insurance to $379 for general liability. Your actual premium depends on the type of electrical work you do and the project sizes you take on.

The policies in your coverage mix is a main determinant of your total insurance cost. The average cost of individual policies are:

What Are These Costs Based On?

A solo electrician handling residential service calls won’t be priced the same as a contractor wiring commercial sites with a crew and work vans. Our business insurance calculator can give you an estimate based on the way your electrical business operates.

Electrical Contractor Insurance Cost Calculator
Select Coverage Type
Select State
Select Employee Cand
Select Vehicle Type
Average Monthly Cost—

How To Buy The Best Electrical Contractor Insurance

It’s easy to lose track of the details that shape the right insurance for your business. I've broken down the process into seven steps and created a downloadable buying checklist you can use as a guide while you gather quotes, review contracts or talk to an agent.

  1. 1

    Identify Required Coverage

    Check your legal and contract requirements before anything else. State law mandates workers’ comp when you hire, though thresholds vary between locations. A business-owned van or truck needs commercial auto that meets your state’s minimum liability rules. 

    Your contract may add another layer. General liability may be required for certain electrical jobs even when licensing rules don’t mandate it. A general contractor or property manager might require a certificate of insurance, which proves you have coverage. Some clients could ask you to add them as additional insured, which gives them protection under your policy for certain claims.

    Read More: Business Insurance Requirements

  2. 2

    Match Your Remaining Risks to Coverage

    Once you’ve handled your required policies, take a closer look at the risks your actual job creates. If your multimeters or testers travel with you, tools and equipment coverage protects them if they’re stolen or damaged on the way to a job or while you’re working. If you create electrical designs or make technical recommendations, you have professional liability exposure.

    Your needs can change with how you operate, too. A shop full of stored materials makes commercial property coverage relevant, and it makes sense to include cyber insurance if you keep customer or payment data electronically.

  3. 3

    Set Limits Around the Jobs You Take

    A policy can satisfy a contract requirement and still leave you paying the difference if a claim exceeds your limit. Say a general contractor requires $1 million in general liability, but faulty wiring causes a fire with $1.4 million in covered property damage. After the policy pays its limit, your business could be responsible for the remaining $400,000. I’d use the contract minimum as a starting point, then choose a limit that reflects what a serious loss on that job could actually cost.

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Before You Quote

    High-voltage or industrial jobs can narrow your provider options because not every insurer will cover the same electrical work. I’d check whether a carrier accepts the kind of projects you take on before asking for a quote. Some insurers rule out certain activities completely, which saves you time if you figure it out early.

    Then think about how you’ll deal with the insurer after you buy coverage. Think about how you want to manage the policy once it’s active. If you prefer handling routine changes yourself, strong online tools might be a priority. Electrical contractors taking on larger commercial work might find access to specialists who can help when the policy or claim gets complicated more valuable.

  5. 5

    Compare Quotes Using the Same Inputs

    A cheaper quote only means something if it gives you the same financial protection as the others you’ve requested. When you compare business insurance quotes, give each insurer the same payroll and business details, then match the limits and deductibles. Include the same vehicle use or tool values where those coverages apply. If one insurer quotes $1 million in liability coverage and another uses a lower limit, the cheaper premium isn’t really an apples-to-apples comparison.

  6. 6

    Review the Policy Before Buying

    Before you sign, read the policy closely for anything that could narrow the protection you expect. If you use subcontractors, check whether it covers their work because a claim can still come back to your business even when someone else did the job. Check separate limits for tools kept in a vehicle or materials waiting to be installed. Another thing to look at are definitions. For example, the policy’s definition of when work is “completed” can affect whether a later claim falls under completed operations. Don’t forget to review cancellation and nonrenewal terms so you know how much notice you’ll get if coverage ends. A lapse could leave you unable to meet a client’s insurance requirements and completely exposed if a claim happens while you’re uninsured.

  7. 7

    Reassess Coverage When Your Business Changes

    Your insurance needs change over time, and it’s not always because your business is growing. If you let employees go, your workers’ comp exposure changes. Sell a work van and you may no longer need the same commercial auto setup. The opposite is true when you start taking larger commercial jobs or add higher-risk services. I’d review your policies whenever the way you operate changes so your coverage still matches the work you’re actually doing.

Electrical Contractor Insurance: FAQ

To make sure you have all the information you need, I've answered some commonly asked questions related to electrical contractor insurance:

Best Electrical Contractor Insurance: Bottom Line

The best electrical contractor insurance isn't all about provider fit. My analysis put ERGO NEXT, Thimble and The Hartford on top, but the right fit your business best depends on your priority and preferences.

Build your insurance around the electrical work you do now so you know you're getting the best electrical contractor business insurance for your business. Make general liability and tools coverage your starting point, then reassess your needs change as you hire or take on larger projects. Expect to spend between $27 to $379 per month on average, but keep in mind that while this gives you a realistic range for budgeting, your actual rate depends on your risk profile. Compare two or three quotes using the same limits and deductibles, then choose based on the protection you’re actually getting for the price.

Best Electrical Contractor Insurance Chart

Get Electrical Contractor Insurance Quotes

Quote prices can vary widely between insurers, even for similar electrical businesses. Compare a few options before you decide which policy fits your budget and coverage needs.

About Connor Bolton


Connor Bolton, Senior SEO and Content Manager (Business & Pet), MoneyGeek

Connor Bolton is Senior SEO and Content Manager at MoneyGeek, where he leads the business and pet insurance editorial teams. He sets the research framework, data standards and content structure for his team. All content goes through his accuracy review before publication. Connor also writes in-depth guides and has spent more than four years covering insurance products across personal, commercial and specialty lines.

The research infrastructure Connor built covers auto, home, renters, life, health, business and pet insurance across pricing analysis, carrier research, customer experience and coverage evaluation. It includes over 6 million data points for business insurance across 408 industry areas, all 50 states and 16 vehicle types. The pet insurance side covers over 5 million profiles across 18 major providers, 100+ breeds and ages up to 20 years. Connor’s insurance research and his team's work have been cited by the U.S. Chamber of Commerce, Allstate, Liberty Mutual, CBS News, Forbes and LegalZoom.

Connor also talks with underwriters and carrier liaisons at Ethos, The Hartford, ERGO NEXT, Nationwide and State Farm, and monitors business and pet owner communities on Reddit. Those sources shape how his team evaluates carriers, structures rate analysis and writes content for real pet owners.

Questions about MoneyGeek's business or pet insurance content? Reach him at connor@moneygeek.com or on LinkedIn.


Sources