Best Business Insurance Companies For Marketing Consultants

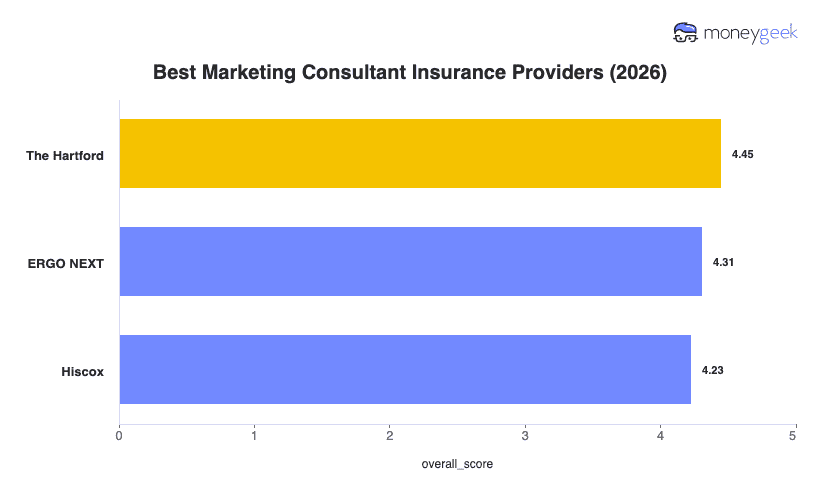
After analyzing major providers to find the best business insurers for marketing consultants, my top recommendations are:

  • Choose if you're a larger firm and prefer dealing with a single carrier: The Hartford
  • Choose if you prefer managing your policy online and often need same-day coverage: ERGO NEXT
  • Choose if you want the broadest professional liability package available: Hiscox

Marketing consultant insurance looks simple until you compare what providers charge and what their policies cover. I weighted my rankings across affordability (50%), customer experience (30%) and coverage options (20%) because price matters, but I also want to know whether the policy and service will still work when you need them.

Here’s what went into my analysis of popular insurers, with AI used to support the research rather than make the final judgments:

  • Affordability: I compared standardized quotes for marketing consultants across states and business sizes, then looked at how costs changed across the coverages we studied.
  • Customer Experience: I reviewed customer feedback and went through each provider’s quote and policy-management process myself to see how easy it is to buy coverage, make changes or get help.
  • Coverage Options: I reviewed policy terms, exclusions and available add-ons, paying closer attention to professional liability and cyber coverage because both can matter heavily for marketing consultants.

See our full business insurance methodology.

The Hartford

The Hartford: Larger Firms and Consultants Who Want to Deal with a Single Carrier

On The Hartford's site
checkmarkpros
  • Cheapest for marketing teams with five or more employees

  • Fast online COIs with no agent back-and-forth

  • Cyber coverage supports consultants handling sensitive client data

  • Keep multiple coverages with one insurance provider

closecons
  • Solo consultants may pay about 2.5 times average rates

  • Professional liability quotes require a phone call

  • Coverage options are limited in some states

COMPANY HIGHLIGHTS

If you’re looking for a strong all-around option for marketing consultant business insurance, I’d recommend The Hartford. Its average premium is 15% below the industry benchmark, and its range of coverage lets your insurance bundle grow along with your business. You might start with professional liability, then add cyber coverage as you take on more client accounts or handle sensitive data. Moving into an office or investing in laptops, cameras and other equipment could also create a need for commercial property coverage. You can’t complete a professional liability purchase entirely online, but the extra steps may be worth it if you expect your insurance needs to become more complex.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Online Policy Management and Same-Day Coverage

On ERGO NEXT's site
checkmarkpros
  • Same-day coverage for time-sensitive client contracts

  • Unlimited COIs at no extra cost

  • Fully online buying process

closecons
  • Pricing rises sharply for teams of five or more

  • Limited support for complex professional liability claims

  • Coverage limits may not suit commercial client requirements

COMPANY HIGHLIGHTS

My analysis found that ERGO NEXT is a strong option for solo marketing consultants and very small firms because its pricing is especially competitive for smaller operations. It also works well if you prefer to handle insurance on your own rather than schedule calls or go back and forth with an agent. That accessibility becomes useful when a new client asks for proof of insurance before work starts. You can apply online, bind your policy and download a shareable certificate in about 10 minutes, so you can get the paperwork handled without slowing down the project.

Learn More: ERGO NEXT Business Insurance Review

Hiscox

Hiscox: Best for the Broadest Professional Liability Package

checkmarkpros
  • Worldwide professional liability coverage for international client work

  • $200,000 copyright and trademark infringement coverage included

  • Retroactive coverage can protect work from prior years

  • PL coverage can extend to work done by freelancers

closecons
  • COIs and policy updates can require more follow-up

  • Claims support scores weaker than other top providers

  • Coverage is not available to businesses in Alaska

COMPANY HIGHLIGHTS

Hiscox would be my preferred provider if my biggest concern is professional liability. You'll find more practical value in its PL policy since its designed for claims tied to the work you perform as a marketing consultant. For example, a client could allege that your campaign strategy caused them to lose sales, or that inaccurate market research led them to make a costly business decision. You also get up to $200,000 in copyright and trademark infringement coverage. That matters if you create ad copy or campaign assets and someone claims you used protected content without permission. The same goes if they say you infringed on a trademark.

Learn More: Hiscox Business Insurance Review

What Types of Insurance Do Marketing Consultant Businesses Need?

A missed deadline or poor recommendation can lead to a professional liability claim if your client says your work caused them financial loss. Professional liability covers that risk, so I’d prioritize it in your coverage mix. I’d also get general liability early. Some clients require it by contract, and its personal and advertising injury coverage can protect against claims involving libel, slander, privacy violations or the use of someone else's advertising idea. If your work involves publishing promotional content or shaping client-facing campaigns, that makes a difference.
Once you start hiring, you'll need to add workers' compensation. Then if you're given account access and begin handling more client data, I'd look into cyber liability.

Claims that your professional work caused a client financial loss, such as a missed launch or faulty recommendation
Once clients rely on your marketing advice to make business decisions
Your advice can influence a client’s budget or business decisions, and a client may hold you responsible if they believe your recommendation caused them to lose money.
Third-party injury or property damage, including accidents at a client’s workplace
Regular client visits or in-person work make this coverage worth carrying

Marketing work can involve published content and reputational claims. Reputation-related claims averaged $50,000, which shows how expensive these disputes can become.

Data breaches, hacks and recovery costs involving sensitive digital information
Handling customer records or working inside client systems creates the trigger

You often work inside client systems or handle customer data. The median SMB breach cost was about $38,000, so one incident can become a major expense for a small firm.

Medical costs and lost wages after an employee suffers a work-related injury or illness
Hiring your first employee may create a legal requirement, depending on your state

Even office-based employees can get hurt at work, and hiring may trigger state coverage rules. NCCI reported that medical costs and wage-replacement payments per claim increased in 2024.

Business equipment and furnishings damaged by covered events like fire or theft
Consider it once replacing your laptops, cameras or office setup would hurt financially
Replacing laptops or production equipment after a fire can get expensive quickly. Fire claims averaged $35,000, a major hit for a small consultancy paying out of pocket.
Liability and vehicle damage from accidents involving business-owned vehicles
A company-owned or leased vehicle usually means personal auto coverage is no longer enough

If your firm owns a vehicle for client visits or production work, one crash can create a costly liability claim. Average bodily injury claims reached $28,278 in 2024.

scale icon
WHY GETTING MARKETING CONSULTANT INSURANCE IS IMPORTANT

It doesn't take a lot for a marketing mistake to become expensive. Say a client claims your recommendation forced them to redo a campaign, which delayed the launch, which lead to lost sales. Even if you dispute the claim, you'll still have to face legal costs or settlement pressure. That’s why I’d view insurance as an investment, rather than a just business expense. Marketing consultant insurance protects you from having one client dispute hit your cash flow all at once.

Coverage also helps beyond paying claims. It affects the kind of work you’re able to take on. Larger clients may require professional liability, general liability or specific coverage limits before they sign a contract. Having the right policies in place helps you satisfy those requirements without scrambling for coverage each time an opportunity comes up.

How Much Does Marketing Consultant Business Insurance Cost?

The type of marketing work you do affects consulting insurance costs for marketing consultants. While individyal policy estimates range from $9 to $114 per month on average, your actual quote will vary depending on whether you do paid media management or campaign execution.

Coverage type costs break down as follows for the profession for a 1 to 4 person business:

What Are These Costs Based On?

Your rates can change based on the size of the accounts you manage and the client data you handle. Use our business insurance calculator to get estimates based on your marketing consultant business.

Estimate Your Marketing Consultant Insurance Cost
Select Coverage Type
Select State
Select Employee Count
Select Vehicle Type
Average Monthly Cost—

How To Buy The Best Marketing Consultant Insurance

Buying marketing consultant insurance gets easier when you work through each decision in order instead of comparing everything at once. I’ve also created a companion worksheet you can download to use as you go through the steps, with space to record what you find and keep your comparisons organized.

  1. 1
    Identify the Coverage You’re Required to Carry

    Start with coverage you’re actually required to have. Hiring employees trigger workers’ compensation requirements under your state’s rules, while a client MSA or agency subcontract could have its own insurance requirements before you can begin work.

    I’d check those contract terms before requesting quotes. A larger client might require specific liability limits or ask to be added to your policy as an additional insured, which gives them protection under your coverage for certain claims. Check first so you don’t buy coverage that falls short of the contract you’re trying to get.

    Read More: Business Insurance Requirements

  2. 2
    Map Your Business Risks to the Right Coverage

    Look at what your marketing work exposes you to. If clients rely on your recommendations or campaign execution, professional liability must be in your policy mix. Handling confidential client information, whether it’s your client’s customer database or mailing list, creates a different risk, which cyber insurance addresses. I’d match each risk to a policy rather than buying a generic consultant package.

  3. 3
    Set Limits Around the Work You Take On

    Don’t choose a liability limit just because it’s the standard option on a quote. I’d start with the requirements in your largest client contracts, then consider how much financial damage a dispute over your work could realistically cause. $1 million per claim is a common starting point for professional liability, but the right limit depends on your contracts and the size of the work you take on. Also, check whether legal defense costs count against that limit. A $1 million policy gives you less room for a settlement if attorney fees are paid from the same amount.

    Read More: How Much Business Insurance Do I Need?

  4. 4
    Research Providers Before Requesting Quotes

    Before you request quotes, I’d look at how each insurer works once you become a customer. Check whether you can make policy changes online and how quickly you can get certificates of insurance (COIs). If you prefer personal help, see whether you’ll have access to an agent or service team when you need one.

    I’d also look at claims support and whether the provider can keep up as your needs change. If you expect to hire or increase your limits, check whether you can add the coverage you need with the same insurer or whether you’ll have to use another provider.

  5. 5
    Compare Quotes with the Same Terms

    A lower premium only means something if you’re comparing the same level of financial protection. I’d line up the coverage limits and deductibles first, then check whether either quote has lower sublimits or missing endorsements. A cheaper quote loses its advantage if it offers lower limits for an important exposure or leaves out coverage included by another insurer.

  6. 6
    Review the Policy Before You Buy

    Before you buy, I’d check the details that can limit your professional liability coverage. Start with the retroactive date, which determines how far back your past work can qualify for coverage. If you’re switching insurers, make sure they'll still cover earlier client projects.

    Then review the exclusions against the work you actually perform. If you create client content or rely on freelancers, check whether those activities are covered instead of assuming they are. Some insurers include protection for certain copyright or trademark claims, while others may restrict those risks.

  7. 7
    Reassess Coverage as Your Business Changes

    Your insurance should change when your business does, whether you’re growing or scaling down. A shift from strategy work into execution can increase your exposure, while winding down a service line could mean you need the same level of financial protection anymore. The goal is to keep your insurance matched to the business you’re actually running now.

Best Marketing Consultant Insurance: FAQ

Insurance for Marketing Consultants: Bottom Line

For most marketing consultants, I’d start with general liability and professional liability, then add coverage based on how you work. Hiring employees or leasing a space for an office can change what you need. The Hartford, ERGO NEXT and Hiscox are the top providers in my analysis, but the best fit depends on your business size, coverage priorities, budget and how you prefer to manage your policy.

Cost matters, but I wouldn’t choose on price alone. Compare insurers on the protection they offer now and whether they can still support you if your business expands or scales back. I’d also look at how easily you can adjust coverage as your client mix or services change.

Best Marketing Consultant Insurance Chart

Get Marketing Consultant Business Insurance Quotes

Your rates can change based on the kind of marketing work you do and the clients you take on. I’d compare quotes from several providers, since the cheapest option for a strategy consultant may not be the best fit for someone managing campaigns.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources