Best Business Insurance Companies For Management Consultants

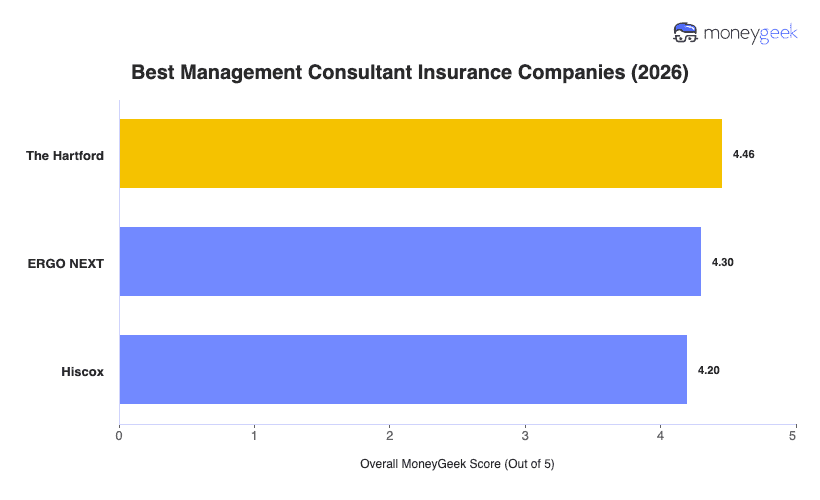
My analysis on the best business insurance companies for management consultants came down to these three:

  • Choose if you have layered coverage needs and want hands-on support: The Hartford
  • Choose if you regularly need customized COIs and want self-service policy management: ERGO NEXT
  • Choose if you have clients overseas and want extended agent support hours: Hiscox

Management consultants sell advice, so I put professional liability exposure at the center of the ranking. A recommendation about operations or business strategy could leave a client claiming financial loss even when no property gets damaged. I also accounted for contract requirements, since larger or more complex engagements may demand higher limits or additional coverage.

I used AI to support parts of the research, but I made the final editorial decisions on provider fit and ranking.

  • Affordability (50%): I priced each insurer against the same management consulting profile. Cost carries the most weight because paying more should get you something useful, such as stronger service or coverage that better fits your work.
  • Customer Experience (30%): Client requirements can change quickly from one engagement to the next. I looked at how easily you can get proof of insurance, update your policy and reach someone when a contract or claim needs more attention.
  • Coverage Options (20%): Management consulting risks don’t stop at professional liability. I gave more credit to insurers that can support additional business exposures and adapt as your contracts become more demanding.

See our full methodology.

The Hartford

The Hartford: Best for Layered Coverage Needs and Hands-On Support

On The Hartford's site
checkmarkpros
  • Lower rates for firms with 10+ employees

  • Hands-on claims support

  • Online COI access

  • Broad coverage for growing firms

closecons
  • Higher costs for smaller consulting firms

  • Agent involvement required to purchase

  • No small-business coverage in Alaska or Hawaii

COMPANY HIGHLIGHTS

The Hartford is my pick for management consultants who expect their insurance needs to get more complicated as the firm grows. At $39 per month on average, it has the lowest in my analysis, so you’re not paying a premium to get access to a broader setup. That matters if you’re hiring staff or taking on larger client contracts and need to add coverage without rebuilding your insurance program from scratch. I also like that The Hartford backs its coverage with consultant-specific risk management resources and specialist support. That extra guidance helps when a new client contract or larger engagement leads to questions you can’t solve with a self-service tool.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Customized COIs and Self-Service Policy Management

On ERGO NEXT's site
checkmarkpros
  • Fast online quote-to-COI process

  • Strong self-service policy management

  • Customized COIs through COI Analyzer

closecons
  • Stricter limits for recent E&O claims

  • PL unavailable above $5 million revenue

  • Less competitive for larger teams

COMPANY HIGHLIGHTS

I'd recommend ERGO NEXT for management consultants who need insurance to keep up with client onboarding. Get everything done online, from a quote to a COI, in about 10 minutes. That helps when a new project can't start until you can submit proof of insurance. The ERGO NEXT also has a COI Analyzer that's especially useful if clients send their own certificate requirements. You can upload a sample and generate a customized COI instead of reworking the request manually. Clients can also request certificate changes themselves, and you approve them before anything updates. That gives consultants with several active accounts a faster way to handle client requests without losing control of the process.

Learn More: ERGO NEXT Business Insurance Review

Hiscox

Hiscox: Best for Overseas Clients and Extended Agent Support Hours

checkmarkpros
  • Worldwide PL coverage for qualifying work

  • Extended weekday and weekend agent hours

  • Dedicated claims representative

closecons
  • Some policy changes require a phone call

  • Higher costs for solo and micro firms

  • Specialized services may need different underwriting

COMPANY HIGHLIGHTS

If your management consulting work regularly crosses borders, Hiscox could be the top choice for you. Its professional liability coverage follows work performed worldwide as long as the claim is filed in the U.S., a U.S. territory or Canada. That makes it useful for consultants advising multinational clients or taking on overseas engagements. Consultants whose client work spills past normal business hours will also find Hiscox a good fit. Licensed agents are available until 10 p.m. ET on weekdays and on weekends, so you can get help after a full day of client calls or when a contract issue comes up late.

Learn More: Hiscox Business Insurance Review

What Types of Insurance Do Management Consultants Need?

Professional liability often comes first because clients make business decisions based on your advice. If a client says your recommendation caused them to lose money, they could hold you responsible even when you delivered the work as promised. General liability, on the other hand, matters for more than slips and damaged property. If something in your report or presentation allegedly defames a client executive or another business, GL's personal and advertising injury addresses it. 
Take a closer look at how you do your business to figure out the other policies you need.

Protects against claims that your advice or services caused a client financial loss. Think a restructuring recommendation that the client says hurt revenue.
Once clients rely on your advice.
This is the core risk for management consultants. Aon reports that management consulting is driving more professional liability claims, with claim costs also rising.
Handles third-party injury, property damage and certain personal or advertising injury claims. For a consultant, that could mean damaging equipment while working at a client’s office.
Once you meet clients or work onsite.
If someone gets hurt at your office or you damage property during a client visit, GL can cover losses that PL does not.
Pays for certain costs tied to breaches, cyberattacks and compromised information. It can come into play if confidential client files or system access are exposed.
Once you handle sensitive data or systems.

Professional services recorded 478 data compromises in 2025, so even a consultancy without a large IT footprint can have considerable cyber exposure.

Helps pay employee medical costs and lost wages after a work-related injury or illness, whether it happens in the office or during business travel.
When you hire employees.

BLS recorded about 3,000 workplace injury and illness cases in management consulting services in 2024. Even in an office-heavy field, employees can still get hurt in a fall or develop a work-related strain.

Applies to business-owned vehicles and covered driving-related liability, such as a company car used for meetings or client-site visits.
Once the business owns a vehicle.

NHTSA estimates that six to seven million police-reported crashes occur each year. That highlights the level of risk you carry each time you sit behind the wheel.

Protects office furniture, computers and other business-owned property from covered losses such as theft or fire.
Once you have property worth protecting.
A laptop may be manageable to replace on your own. An office full of computers and monitors changes the math, especially as your team grows.

How Much Does Management Consultant Insurance Cost?

Depending on the coverage you get, you'll spend between $16 per month for commercial property and $121 for cyber insurance. Those, however, are estimates. Your actual premium will depend on the kind of advice you give and the kind of clients you service. Whether you get access to your client's data or systems could also affect your costs.

Per policy, expect to pay these average rates:

What Are These Costs Based On?

Our business insurance calculator gives you a quick estimate based on your profile. Costs may change with the type of advice you provide or the clients you serve, especially if your work involves sensitive data. When you’re ready to compare actual options, select “Get Quote” to see insurers that match your coverage needs and budget.

Management Consultant Insurance Cost Calculator
Select Coverage Type
Select State
Select Employee Cand
Select Vehicle Type
Average Monthly Cost—

How To Buy The Best Management Consultant Insurance

To get the best management consultant insurance, you'll work through your decisions in order instead of automatically going with the provider that's most familiar or the one that has the lowest rates. I've also created a companion buying worksheet you can save or print. Use this as you go through the steps I've mapped out below.

  1. 1

    Start With What You’re Required to Carry

    Pull out your active and upcoming client contracts before you request quotes. Note the policies and limits they require, then check whether the client also asks for proof of coverage. That could mean providing a certificate of insurance or adding the client as an additional insured. Then check the legal requirements tied to how your business operates. A company-owned vehicle means you need commercial auto coverage, while hiring employees can trigger workers’ comp rules in your state.

    Read More: Business Insurance Requirements

  2. 2

    Cover the Risks Your Requirements Leave Behind

    Pay attention to what your work exposes beyond the requirements you already found. If you handle sensitive client information or log in to client systems, cyber insurance can cover risks those required policies may miss. Commercial property starts to matter once replacing your work setup would be expensive, especially if you rely on multiple laptops or a dedicated office. The goal is to cover real gaps, not collect policies you don’t need.

  3. 3

    Set Limits Around the Loss You Could Realistically Face

    Use your client requirements as the floor, not the final answer. Start with the highest limit a contract asks for, then compare it with the size of a loss your work could realistically create. For professional liability, think about the decisions your advice influences. A $1 million contract requirement is typically enough for smaller engagements, but it can look very different if your recommendations shape a major restructuring or operating change. 

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Before You Request Quotes

    Once you know the coverage and limits you want, focus on how each insurer will support your business. If clients regularly ask for proof of insurance, check how quickly you can issue or customize COIs. If you prefer hands-on help, look at agent access and claims support instead of assuming every provider works the same way. I’d also compare how easily the insurer can handle more complex client requirements without forcing you to piece together coverage from multiple carriers.

  5. 5

    Compare Quotes on Equal Terms

    Use the same business details and coverage setup for every quote. Otherwise, a lower premium may simply reflect a smaller limit or a higher deductible rather than a better deal. Before you compare business insurance quotes, line up the terms that can materially change what you’re buying. For professional liability, pay close attention to the limit, deductible and retroactive date. If one insurer changes any of those, fix the mismatch before you compare price.

  6. 6

    Read the Policy Wording Before You Buy

    A quote can look fine until you get into the policy wording. Check the exclusions and any sublimits first, then look for terms that change how the coverage works in practice.

    For professional liability, confirm that the professional services definition matches the management consulting work you actually perform. Check the retroactive date so you know whether past work is covered, and read any hammer clause that could affect what you pay if you reject a settlement your insurer recommends. 

    For general liability, make sure personal and advertising injury remains included, since a defamation claim can come from a report or presentation. Then check how your cyber policy handles third-party liability. You’d want to know whether it covers you if your client holds your firm responsible for a breach involving data you accessed or stored during the engagement.

  7. 7

    Recheck Coverage When Your Business Changes

    Your insurance should change when the business does, whether you’re taking on more work or cutting back. Revisit your policies when you add or drop services, gain or lose employees, change how often you handle client data or stop using business-owned vehicles. Also review limits when your client mix changes. A larger engagement may push you toward more protection, while fewer projects or a smaller team could leave you paying for coverage you no longer need.

Management Consultant Insurance: FAQ

While we've covered most of the basics, there are other factors you need to consider when thinking about getting management consultant insurance.

Best Management Consultant Insurance: Bottom Line

The best management consultant insurance should reflect the consequences of the work you take on. I’d put professional liability at the center because a client could blame your advice for a financial loss. General liability handles risks outside the advice itself. As for the other policies, each one should earn its place based on how you operate, whether that means handling sensitive client data or employing a team.

Once you know what protection you need, it's easier to judge provider fit. The Hartford gives more support when the insurance setup gets complicated. ERGO NEXT suits a consultant who wants to manage things independently, and Hiscox has advantages for international work. Before even looking at price, check that your limits can handle a realistic loss and that each quote gives you the same amount of financial protection.

Best Management Consultant Insurance Chart

Get Management Consulting Insurance Quotes

Use the quote tool to see which insurers match your management consulting business. Compare the available options based on the coverage you need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources