Best Business Insurance Companies For IT Consultants

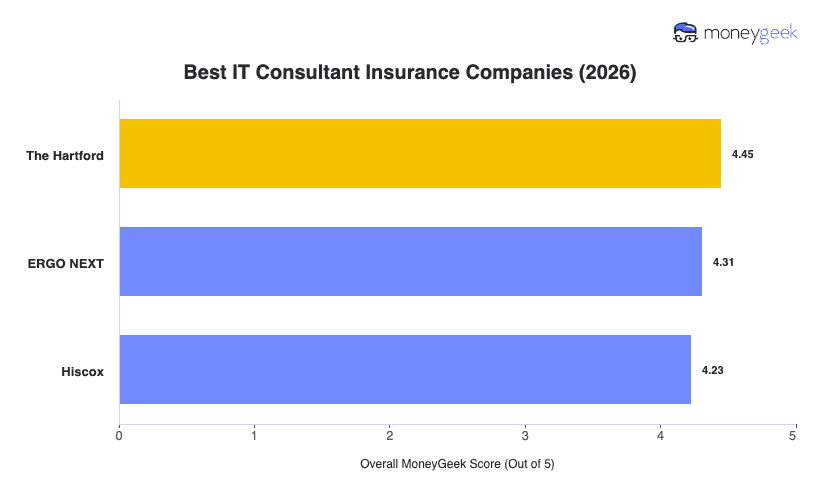
The three best business insurance companies for IT consultants in my analysis are:

  • Choose if you regularly work commercial contracts and have complex coverage needs: The Hartford
  • Choose if you want a fully digital buying experience and  frequently need COIs: ERGO NEXT
  • Choose if you customize software and want coverage for past work: Hiscox

I based the scoring on the risks IT consultants actually take on through client work. A technical mistake can create financial loss even when no physical damage occurs. Client contracts can also raise the bar for what your insurance needs to cover, so I weighed both risk and cost in the final rankings.

I used AI to support parts of the research, but I made the final editorial decisions on provider fit and ranking.

  • Affordability (50%): I compared every insurer using the same IT consultant profile. Cost carries the most weight because a higher premium should come with a meaningful advantage for your business, not simply more policies on the menu.
  • Customer Experience (30%): Insurance can become part of the client onboarding process. I looked at how easily you can provide proof of coverage and make policy changes when a contract calls for them. I also considered the support available once a claim becomes more complicated.
  • Coverage Options (20%): IT work can create professional and cyber-related liability at the same time. I gave more credit to insurers that can handle that overlap and continue supporting you as client requirements become more demanding.

See our full methodology.

The Hartford

Best for Commercial Contracts and Complex Coverage Needs

On The Hartford's site
checkmarkpros
  • Strong fit for implementation-heavy IT consulting

  • Tech E&O limits up to $10 million per claim

  • Technology-specialist underwriting and claims support

closecons
  • Expensive for solo IT consultants

  • Some coverage requires agent or phone support

  • Less suited to simple, low-touch insurance needs

COMPANY HIGHLIGHTS

The Hartford fits once your work moves past advice into implementation or more demanding client contracts. Its technology program scales to cover broader risks as your work grows more complex, so you’re not stitching policies together from separate insurers. FailSafe is the product that sets it apart. It brings technology E&O together with cyber liability, responding if a system you configured for a client fails and exposes sensitive data. The client could allege both a professional mistake and a cyber-related loss from the same incident.

The Hartford’s broader coverage doesn’t come with a higher price tag. Its rates run about 16% below the industry average, saving roughly $94 a year. For consultants serving larger clients, where insurance requirements tend to be stricter, this gets you broader coverage without the usual jump in cost.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT:

On ERGO NEXT's site
checkmarkpros
  • Affordable for solo IT consultants

  • Fast and free COIs

  • Fully digital policy management

closecons
  • Pricing gets weaker as teams grow

  • Less suited to complex contract-heavy claims

COMPANY HIGHLIGHTS

I'd recommend ERGO NEXT if you take on new clients regularly and insurance paperwork tends to show up right before work begins. Most of the process stays online, so you’re not waiting on an agent every time a client asks for proof of coverage. Its COI Analyzer is another interesting feature. Say an enterprise client sends over its preferred certificate before you can start an implementation project. Instead of rebuilding the COI yourself or emailing back and forth with an agent, you can upload the sample and review what ERGO NEXT generates. That takes a lot of friction out of onboarding when every client seems to want something slightly different.

Learn More: ERGO NEXT Business Insurance Review

Hiscox

Hiscox: Software Customization and Coverage for Past Work

checkmarkpros
  • Worldwide coverage for international client work

  • Lower rates for teams of 10 to 19

  • Extended agent availability, including weekends

closecons
  • Separate cyber coverage needed for sensitive client data

  • Limited protection for broader intellectual property disputes

COMPANY HIGHLIGHTS

If you’ve been consulting for a while and have plenty of past projects behind you, consider Hiscox. Its professional liability policy includes a retroactive date, which covers work completed before the policy started. Imagine a client discovers a configuration mistake from two years ago and files a claim today. If that work falls after your retroactive date, the policy may still respond.

Hiscox is also a good fit if you build or customize software. Its IT-focused errors and omissions (E&O) covers certain software copyright infringement claims. Picture this: you build or customize software for a new client using code or methods similar to work you created for a previous client, and that former client later claims you reused code they own and sues for software copyright infringement. Your policy helps with the legal costs and covered damages if the dispute turns into a lawsuit.

Learn More: Hiscox Business Insurance Review

What Types of Insurance Do IT Consultants Need?

Put errors and omissions (E&O) insurance in your bundle first since the most claims often start with the work itself. A client might blame your recommendation for a costly decision or say an implementation failed. If they claim your work caused financial loss, E&O helps pay for your legal defense and covered damages. Cyber liability comes next, since your work touches client systems or data. If a configuration error or compromised credential contributes to a breach, third-party cyber liability responds. 

When your IT work requires you to visit client locations or handle hands-on installation, get general liability. It helps if you accidentally damage a client’s server while setting up equipment. If a network rack you mounted comes loose after you finish the job and damages other equipment, completed-operations coverage in your GL policy helps with the resulting property damage.

Financial losses from mistakes in your advice or technical work, such as a failed implementation
As soon as clients rely on your technical work
A bad configuration can cost a client money even if nothing physical gets damaged. E&O is built for that kind of professional loss.
Costs from data breaches or network incidents involving systems you access
If you handle client systems or sensitive data

IT consultants can become part of a client’s cyber exposure simply by having access. Third parties were involved in 30% of breaches in Verizon’s 2025 DBIR.

Third-party injury or property damage tied to your business, including onsite work
For onsite projects or contract-required GL
Knock over a client’s server during installation or create a trip hazard with equipment, and E&O won’t step in for the physical damage or injury claim.
Tools & Equipment
Portable business gear away from your main location, such as laptops or network-testing equipment
Once costly equipment starts traveling with you

Replacement costs add up quickly. A current 14-inch MacBook Pro starts at $1,699, before you account for testing gear or other equipment you rely on for client work.

Liability and vehicle damage from covered business driving
For business-owned vehicles or uncovered work use

Client visits still put you on the road. In 2024, 11,769 car occupants died in crashes, and 75% were drivers.

Medical costs and lost wages after an employee is hurt or becomes ill because of work
After you hire, subject to state law

IT work is low-risk physically, but injuries still happen. Computer systems design and related services recorded about 5,800 nonfatal workplace injuries and illnesses in 2024.

How Much Does IT Consultant Insurance Cost?

How much you spend on IT consultant insurance depends on the policies you carry. Individually, average costs range from $17 per month for commercial property to $159 for cyber liability. Your actual rate can also change based on the services you provide and how much access you have to client systems or data. 

On average each policy costs:

What Are These Costs Based On?

Use our business insurance calculator to get a starting estimate for your IT consulting business. Your rate can shift depending on the kind of work you take on and how much access you have to client systems. Once you have a ballpark figure, select “Get Quote” to see which insurers line up with your budget and coverage needs.

IT Consultant Insurance Cost Calculator

Select your state and industry to view average business insurance premiums in your area. Rates are calculated based on a business with 5 employees and $500,000 in annual revenue.

Select Coverage Type
Select State
Select Employee Cand
Select Vehicle Type
Average Monthly Cost—

How To Buy The Best IT Consultant Insurance

There isn’t one universal insurance package for IT consultants, so you have to build yours around the work and client requirements. I've mapped out the process below so you know what to do. You can also download the companion checklist I've prepared and use it as you go through the steps.

  1. 1

    Start With What You Have to Carry

    Before you shop for coverage, figure out your insurance requirements. Your contracts are a good place to start. Some clients require E&O insurance or cyber liability before they'll let you touch their systems. Others ask for general liability and proof through a certificate of insurance (COI). If the agreement sets minimum limits or requires additional insured status, write those requirements down exactly as stated. Then check what the law adds. Hiring employees often triggers workers' comp. Owning a vehicle for the business brings commercial auto into play.

    Read More: Business Insurance Requirements

  2. 2

    Cover the Risks Your Requirements Leave Behind

    Think about what your required policies still miss. A stolen laptop or a piece of network-testing gear left behind at a client site can do more than cost you money to replace. It can also stop you from working until you get it back. That’s the gap tools and equipment coverage fills. Add it to your mix only when it answers a risk your actual work creates.

  3. 3

    Set Limits Around the Loss You Could Realistically Encounter

    Use client requirements as your floor, not your finish line. If a contract calls for $1 million in E&O, start there, then ask what one serious mistake could cost. A consultant migrating a large client's core systems, for example, likely needs more financial protection, since a failed rollout could interrupt operations across the business. Your limit should reflect the size of the loss you could create, not just the minimum written into the contract.

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Before You Request Quotes

    Check whether the insurer fits how you want to buy and manage coverage. If your clients regularly ask for COIs, look at how quickly an insurer can issue or update them. If you'd rather handle everything yourself, see what you can do online and where an agent still has to step in.

    Then look past convenience. Pay close attention to whether the insurer understands technology claims and offers policy features that match your work. A provider with strong Tech E&O or cyber expertise fits better if you handle implementations or client systems. A simpler self-service carrier works fine for straightforward advisory work.

  5. 5

    Compare Quotes on Equal Terms

    Make sure each policy uses the same limits and deductibles when you compare business insurance quotes. A lower premium doesn't tell you much if one policy gives you less financial protection. Keep the business details consistent too, especially how you describe your IT services. Once the terms line up, it's easier to judge whether the price difference reflects real value or just thinner coverage.

  6. 6

    Read the Policy Before You Buy

    A quote can look good until the wording changes what you thought you were getting. For professional liability, start with the retroactive date. It tells you how far back the policy can reach for work completed before the current policy started. That matters when a client discovers a mistake months or years later. Also look for a hammer clause. If the insurer wants to settle and you refuse, that clause can shift some of the additional costs back to you.

    Cyber policies need the same scrutiny. Check that your policy includes third-party liability, since that responds if your work contributes to a client breach. Then review exclusions around dependent systems or widespread cyber events. Those limits matter if the incident starts with a vendor or affects many businesses at once.

  7. 7

    Recheck Coverage When Your Business Changes

    Don't wait for renewal before you revisit your insurance. Review your policies when your work changes, whether that involves hiring your first employee or no longer offering implementation services. Even if the change is small, it could still affect your coverage needs. If you lose access to client systems you once managed, for example, you might not need as much cyber coverage as before. That could mean lowering your limits. Your coverage should reflect the business you run now, not the version you insured a year ago.

IT Consultant Insurance: FAQ

Best IT Consultant Business Insurance: Bottom Line

Start with the work you do, then build your insurance around it. Professional liability often anchors the bundle for IT consultants, while cyber becomes more important once you access client systems or data. Your contracts and day-to-day operations will tell you what else to add.

Once you know your coverage mix, choosing the best IT consultant insurer comes down to how complex your work is and how you prefer to manage coverage. The Hartford fits broader technology risks. ERGO NEXT works well if you want more self-service, while Hiscox is a better match when IT-specific E&O features matter more.

Before you buy, make sure your limits satisfy client requirements and still reflect the size of loss you could realistically cause. Then compare quotes on equal terms so you can tell whether a lower premium gives you real value or simply less protection.

Best IT Consultant Insurance Chart

Get IT Consulting Insurance Quotes

If you’re ready to shop, use the quote tool to see which options fit your IT consulting business. You can compare available insurers based on the coverage you’re looking for.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources