


Jump to the section that meets your needs best below:
Average Dog Walker Insurance Cost (2026 Report)
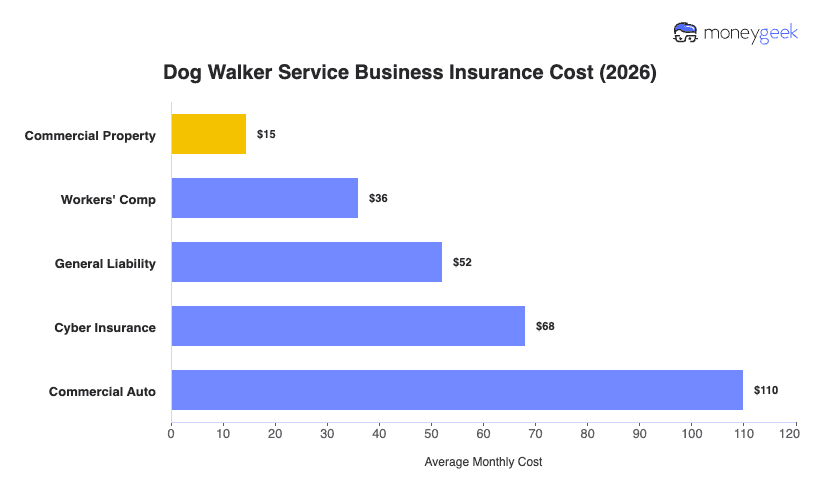
Dog walker insurance costs range from $15 to $110 per month, depending on your services, how many dogs you walk and whether you drive between clients.
If you're ready to get a quote, MoneyGeek can connect you to the best dog walker insurance provider for your operations with our matching tool below.
Select state
Safe & SecureVerified and VettedTrusted Brands
Updated: September 10, 2026
Advertising & Editorial Disclosure
How Much Does Dog Walker Business Insurance Cost?
Pet care services business insurance costs for dog walkers average around $56 per month, or about $673 per year, across the five most common coverage types. That figure is based on estimates for businesses with one to four employees across all 50 states and Washington, D.C., using standard limits of $1 million per occurrence and $2 million aggregate.
What you pay for any single coverage type will likely fall between $15 and $110 per month. Commercial property is the most affordable because your work is mobile, so most of your exposure happens out on the street with a dog on a leash, not inside a building you own or lease. You pay the most for commercial auto since driving between client homes every day is commercial use, and insurers price that daily road exposure accordingly.
The table below breaks out costs by coverage type, but treat the figures as benchmarks, not quotes, since your actual premium depends on your specific business profile.
| Commercial Property | $15 | $174 | 88% | 27 |
| Workers' Comp | $36 | $432 | 68% | 128 |
| General Liability | $52 | $626 | -58% | 113 |
| Cyber Insurance | $68 | $817 | 18% | 161 |
| Commercial Auto | $110 | $1,318 | 33% | 112 |
We analyzed quote data from major U.S. commercial insurance providers and modeled standardized premium estimates across business profiles representing around 95% of the market. Results are designed to provide a consistent national benchmark showing how premiums vary by key baseline factors including business size, restaurant profession type, location and vehicle type for operations that use commercial vehicles.
Dataset Scope and Assumptions
Our cost modeling uses standardized inputs for consistent comparisons across businesses.
- Total estimates modeled: just over 6 million standardized pricing estimates
- Providers analyzed: 10 major insurance providers
- Geography: all U.S. states including Washington, D.C.
- Employee count bands: solo practitioners, one to four, five to nine, 10 to 19, and 20 to 49 employees
- Vehicle types studied: Sedans, SUVs, pickup trucks, vans, taxis, limousines, tractors, food trucks, semi-trucks (non-HAZMAT and HAZMAT), tanker trucks (non-HAZMAT and HAZMAT), buses, box trucks, dump trucks, flatbed trucks
- Policies studied: general liability, workers' comp, professional liability, commercial auto, commercial property, and cyber insurance
- General liability: $1 million per occurrence and $2 million aggregate
- Workers' comp: state required coverage
- Professional liability: $1 million per claim and $1 million aggregate
- Commercial auto: minimum coverage
- Commercial property: personal property coverage limits personalized to industry, business size and state
- Cyber insurance: $1 million per occurrence and $1 million aggregate
How We Calculated Average Dog Walker Service Business Insurance Costs
Our published averages represent modeled premiums for standardized business profiles and were aggregated in two ways.
- National benchmark average: The national average cost reflects the modeled premium for a standardized one to four employee business across all and states included in our dataset for a standard policies
- Segment averages: To show how costs vary, we calculated average modeled premiums for our national base profile and isolated for variables, including:
- Employee count (business size ranges)
- Vehicle types (for commercial auto)
- States (including Washington, D.C.)
Segment averages were produced by aggregating modeled pricing trends across the full dataset so readers can compare how premiums shift across coverage types and regions.
See our full business insurance methodology.
Get Dog Walker Business Insurance Cost Estimates
If you want a more personalized estimate, use our business insurance cost calculator before comparing rates.
Get Dog Walker Insurance Cost Estimates
Select Coverage Type
Select State
Select Employee Count
Select Vehicle Type
Monthly Rate Estimate—
Select Coverage Type
Monthly Rate Estimate—
Select State
Select Employee Count
Select Vehicle Type
Factors Affecting Dog Walker Business Insurance Costs
Several factors shape what you'll pay for dog walking business insurance, and in our analysis, the biggest price differences come from operational decisions specific to this industry, not just how long you've been in business or your claims history.
 Vehicle use
If you drive between client homes every day, that routine travel is commercial use and it prices higher than personal auto coverage because insurers rate on daily, predictable road exposure. Your premium reflects how frequently your vehicle is in use for business, not just whether you own one. A walker who drives five routes a day faces a different underwriting profile than one who works within walking distance of their clients.
 Animal handling and behavior risk
According to the Insurance Information Institute, U.S. insurers paid $1.86 billion in dog-related injury claims in 2025, a nearly 19% increase from the year before. Because your work puts you in direct physical control of a client's animal in public spaces, that national claim trend directly affects what you'll pay for liability coverage. The more dogs you handle and the more public your routes, the more that exposure compounds.
 Services offered
Your risk profile as a walking-only business looks very different from one that also boards dogs overnight or offers training-adjacent services. Each additional service introduces exposures that a walking-only policy may not fully address, and insurers adjust pricing to reflect the broader scope of what your business actually does. If you've recently added pet sitting or in-home boarding, your current policy may not reflect your actual risk.
 Dog breed and animal profile
High-value animals in your care raise your financial exposure on any given walk. A client's $4,000 French Bulldog carries a very different claim risk than a mixed-breed rescue. If that dog is injured or lost during a walk, the claim value reflects the animal's worth, and insurers weigh the type and value of animals you typically handle when assessing your liability exposure.
 Pack size
Walking one dog at a time carries less handling risk than managing a group of three or four on a single route. When your typical walk involves multiple dogs from different households, the complexity of controlling each animal increases, and so does the likelihood of an incident. This leads some underwriters to treat group walks as a higher-risk service category than solo walks, even when the route and duration are identical.
How to Lower Dog Walker Business Insurance Costs
The same operational decisions that drive your premium up can often be adjusted to bring it down. Some of these methods take effect within your current or next policy period, while reducing your overall risk profile takes longer but produces more lasting results. Finding affordable business insurance starts with knowing which levers actually apply to how your business runs.
 Compare quotes using the same coverage limits
Getting the lowest quote means less if it's priced on thinner coverage than your other options. Dog-walker-specific general liability that includes care, custody and control coverage prices differently across pet-care specialists versus generalist small business insurers. Compare business insurance quotes on identical limits is the only way to see what you're actually paying for the same protection.
 Right-Size Your Coverage
If you're a solo walker with no employees, no boarding services and a single vehicle, your coverage scope should reflect that, not the profile of a multi-walker operation. Paying for endorsements or limits built for a larger or more complex business adds cost without adding protection relevant to your situation. Review your policy against your actual services before each renewal.
 Bundle policies with the same provider
Pet-care-specific insurers often package commercial auto, general liability and tools coverage together at a lower combined rate than buying each separately. Because the specialized insurer market for dog walkers is more concentrated than in many other trades, bundling with one provider tends to produce more meaningful savings here than it would elsewhere.
 Pay annually instead of monthly
Most insurers charge an installment fee when you pay month to month, which adds to your total annual cost without changing your coverage. If your cash flow allows it, paying your full premium upfront is one of the simplest ways to reduce what you pay each year.
 Invest in risk management practices
Dog bite and animal-handling claims are the most common and costly claims your business faces, and your claims history over multiple policy periods is one of the strongest signals underwriters use when setting your rate. Documented safety practices build that record over time and can meaningfully lower your renewal pricing.
- Use a client intake process that screens for behavioral history and vaccination records before taking on a new dog
- Keep written leash and handling protocols for group walks, particularly for reactive or large-breed dogs
- Document every incident involving a dog in your care, even minor ones, with date, location and outcome
- Require signed service agreements from clients that outline your policies for emergencies, injuries and lost animals
Dog Walker Business Insurance Cost: Bottom Line
$56 per month is a useful starting point for understanding what dog walking business insurance costs, but it's not a quote tailored to your operation. Your actual rate reflects a narrower set of variables like the services you offer, how you use your vehicle and the animals you typically handle.
Three questions help you put any quote you receive in context:
- Where do you fall in the distribution? Your walking-only operation will sit at a different point in the cost range than a multi-service business that also boards or does drop-in visits. Start by locating your profile against the benchmarks on this page by coverage type and state.
- Is your quote consistent with your risk profile? A quote that sits well above the benchmarks for a solo walker in a low-cost state warrants a closer look before you accept it. Understanding which part of your profile is driving the difference helps you evaluate whether the price reflects your actual exposure. Usually, your vehicle use pattern and service scope are the two most common sources for a gap.
- 3. Which cost drivers apply to your business? Not every factor on this page carries the same weight for your business. Daily vehicle use matters more to someone driving across a metro area than to a walker who covers a single neighborhood on foot. Identify which drivers actually apply to your operation before drawing conclusions from the averages.
Understanding which factors affect your costs the most and why they move the number is more useful than knowing whether your quote sits above or below average. Use the figures on this page as orientation, not as a target.
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com
Sources
- Insurance Information Institute. "Dog-Related Injury Claims on the Rise in 2025." Accessed October 19, 2026.