Cheapest Illinois General Liability Insurance Companies

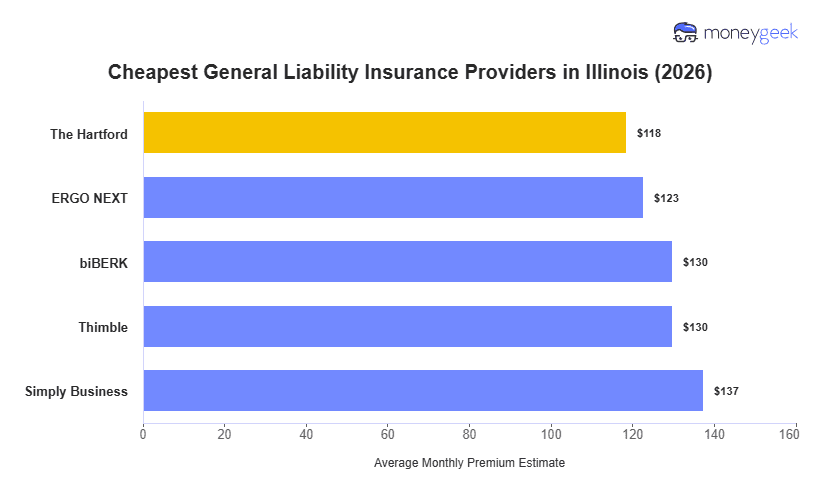
I analyzed quotes across 25 general industries to determine which carriers have lowest general liability rates across different business types in Illinois. Four providers consistently topped my list:

  • The Hartford: Best for professional services and creative businesses (photography, financial advisors, accountants, chiropractors)
  • ERGO NEXT: Best for hands-on trades and food service operations (electrical contractors, plumbing, food trucks, catering)
  • biBERK: Best for fitness facilities and cleaning services (gyms, personal training, janitorial services, carpet cleaning)
  • Simply Business: Best for retail shops and food service establishments (bookstores, gift shops, bakeries, delis)

The cost of your general liability policy depends on your industry, business size, revenue and location within Illinois. Use these providers as a starting point, then compare quotes based on your business details.

The Hartford$118$1,42216%
ERGO NEXT$123$1,47213%
biBERK$130$1,5578%
Thimble$130$1,5598%
Simply Business$137$1,6473%
Coverdash$145$1,740-3%
Progressive Commercial$150$1,795-6%
Hiscox$157$1,883-11%
Nationwide$159$1,908-13%
Chubb$160$1,919-14%

We identified Illinois’ cheapest general liability insurers by comparing average rates for businesses with one to four employees across industries. Industry recommendations use that same employee range to keep business size consistent, while employee-size comparisons combine pricing across industries to show how rates change as companies grow.

The analysis draws on more than 20,000 standardized estimates from 10 major insurers, covering 408 business types across 25 industries and businesses with zero to 49 employees. Estimates assume $1 million per occurrence/$2 million aggregate coverage and incorporate modeled revenue and payroll.

These figures are benchmarks, not personalized quotes. Actual premiums in Illinois can vary based on business classification, claims history, revenue or payroll, coverage limits, deductibles and endorsements. Compare quotes using equivalent coverage terms.

Read our full methodology.

The Hartford

The Hartford: Cheapest for Professional and Creative Businesses

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford offers the cheapest rates across the widest range of Illinois businesses, ranking lowest in 112 of 408 industries, 27% of all business types. It provides the biggest savings for professional services and creative businesses like photography studios, financial advisors, accountants and chiropractors. Most small businesses pay an average of $118 monthly, 16% below the Illinois average, saving $268 a year compared to typical rates.

Most often cheapest for these business profiles:

  • General industries: Arts, Media and Entertainment, Education, Financial Services, Health Care and Medical, Retail and Product Rental, Tech/IT, Wholesale and Distribution
  • Employee count: Zero to 49 employees

Not a fit? Jump to: NEXT or biBerk or Simply Business

ERGO NEXT

ERGO NEXT: Cheapest for Trades and Food Service

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT offers the lowest rates for hands-on trades and food service operations like electrical contractors, plumbing businesses, food trucks and catering companies. It's the most affordable provider for 126 (31%) out of 408 business types. Businesses with one to four employees spend an average of $123 monthly, 13% below typical Illinois rates, for annual savings of $219.

Most often cheapest for these business profiles:

  • General industries: Beauty, Body and Wellness Services, Construction and Contracting, Consulting Services, Food and Beverage, Hospitality, Travel and Tourism, Manufacturing, Marketing and Communications, Repair and Maintenance, Transportation and Logistics

Not a fit? Jump to: The Hartford or biBerk or Simply Business

biBerk

biBERK: Cheapest for Fitness and Cleaning Businesses

COMPANY HIGHLIGHTS

Small Illinois businesses in fitness and cleaning sectors, like gyms, personal training studios, janitorial companies and carpet cleaning operations, pay $130 monthly with biBERK, saving $133 annually compared to typical state rates. It ranks cheapest in 25% of all business types we analyzed in Illinois (103 out of 408), with low rates for businesses providing personal services.

Most often cheapest for these business profiles:

  • General industries: Cleaning Services, Fitness Services, Other Professional Services, Pet Care Services, Real Estate and Property Services, Recreation and Sports

Not a fit? Jump to: The Hartford or ERGO NEXT or Simply Business

Simply Business

Simply Business: Cheapest for Retail and Food Establishments

COMPANY HIGHLIGHTS

With monthly premiums averaging $137 ($1,647 annually) for Illinois businesses with 1 to 4 employees, Simply Business's premium falls 4% below typical state rates. Although this provider is the cheapest for only one general industry (childcare services), it offers other business types with savings of over 40% compared to Illinois' average cost. These include retail shops and food-service establishments such as bakeries and delis.

Most often cheapest for these business profiles:

  • General industry: Childcare Services

Not a fit? Jump to: The Hartford or ERGO NEXT or biBERK

Is the Cheapest General Liability Insurance Right for Your Illinois Business?

Low premiums make sense for businesses with simple operations and minimal client requirements. But cutting costs too much can backfire if your policy doesn't cover what you need when problems arise.

Don't pick a policy on price alone. Think through these considerations first:

  • Contract requirements: Property managers in Evanston and general contractors in Springfield often require specific coverage amounts before you can start work, so buying minimum limits now might mean upgrading later at a higher cost
  • Your claims cushion: If a customer slips on ice outside your Naperville shop or alleges damage during a job in Joliet, can you cover a $2,500 deductible without disrupting cash flow?
  • Room to grow: A small Peoria consulting firm and a mid-sized Aurora warehouse need different protection levels, and your insurer should offer the endorsements your industry requires as you scale
  • Claims-handling speed: Fast processing matters more than a low premium when you're dealing with property damage after a storm or an injury at your location

Find the best general liability insurer for your business by matching your policy to what clients and landlords require now. Then, you can raise limits as your operations expand across Illinois markets.

How to Get Cheaper General Liability Insurance in Illinois

Lowering your general liability costs in Illinois without sacrificing coverage means focusing on accurate pricing and demonstrating lower risk to insurers, not just accepting the first quote you receive or cutting limits to save money.

  • swipe icon

    Compare general liability quotes using the same limits

    If you request a quote with $1 million limits from one insurer and $2 million from another, you can't tell which company actually offers better rates for your business. A Wicker Park coffee shop comparing business insurance quotes from three insurers should ask each for the same liability limits, same deductible and same policy period. Otherwise, you're comparing a basic sedan price to a luxury SUV and wondering why the numbers don't match.

  • loanReview icon

    Ensure your business classification (class code) is correct

    Insurers assign premiums based on your industry classification code. An Oak Park bookkeeper doing basic accounts payable and receivable work for small clients pays far less than a CPA firm preparing audited financial statements and tax returns. If your insurer codes you as the latter, you'll overpay by 40% to 60%. Confirm the classification on your quote matches the actual services you provide, especially for professional services common across Chicagoland.

  • signupBonus icon

    Only pay for general liability coverage limits you actually need

    If you're bidding on corporate office cleaning contracts in Oak Brook or leasing retail space in Naperville, landlords and clients' general liability requirements typically require proof of $1 million per occurrence before you can start. Buying $2 million limits when nobody asks for it wastes money, but showing up with only $500,000 can disqualify you from jobs before price negotiations even start.

    Read More: How Much General Liability Insurance Do I Need?

  • money2 icon

    Use general liability deductibles and payments strategically

    A Peoria accounting firm working from a quiet office building can likely handle a $2,500 deductible because slip-and-fall claims rarely happen in low-traffic professional spaces. But if you run a Naperville restaurant where customers walk in daily during icy Illinois winters, a $2,500 out-of-pocket cost after someone falls in your parking lot could strain cash flow during your slowest season. Higher deductibles work when your business setup and customer interactions create lower claim frequency.

  • bag icon

    Bundle general liability insurance when it lowers your total cost

    Compare BOP costs against standalone general liability pricing before deciding. A business owner's policy (BOP) package bundles general liability with property coverage and for retail shops, restaurants or small offices in leased Illinois spaces, bundling often costs 15% to 25% less than buying each policy separately. If you run a home-based consulting practice in Schaumburg with minimal equipment and no physical location to insure, buying standalone general liability makes more sense than paying for property coverage you don't need just to access the bundle discount.

  • takingNotes icon

    Lower your claim risk in ways Illinois insurers reward

    Insurers reduce premiums for businesses that demonstrate active risk management. What counts varies by industry, but these practices signal lower liability exposure across Illinois operations:

    • Written safety protocols for winter weather (salting schedules, entrance mat placement, ice melt procedures for November through March)
    • Employee training documentation for high-risk periods (crowd management during Chicago summer festivals, customer interaction during peak retail seasons, safe food handling for Illinois restaurants)
    • Regular facility maintenance logs that address regional challenges (HVAC inspections before humid summers, plumbing checks before freezing temperatures, flat roof drainage for spring storms)
    • Customer contract templates with liability waivers appropriate for Illinois law and clear scope-of-work boundaries for service calls across collar counties
    • Certificate of insurance tracking for subcontractors or vendors, especially if you work with Chicago union contractors or Metro East suppliers who service your location

    You don't need expensive consulting. Consistent documentation shows insurers you're managing the risks they price into your premium.

Affordable General Liability Insurance in Illinois: Bottom Line

No single carrier consistently offers the lowest rates across all Illinois businesses. A Naperville consulting firm and a Joliet manufacturing facility get quoted differently by the same insurer because they assess industry risk, location and customer interaction patterns in distinct ways.

The industry guides above show which carriers price your business type competitively, but affordable means more than the smallest premium. The lowest quote only makes sense when it covers what Schaumburg landlords require for your lease or protects you adequately when a customer files a claim at your location.

Cheapest General Liability Insurance in Illinois Chart
shoppingCart icon

LOOKING FOR CHEAP COVERAGE FOR OTHER POLICY TYPES?

General liability won't be the only coverage in your insurance mix if you want extensive financial protection. The more coverages you have, though, the higher your total costs become. See which providers have affordable premiums for other policies to keep your insurance expenses manageable.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com