Top Picks: Best Commercial Auto Insurance Companies in California

MoneyGeek evaluated California's best commercial auto insurance providers by comparing rates across eight vehicle types and 25 industries, then measuring the coverage breadth and policy flexibility each one delivers. Every carrier was also scored on customer experience across the quote process, policy management and claims handling. The five providers below stood out.

  1. Progressive Commercial: Best Overall, Best for Fleet Operations
  2. GEICO: Best for Low-Risk Business Areas
  3. The Hartford: Best for Coverage Depth
  4. Nationwide: Best for Agricultural and Specialty Fleets
  5. biBerk: Best for Simple Coverage Needs

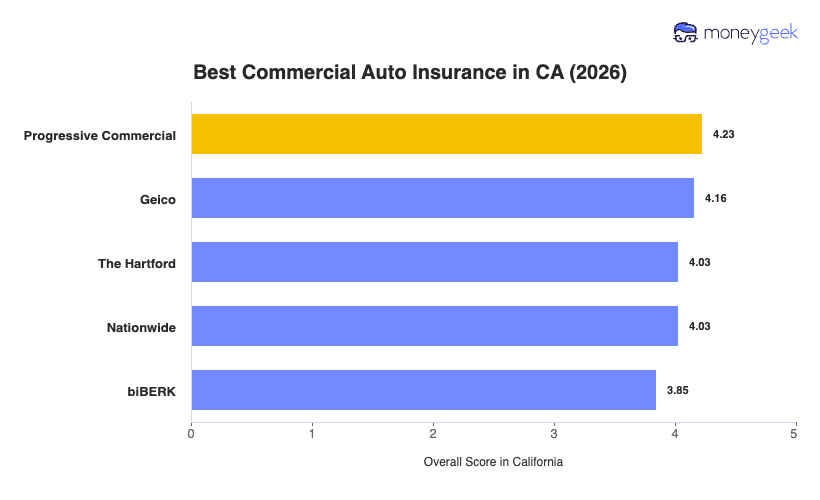
Here is how all five providers compare across score and rank.

Progressive Commercial4.23214
Geico4.16123
The Hartford4.03521
Nationwide4.03352
biBERK3.85445

The summaries below break down exactly who each provider fits best and who should look elsewhere, since an overall ranking means little if a provider does not match your specific vehicle type, industry or operational need.

Progressive

Progressive

Best Overall, Best for Fleet Operations

Progressive Commercial is the strongest all-around option for businesses that want competitive pricing on high-exposure vehicles paired with the best buying and claims experience in California. It holds the No. 1 customer experience rank among all five providers and prices 11% below the state average overall, with the widest gap on taxi and limousine fleets at 31% below. The fully digital quote process supports same-day coverage for most California business types, and fleet operators can add vehicles mid-term without picking up the phone. Progressive does rank fourth on coverage depth (4.04 out of 5), so California businesses that need broader endorsement options beyond the state's 30/60/15 minimums, particularly those in medical transport or specialized freight, may find the policy terms too narrow.

Learn More: Progressive Business Insurance Review

GEICO

GEICO

Best for Low-Risk Business Areas

GEICO is the best fit for businesses that want the lowest rates in California on light vehicles and office-based industries. It carries the No. 1 affordability rank among all five providers, pricing 15% below the state average overall. The savings are steepest in financial services and consulting (23% to 25% below), with tech/IT and agriculture close behind at 23% below. The fully self-service quote process works well for smaller California operations that do not need agent guidance, and the Auto Repair Xpress program connects policyholders with preferred shops that guarantee their work. GEICO ranks third on coverage (4.12 out of 5), and California law bars using telematics data to set rates, so its DriveEasy Pro fleet tools will not translate into premium savings here.

The Hartford

The Hartford

Best for Coverage Depth
On The Hartford's site

The Hartford is the best fit for businesses that want the broadest policy terms and endorsement options available in California. It ranks first on coverage among all five providers with a score of 4.26 out of 5, and it is the only carrier in the analysis that packages Broad Form, HNOA and Motor Truck Cargo without requiring a specialty-market referral. For California businesses in hospitality, arts and professional services that need flexibility above the state's 30/60/15 minimums, The Hartford is the clearest fit. It ranks last on affordability (fifth of five), pricing 25% above the California average overall, and purchasing requires working with an agent rather than completing a quote online.

Learn More: The Hartford Business Insurance Review

Nationwide

Nationwide

Best for Agricultural and Specialty Fleets

Nationwide is the best fit for businesses that want competitive rates on limousines, vans and food trucks along with strong coverage terms for agricultural and specialty fleet operations in California. It ranks second on coverage depth (4.13 out of 5), sitting between The Hartford and the rest of the field, and prices 5% below the state average overall. Its strongest edge is on limousines, where it ranks second among California providers. Hospitality, cleaning services and transportation and logistics businesses also get solid value, with Nationwide pricing below the state average in each of those industries. Nationwide ranks last (fifth of five) on customer experience, with commercial policyholders reporting slower adjuster communication and less consistent follow-through on complex claims.

Learn More: Nationwide Commercial Auto Insurance Review

biBerk

biBerk

Best for Simple Coverage Needs

biBerk is the best fit for businesses that want a straightforward, fully online purchase for basic commercial auto coverage in California. Its digital quote process takes most applicants from quote to bound policy with no agent involvement, which suits sole operators and very small businesses that know exactly what they need. It prices below the California average for low-mileage professional service businesses in fitness, beauty, wellness and consulting. biBerk ranks fifth overall (3.85 out of 5) and last on coverage depth (3.57 out of 5), with fewer endorsement options and less policy flexibility than any other provider in the analysis. It also prices 6% above the state average across most vehicle types and industries.

Learn More: biBerk Business Insurance Review

What Determines the Best Commercial Auto Insurance in California for You

No single provider is the right fit for every California business. The right choice depends on how well a provider's pricing, policy terms and claims support line up with your specific vehicles, industry and the risks tied to commercial auto insurance in California. Three areas matter most.

  • money2 icon

    Affordability Across Your Vehicle Type and Industry

    Rate gaps between providers in California run wider than most business owners expect, in both directions. As much as 68% separates the most and least competitive providers for taxi and limousine operators in MoneyGeek's analysis, and pickup trucks and farm tractors show gaps of 59% to 61%. On the industry side, wholesale and distribution, transportation and logistics, and construction and contracting businesses see differences of 50% to 60% between providers. A California hospitality or manufacturing business that picks a provider without comparing rates by industry could pay 20% to 30% more than necessary. Compare quotes against the cheapest commercial auto providers in CA using your actual vehicle types and industry classification, not just the statewide average rate.

  • insurance2 icon

    Coverage That Matches Your Fleet's Risks

    California requires minimum commercial auto liability coverage of $30,000 per person, $60,000 per accident and $15,000 for property damage. Those minimums rise quickly based on how your business operates. A Motor Carrier Permit from the California DMV becomes required for any vehicle over 10,001 lbs GVWR (gross vehicle weight rating), and your insurer must file Form MC-65 directly with the DMV before that permit becomes active. Liability requirements from $300,000 to $5,000,000 combined single limit apply to intrastate for-hire carriers, depending on vehicle weight and cargo type. Passenger transport businesses operating intrastate need a separate CPUC permit rather than an MCP, which triggers its own insurance filing requirements. Confirm the full commercial auto insurance requirements in California that apply to your operation before you buy.

    • Liability limits available: California's 30/60/15 minimums are a starting point, not a recommendation. Transportation, construction and passenger transport businesses especially should confirm that available liability ceilings match their actual exposure, given California's high nuclear verdict environment.
    • Breadth of vehicles covered: Not every California vehicle type is written by every provider. Confirm coverage eligibility for farm tractors, food trucks, limousines and specialty vehicles before binding, and check whether your fleet mix affects your rate classification.
    • Standard vs. endorsement coverage: Some providers include roadside assistance, rental reimbursement and hired and non-owned auto as standard, and others charge extra for them. The Hartford packages named endorsements like Broad Form and HNOA that other providers price separately.
    • Hired and non-owned auto coverage: This matters for California professional services, healthcare and real estate businesses where staff drive personal vehicles on company time, since it is not automatic on all base policies.
    • Cargo and equipment coverage: California transportation, wholesale and distribution, and Central Valley agriculture businesses should verify whether tools and cargo are included or require a separate inland marine policy.
    • Exclusions and policy language: California is a tort state with no PIP requirement, so injury claims go through the at-fault driver's liability coverage instead. Also confirm whether your policy covers operations near the California-Mexico border, since standard California policies exclude incidents in Mexico.
    • Deductible flexibility: Diminishing deductibles and total loss waivers affect out-of-pocket costs at claim time more than most businesses anticipate, and these vary by carrier.
    • Coverage for fleet growth: Some policies allow mid-term vehicle additions without a rewrite. Others require a full rewrite, which can create temporary coverage gaps for California businesses that add vehicles frequently.
  • talk icon

    Customer Experience and Claims Support

    California's litigation environment produces more contested commercial auto claims than most states, which makes adjuster quality and response time more consequential here than in lower-risk markets. Check whether claims are available 24/7 or only during business hours, whether commercial claims get a dedicated adjuster or go through a general call center, and whether your account keeps a consistent agent who knows your industry over time. A provider that handles personal auto claims well does not automatically translate that to commercial fleet claims, so look for data specific to commercial lines. NAIC complaint ratios offer an independent benchmark to compare alongside customer reviews.

How to Choose the Best Commercial Auto Insurance in CA

Getting commercial auto insurance right in California takes more than finding a competitive rate. Work through these steps before requesting quotes so the coverage you buy matches how your business operates.

  1. 1
    Define Your Risk Profile

    Start with a full inventory of every vehicle the business uses, including owned, leased and employee-owned vehicles driven for work. Record each vehicle's primary use, annual mileage and the driving history of all operators. Load type and operating radius deserve extra attention from California businesses in construction, transportation and logistics, hospitality and agriculture, since both directly affect how carriers classify and price the fleet.

  2. 2
    Determine Your Coverage Requirements

    With the inventory complete, identify which coverage types the operation actually requires beyond California's baseline 30/60/15 liability minimums. California is a tort state with no PIP requirement, so injury claims go through the at-fault driver's liability coverage rather than a no-fault system. Cargo coverage needs explicit confirmation for transportation, wholesale and distribution, and agriculture businesses moving goods. Collision and comprehensive is required for financed or leased vehicles. Hired and non-owned auto matters where staff drive personal vehicles for work. The Motor Carrier Permit requirement triggers on any vehicle over 10,001 lbs GVWR, with liability minimums from $300,000 to $5,000,000, and passenger transport operators running limousines, shuttles or charter vehicles intrastate need a CPUC permit with its own filing requirements.

  3. 3
    Research Providers by Industry and Vehicle Type

    Not all carriers price California commercial auto risk the same way. Progressive Commercial ranks first on high-exposure operations, including taxis, limousines, food trucks and most trade and logistics industries. GEICO offers the most competitive rates for low-exposure professional service businesses in tech, consulting, financial services and fitness. Identify which carriers have a track record in your specific industry and vehicle category before comparing on price.

  4. 4
    Evaluate Coverage Quality and Policy Terms

    Premiums tell you a policy's cost. Policy terms tell you what it actually covers. For each provider on your shortlist, check which coverages are standard versus endorsement-only, what liability limits are available above California's 30/60/15 minimums and what exclusions could void a claim. Confirm how the policy handles mid-term fleet additions, since some California carriers require a full rewrite to add vehicles, which can create a temporary coverage gap.

  5. 5
    Get Quotes to Confirm

    Only after narrowing options through research should you request quotes. A quote validates whether a provider's pricing holds for your specific fleet, location and coverage requirements, so it works as a confirmation step rather than the starting point. California pricing can separate providers by as much as 68% on high-exposure vehicle types like taxis and limousines, and by 50% to 60% across industries like wholesale and distribution and transportation and logistics, so a comparison of quotes taken without that context invites overpaying or underinsuring.

  6. 6
    Confirm California Filing Requirements

    Confirm whether the operation triggers any state-specific filing requirements beyond a standard commercial auto policy before purchasing. A Motor Carrier Permit from the DMV becomes necessary for California businesses operating vehicles over 10,001 lbs GVWR, and the insurer must file Form MC-65 as proof of coverage. A USDOT number and federal FMCSA filings are also required for interstate carriers. Passenger transport operators handling taxis, limousines, shuttles or charter services intrastate need a CPUC permit and must file proof of insurance directly with the Commission before operating.

Best Commercial Auto Insurance in California: Bottom Line

Three questions cut through most of the noise when choosing commercial auto insurance in California. What vehicles does the business operate? What industry is it in? And how much would a serious accident actually cost the operation to resolve? Claim costs run higher in California's litigation environment than in most states, so that third answer shapes how much coverage the business actually needs, not just the legal minimum.

Price matters, but a policy that leaves a gap the California operation actually needs will cost more at claim time than a higher premium would have. Decide early whether a fully digital purchase with no agent involvement or a carrier that assigns a dedicated account manager and commercial adjuster fits better, because those two models point to different providers. Once that picture is clear, pull at least three quotes using actual vehicle types and industry classification to confirm the pricing holds for your specific fleet and location.

Best Commercial Auto Insurance in CA Chart
mglogo icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

Commercial auto insurance is only one piece of your best California business insurance bundle, and you will likely need more coverage to satisfy requirements and protect your company financially. Below, explore more state-specific guides to top insurers for other commonly needed business insurance types.

How We Built These Best Commercial Auto Insurer Rankings

California's rankings come down to three questions: what businesses in the state actually pay, how each carrier holds up once the policy is active, and whether coverage pays out cleanly when a claim is filed. Each of the five providers was scored on affordability (50%), customer experience (30%) and coverage options (20%). Affordability weighs heaviest because cost drives most first cuts, but the rate alone rarely decides the match. For the full data sources and scoring detail, see MoneyGeek's methodology.

About Mark Flores


Mark Flores, Business Insurance Writer, MoneyGeek

Mark Flores is a Business Insurance Content Writer at MoneyGeek, where he focuses on commercial auto, commercial property, cyber and specialty business insurance coverage. His work simplifies coverage terms, gives business owners a strong baseline for expected costs, and narrows down policies and providers tailored to your operation, regardless of complexity.

Before joining MoneyGeek’s business insurance team, Mark worked as a Senior Content Writer at Clutch.co, where he produced structured B2B reviews and provider analyses based on client interviews, company research and service evaluation. That experience shaped his approach to business insurance content, especially when comparing insurers, explaining coverage differences and translating complex policy features into practical guidance for small business owners.

Mark also spent nearly 4 years as a digital marketing specialist serving small-business clients across industries such as home services, manufacturing and education. That background gives him practical context for how businesses evaluate vendors, manage operational needs and make purchasing decisions.

At MoneyGeek, he applies this research and evaluation experience to build guides that help transportation sectors, those with complex property-related risks (such as hotels and retail stores), and those most at risk of a cyberattack get the coverage they need at a reasonable price.

Linkedin: https://www.linkedin.com/in/mark-jason-flores-7844634a/

Contact Email: mark.flores@moneygeek.com