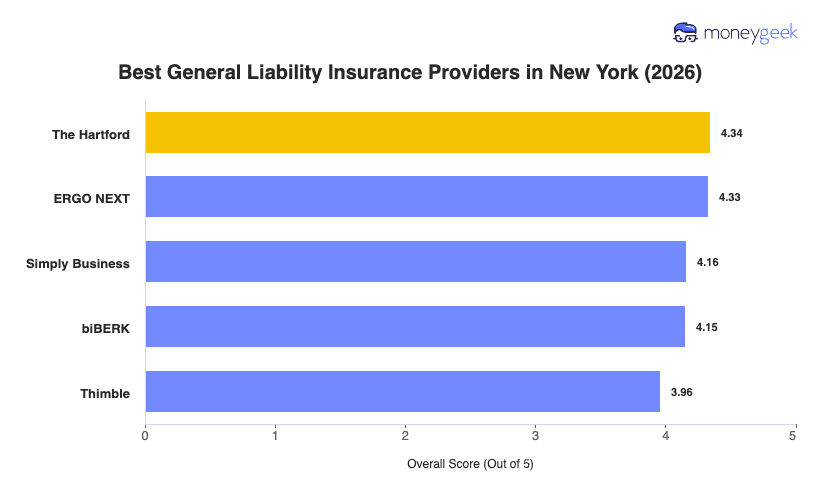
Best General Liability Insurance Companiesin New York

To find New York’s best general liability providers, I looked at how insurers explain eligibility and how easily you can update your policy or get proof of insurance. I then compared average rates of quotes from 10 insurers across 25 general industries, including professional and technical firms and transportation businesses, to see whether policies fit different types of work.

My top picks are:

  • Choose if you're in professional services: The Hartford
  • Choose if your business is customer-facing: ERGO NEXT
  • Choose if you want more coverage options: Simply Business
  • Choose if you a service-based business: biBerk
  • Choose if you're a freelancer or a gig worker: Thimble

For our New York general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of New York's small businesses, while weighting results to ensure broader industry and location representation across New York City, Buffalo, Rochester, Syracuse and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 5,700 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve New York businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to New York, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

5,739

Customer Experiences Analyzed

The Hartford

The Hartford: Best Overall, Best for Professional Services

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford tops our analysis of general liability insurers in New York, leading in affordability and ranking strong for coverage options. It saves New York businesses 17% on average and is the most affordable option for companies with one to 49 employees. Businesses in education, health care and agriculture see the most savings with The Hartford. 

The Hartford ranks first nationally for policy management and claims handling. Buying is its weak spot: an agent has to finish the purchase with you, and quotes take two to three business days instead of happening online.

Learn More: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Customer-Facing Service Businesses

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT ranks second overall for New York small businesses. Service quality is its strength: customers ranked the buying experience first and policy management second. Claims handling ranks sixth. Though the fully digital platform quotes and covers you in 15 minutes, some policyholders report disputes over settlement fairness and slow communication.

Most New York businesses pay $154 monthly, 13% less than the state average. Food service and hospitality businesses get the lowest rates, saving up to 30% monthly. Coverage options rank ninth due to limited endorsements and lower sublimits. ERGO NEXT covers damage to rented premises up to $100,000 versus the standard $300,000. That gap may leave NYC businesses in high-rent commercial spaces underinsured.

Learn More: ERGO NEXT Business Insurance Review

Simply Business

Simply Business: Best for Coverage Options

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business ranks third for customer experience. It connects New York small businesses with multiple carriers, including Hiscox, Travelers and The Hartford, through one submission. Coverage options rank fourth: you can weigh several carriers' policy structures side by side, though sorting out different sublimits and endorsements across quotes adds complexity. Post-purchase service depends entirely on which carrier underwrites your policy.

New York businesses pay $175 monthly, 2% less than the state average. Retail and repair businesses see the biggest savings, at 16% to 17%.

Learn More: Simply Business Review

biBerk

biBerk: Best for Service-Based Businesses

COMPANY HIGHLIGHTS

biBerk ranks fourth overall for New York small businesses, with competitive affordability and buying experience alongside mid-pack policy management and coverage. Berkshire Hathaway owns the company, which offers a hybrid model: agents are available during purchase to help with New York requirements. Reviewers point to agents explaining Scaffold Law disclosures and liquor liability without the rushed feel of traditional carriers.

New York businesses pay $165 monthly, an 8% savings. Service industries see the biggest rate cuts: hospitality saves 30%, repair and maintenance 28%, and health care 24%. Post-purchase service is a weaker spot. New York contractors report mixed results with certificates of insurance: simple requests process instantly, but complex NYC commercial real estate requests take one to two days for agent review.

Learn More: biBerk Review

Thimble

Thimble: Best for Freelancers and Gig Workers

COMPANY HIGHLIGHTS

Thimble ranks fifth overall for New York small businesses. Its on-demand model is unlike anything else on this list, but coverage and affordability both fall short. The platform's strength is flexible coverage periods: New York freelancers and gig workers can activate policies by the hour or day for a single project, then deactivate between jobs. Affordability is inconsistent. Most New York businesses pay $166 monthly, an 8% savings, but hospitality businesses pay 26% more than the typical rate, and marketing firms pay 17% more.

Coverage ranks last. Thimble doesn't cover New York construction businesses with Scaffold Law exposure, offers no liquor liability, and provides very limited endorsements. Claims handling trails the top options too: New York reviewers report settlement offers 30% below repair quotes, plus weeks-long gaps in communication.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for New York Businesses

Choose a provider that understands how your New York business operates, not just where it's registered. A contractor may need revised insurance documents for several job sites. A food producer needs protection that continues after a product leaves its facility. The best general liability insurance addresses those needs.

How to Choose the Best General Liability Insurance in New York

To get general liability insurance that matches your New York operations, start with knowing what your business needs. Then use the steps below to narrow the field and find an insurer that provides value both for the short- and long-term.

  1. 1
    Optimize your payment and coverage structure

    Identify the liability risks your New York business carries, then match coverage levels to them. A Bronx food service business that serves alcohol needs different limits and endorsements than a freelance graphic designer working from a home office in Rochester. Start with these questions:

    • Would paying the annual premium upfront strain your cash flow? Monthly billing spreads out payments, but installment fees increase the total cost.
    • What liability limits do your leases and client contracts require? Check whether you also need to add a landlord or client as an additional insured.
    • Are you planning to open another location or offer a new service within the next year? Make sure the insurer accepts those operations and can update your policy when the change happens.

    Most New York small businesses start at $1 million per occurrence and $2 million aggregate. Actual needs then shift based on your work, your clients and any additional general liability requirements in your contracts. A Manhattan event planning company managing high-value weddings needs higher limits and liquor liability, while a solo IT consultant working from home in Buffalo can stay at standard coverage.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    Decide which factor matters most to you today. If two providers look about even, that factor makes the call.

    • Affordability comes first if you're starting a Brooklyn retail shop or an Albany consulting firm with limited startup cash. It also comes first when a 20% premium hike would force cuts elsewhere, or when your low-risk, predictable operation gets more from steady rates than from extra endorsements.
    • Customer experience comes first if you're a contractor bidding on NYC jobs that need certificates within 24 hours. It also fits a Syracuse event planner who changes policies often for seasonal staff and new venues, and anyone with Manhattan commercial clients who need paperwork fast.
    • Coverage options come first if you run a Rochester restaurant that serves alcohol, a construction company working across multiple boroughs or a business growing from Buffalo into downstate markets. If your work is higher risk, or your clients have their own endorsement demands, you need a policy that can scale.
  3. 3
    Shortlist two to three providers

    Cut your list to two or three insurers that match your priority and will really write your New York business. What works for a Manhattan retail shop may not work for a construction company that operates in all five boroughs. And great service upstate does nothing for a Brooklyn restaurant that needs liquor liability endorsements.

    Check that every provider on your shortlist covers your industry, your New York locations and the coverage structure you set in step one.

  4. 4
    Double check for dealbreakers before investing more time

    Check each provider against your non-negotiables before you go deeper. If it fails any one of these, cross it off:

    • Does it write policies for your industry in New York?
    • Can it issue certificates in time for your contract deadlines? This matters most for NYC project work.
    • Does it offer the endorsements your landlord, clients or contracts require?
    • Can it cover your business across several New York locations or counties?
    • Does it have an online portal for mid-term changes and certificate requests?
    • Do its adjusters know New York liability law, and do they respond within 24 to 48 hours?
  5. 5
    Compare your finalists using the same three lenses

    One priority gets you a shortlist, but it can't stand in for a full comparison. An insurer that shines in one area and stumbles in the other two will cause trouble at renewal. Judge every finalist on all three:

    • Affordability: Look at how steady renewal rates are, how clearly the insurer explains premium changes and whether its audits are transparent. Stable pricing over the years matters more than the lowest opening quote.
    • Customer experience: See how quickly certificates arrive for New York contract work, how simple midterm policy changes are online and how fast claims get a response. Find out whether adjusters understand state liability law.
    • Coverage options: Make sure the endorsements you need are on offer (liquor liability, additional insured, product liability). Check that the limits can flex as you grow and that the policy can follow you into new parts of New York.
  6. 6
    Use quotes as the final confirmation step

    Compare business insurance quotes from your top two finalists, using your real business details. A quote shows whether the provider will cover your Brooklyn storefront or Albany office, fits your industry classification and revenue size, and can write the endorsements your clients require. Use quotes to confirm your earlier comparison, not to restart it.

Best Small Business General Liability Insurance in New York: Bottom Line

The Hartford, ERGO NEXT, Simply Business, biBerk and Thimble lead for New York small business general liability, though the best fit depends on your industry's liability exposure, how many employees you have and which New York counties you serve. 

Weighing long-term rate stability, responsiveness during policy changes and claims and available endorsements for your specific risks ensures your coverage aligns with how your business actually operates. It also allows you to scale without requiring a carrier change when you hire staff or add locations.

Best General Liability Insurance for Small Business in New York Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

Besides general liability insurance, you'll likely need other coverages in your policy mix. Check the resources below and see which providers we recommend for other coverage types you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com