The best workers’ comp insurer for your business is the one that charges a fair price for your kind of work and still takes good care of employees who get hurt, and which of those deserves more weight depends on how often injuries happen in your line of work and how serious they tend to be. Here’s how to decide:

  • Choose the best insurer if your employees do asbestos removal, concrete or masonry work, or drive for the job, since these are among the costliest jobs to insure in New York and a single fall or crash can keep a worker off the job for months. (Compare the Best Insurers)
  • Choose the cheapest insurer if your employees do accounting, bookkeeping or graphic design work, since those jobs face fewer risks and serious injuries are less common. (See the Cheapest Insurers)
Best Workers' Comp Insurance Companies in New York

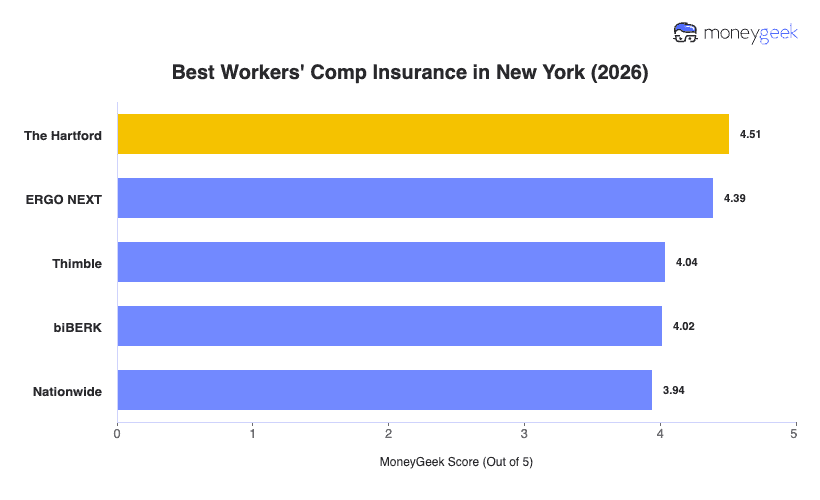
The Hartford is New York’s best workers’ comp insurance company, with a MoneyGeek score of 4.51 out of 5 and an average rate of $206 a month per employee, 23% below the $266 state average. It also has the most complete coverage of the insurers we compared and sells New York’s required disability and paid family leave coverage alongside workers’ comp. ERGO NEXT ranks second at 4.39 out of 5 on its low rates and the highest-rated customer service of the insurers we compared.

ERGO NEXT and The Hartford are nearly tied in New York, with average rates just $1.41 a month per employee apart, so the better choice depends on what matters more to your business. The Hartford is stronger on claims support, while ERGO NEXT is faster to buy from, with the whole purchase handled online.

Best Overall and for Healthcare Practices
4.51
$206
1 million+ provider network, New York disability and paid family leave coverage
Contractors Buying Online
4.39
$207
Online purchase in about 10 minutes, blanket waiver of subrogation added online
Collecting Subcontractor Certificates
4.04
$229
Free Certificate Manager, waiver of subrogation included when you add additional insureds
Buying Direct Without a Broker
4.02
$254
Sold directly with general liability, a BOP and umbrella coverage
Risk Management Support
3.94
$267
24/7 nurse triage for non-emergency injuries

The cards below show who each of the top three insurers suits and when another option is the better pick.

Featured Partner
The Hartford

The Hartford

  • The Hartford is MoneyGeek's cheapest workers' compensation provider in New York for 2026, scoring 4.51 out of 5.
  • New York rates average $206 a month per employee ($2,472 a year) at The Hartford, about 23% below the state average of $269.
  • New York is one of 27 states where The Hartford is the cheapest workers' comp insurer MoneyGeek analyzed.
  • The Hartford assigns nurse case managers who coordinate care from the first report of injury through recovery.
On The Hartford's site

*MoneyGeek featured partner. Editorial rankings below are independent of this placement. Rates, rankings and savings comparisons are based on MoneyGeek's independent research and Hartford-reported data as of 2026. Figures are estimates and averages, not a guarantee of any individual quote, premium or discount.

The Hartford

The Hartford: Best Overall, Best for Healthcare Practices

On The Hartford's site
checkmarkpros
  • Cheapest for all 49 healthcare business types we analyzed

  • Above-average customer service

  • Disability and paid family leave coverage sold alongside workers’ comp

  • Saves 10% on commercial auto when paired with workers’ comp

closecons
  • Costs 30% above average for construction and 26% above for transportation

  • Lower-rated customer service than ERGO NEXT

COMPANY HIGHLIGHTS

The Hartford is the best workers’ comp insurer in New York for most small businesses, because it has the lowest average rate, $206 a month per employee and 23% below the state average, and it doesn’t trade service or coverage to get there. It’s the cheapest insurer for every healthcare business type we analyzed and for 32 of 39 retail types, which makes it the natural fit for medical offices, home care agencies and shops. For a home healthcare agency, its needle stick reimbursement program helps pay for testing both the aide and the patient if an aide is stuck by a needle in a client’s home. New York also requires employers to carry disability and paid family leave coverage, and The Hartford sells that coverage too, so both required employee policies can sit with one insurer. Where it falls short is price for contractors and transportation businesses, which pay $1,295 and $1,038 a month per employee with The Hartford, so those businesses should compare ERGO NEXT.

Read Our Review: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Contractors Buying Online

On ERGO NEXT's site
checkmarkpros
  • Cheapest for 38 of 45 construction business types we analyzed

  • Highest-rated customer service of the insurers we compared

  • Blanket waiver of subrogation added from your online account

  • Optional coverage for business owners

closecons
  • No scheduled waivers of subrogation

  • Costs more than The Hartford for every healthcare business type

COMPANY HIGHLIGHTS

ERGO NEXT is the best workers’ comp insurer for New York contractors and ranks second overall at 4.39 out of 5, driven by low rates and the highest-rated customer service of the insurers we compared. Its construction average of $650 a month per employee is 35% below the $998 industry average, and it has the lowest rate for 38 of the 45 trades we analyzed, along with most food service, recreation and transportation business types. A one-person handyman business doesn’t need workers’ comp under state law, but a general contractor may still require a policy that covers the owner, and ERGO NEXT lets you add owner’s coverage and buy online in about 10 minutes. If a contract calls for a waiver of subrogation, you can add a blanket waiver from your account, though it usually raises your premium and scheduled waivers aren’t available. Where it falls short is healthcare, where it costs more than The Hartford for every business type we analyzed, so medical offices and home care agencies should compare The Hartford.

Read Our Review: ERGO NEXT Business Insurance Review

Thimble

Thimble: Best for Collecting Subcontractor Certificates

checkmarkpros
  • Free Certificate Manager for tracking subcontractors’ coverage

  • Waiver of subrogation included when you add additional insureds

  • Second-lowest construction average, 20% below the industry average

closecons
  • Lowest-rated customer service of the insurers we compared

  • Workers’ comp is issued by a partner insurer, not Thimble

COMPANY HIGHLIGHTS

Thimble ranks third at 4.04 out of 5, mainly on affordability, and it’s the best choice for New York general contractors who hire subcontractors, because its free Certificate Manager lets you request and collect each sub’s proof of coverage in one place. That paperwork matters in New York, where anyone working on your construction job is presumed to be your employee and insurers often charge a general contractor for every subcontractor who can’t show its own policy. Its prices hold up for contractors, too, with a construction average of $799 a month per employee, 20% below the $998 industry average, and the lowest rates for lawn care, snow removal and tree surgery businesses. When a client asks to be added to your policy, Thimble includes a waiver of subrogation automatically, so you don’t have to request one separately. Where it falls short is service, since it has the lowest-rated customer service of the insurers we compared and its policies are issued by a partner insurer, so contractors who care more about price and claims help than tracking subs should compare ERGO NEXT.

Read Our Review: Thimble Business Insurance Review

Cheapest Workers' Comp Insurance in New York

The Hartford has the cheapest workers’ comp insurance in New York at $206 a month per employee, 23% below the $266 state average, and ERGO NEXT is close behind at $207. The cheapest policy makes sense when your employees rarely get hurt and their injuries tend to be minor, as in a bookkeeping office where most claims are small and heal quickly. It’s riskier when the work is among the most expensive to insure, like concrete, masonry or asbestos removal, or involves driving all day, because one serious injury can mean a long recovery and a claim that depends on how well the insurer manages care. Janitorial services fall in between, since crews lift heavy equipment and work around wet floors and chemicals, so a single injury can turn into weeks of treatment. ERGO NEXT is cheapest there at $180 a month per employee, but The Hartford costs about $1 more and assigns nurse case managers to coordinate an injured worker’s care, which makes it the safer pick for that level of risk.

The Hartford
$206
$2,468
23%
ERGO NEXT
$207
$2,485
22%
Thimble
$229
$2,743
14%
biBERK
$254
$3,047
5%

Your industry affects your price far more than these statewide averages do. Each insurer sets its own rate for every employee job classification, charged per $100 of payroll, so the cheapest insurer for a dental office often isn’t the cheapest for a concrete contractor. Of the 408 business types we analyzed, The Hartford is cheapest for 181, mostly medical practices, stores and office-based firms, and ERGO NEXT is cheapest for 169, mostly construction trades, food businesses, recreation venues and transportation companies. The sections below show the cheapest insurers in six of New York’s largest small business industries.

How to Get the Best Workers' Comp Insurance in California

New York asks more of employers than most states, with a separate disability policy on top of workers’ comp, its own rating bureau and strict rules about who counts as your employee. These steps cover what a New York business owner needs to sort out before buying and after.

Best Workers' Compensation Insurance in New York: Bottom Line

The Hartford is the best workers’ comp insurer in New York and the cheapest on average, and it fits medical practices, stores and office-based businesses best, especially owners who want strong claims support and New York’s required disability and paid family leave coverage from the same insurer. ERGO NEXT is the better choice for contractors, restaurants and other businesses that need coverage in place before a job or event, since it’s cheapest for most construction trades and handles the whole purchase online. Thimble suits general contractors who hire subcontractors and need an easy way to collect proof of their coverage. Whichever insurer looks right, get quotes from it and at least two others using the same NYCIRB classifications and payroll estimates, and line up your disability and paid family leave policy at the same time.

Best Workers' Comp Insurance in New York Chart
mglogo icon
WANT TO LEARN MORE ABOUT OTHER BUSINESS INSURANCE TYPES?

Workers’ comp is only one part of commercial insurance that you likely need. Check our other resources for coverage in the state below to ensure you have comprehensive coverage:

New York Workers' Compensation Insurance FAQs

How We Determined the Best and Cheapest Workers’ Comp Insurers in New York

MoneyGeek analyzed estimated workers’ comp rates from eight insurers that sell to New York small businesses, which are biBERK, Chubb, ERGO NEXT, Hiscox, Nationwide, Progressive Commercial, The Hartford and Thimble. Our analysis covers 408 business types across 25 industry categories, and every rate on this page is a monthly estimate per employee.

MoneyGeek scores: Each insurer is scored out of five in three categories, which we combine into a weighted overall score.

  • Affordability (55%): Based on average payroll for the most common job classification in each industry, priced per employee.
  • Customer experience (35%): Covers buying (20%), including quote access, pricing accuracy and sales support; policy management (30%), including payroll reporting, audits, billing and loss control; and claims (50%), including how quickly claims are reported and handled, adjuster support, medical access, wage replacement and dispute handling.
  • Coverage options (10%): Covers coverage completeness (35%), policy flexibility and endorsements (25%), eligibility across industries (20%), and policy terms, limits and exclusions (20%).

Averages and savings: New York’s $266 monthly average per employee is the simple mean of the eight insurers’ statewide rates, and each industry average is the mean of their rates for that industry. Business-type averages are the mean of the insurers with rates for that business type. Each savings figure shows how far an insurer’s rate falls below the average for the same group, so statewide rates are measured against the state average, industry rates against their industry average and business-type rates against their business-type average. Rates by business size are averaged across every industry category. All dollar amounts and percentages are rounded to whole numbers, and where rounding makes two rates look the same, we note the gap in cents.

Featured industries and tables: The six industries in the cheapest section come from the sectors with the most small employers in the SBA’s 2026 New York small business profile, with priority given to industries where workers’ comp is a major cost. Each table shows up to 15 common business types, or every type when a category has 15 or fewer. Business-type rates include seven of the eight insurers, because Chubb doesn’t have rates at that level.

Coverage and requirements: Coverage details, such as claims support, waivers of subrogation, pay-as-you-go billing and disability and paid family leave coverage, come from each insurer’s published materials. New York requirements come from the Workers’ Compensation Board, the New York Compensation Insurance Rating Board and the other state sources linked throughout this page.

These figures are estimates, not personalized quotes. Your premium depends on your NYCIRB classifications, payroll, claims history and the insurer you choose. MoneyGeek partners with some of the insurers on this page through our matching tool, but those partners have no say in our rankings or recommendations. See our advertising disclosure and full business insurance methodology for more details.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources