Best General Liability Insurance Companies in Michigan

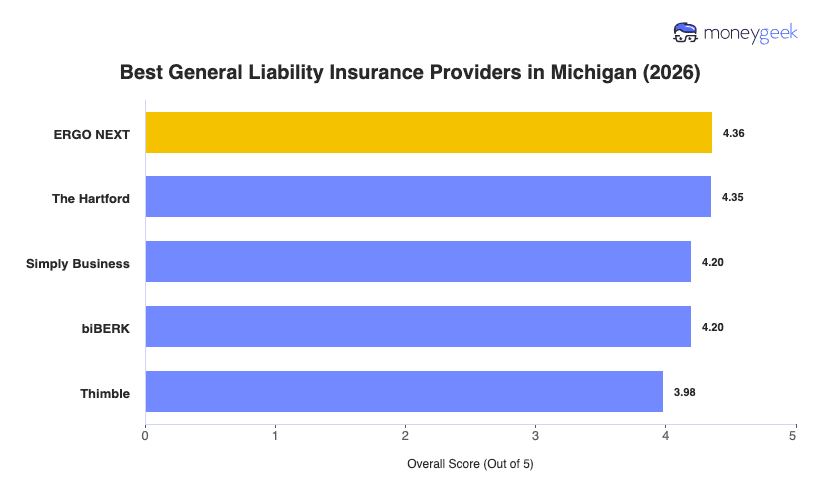
To determine Michigan’s best general liability providers, I started by comparing average rates from 10 insurers across 25 general industries, including small manufacturers and firms providing professional and technical services. Then, I focused on whether you’re likely to receive clear instructions during product-related GL claims and if you can easily get proof of insurance that matches a client contract.

My top picks are:

For our Michigan general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent nearly half of Michigan's small businesses, while weighting results to ensure broader industry and location representation across Detroit, Grand Rapids, Lansing, Ann Arbor and smaller markets throughout the state.

To do this, we evaluated over 20,000 business profiles, more than 2,900 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Michigan businesses consistently across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Michigan, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

2,963

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Solo Operatorsand Hands-On Industries

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT tops our general liability insurers analysis, saving Michigan businesses 13% on average at $101 monthly. It’s the most affordable option for 12 industries, including hospitality (35% savings), manufacturing (28% savings) and repair services (27% savings). ERGO NEXT’s fully digital buying process delivers instant quotes and fast COI generation, strengths contractors and consultants prioritize.

The coverage options don't include specialized endorsements for liquor liability or pollution coverage that restaurants or environmental service businesses need. Adjusters tend to respond slowly during claims, and the settlement explanations can be confusing.

Learn More: ERGO NEXT Business Insurance Review

The Hartford

The Hartford: Best Cheap General Liability Insurance

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford offers liquor liability and limited pollution coverage that online-only competitors don't have. They also have offices in Detroit, Grand Rapids, and Ann Arbor.

Small businesses of all sizes get their best rates through The Hartford. Solo owners save about 15%, while midsize companies typically save around 21%.

Learn More: The Hartford Business Insurance Review

Simply Business

Simply Business: Best for Comparing Multiple Carriers

On Simply Business site
COMPANY HIGHLIGHTS

Unlike other providers in our analysis, Simply Business does not underwrite its own policies. Instead, it acts as an insurance marketplace that connects businesses with multiple carriers, like Hiscox, Travelers, Liberty and others. Its platform provides buyers with a positive experience, with instant multi-carrier quote comparison. Policy management and claims handling then route to whichever carrier you select, not Simply Business itself.

Coverage options vary by carrier, letting Michigan businesses compare endorsement availability and limits side-by-side. While it’s not the most affordable option, its monthly rate of $113 is 5% lower than the state average. Tech and IT businesses save 23%, and retail saves 18%, while construction costs 10% more than average and marketing costs 15% more.

Learn More: Simply Business Review

biBerk

biBerk: Best for Service Businesses

COMPANY HIGHLIGHTS

biBerk ties with Simply Business for third overall in Michigan, saving businesses 9% on average at $105 monthly. The Berkshire Hathaway subsidiary posts its strongest numbers in hospitality (30% savings), health care (25%) and manufacturing (27%), with competitive rates for cleaning, fitness, food service and real estate. Savings do thin out as businesses grow; sole proprietors save 14%, while mid-size companies save 6%.

The tradeoffs show up in service and coverage. The digital-first platform delivers instant quotes but slower ongoing support. Reviews cite a five-day turnaround for additional insured requests, compared to instant generation from competitors. biBerk also doesn't offer liquor or pollution liability endorsements.

Learn More: biBerk Review

Thimble

Thimble: Best for On-Demand Coverage

COMPANY HIGHLIGHTS

Thimble ranks fifth overall for Michigan general liability insurance. It's an on-demand platform that lets businesses buy coverage by the hour, day, week, month or year. This pay-as-you-go model provides instant quotes. Thimble costs more than other insurers overall. Michigan construction businesses save 22% with Thimble. Manufacturing businesses save 19%.

You won't find a lot of coverage flexibility with Thimble. Endorsements are minimal. Limit caps run lower than traditional carriers offer. Claims handling is a weak spot too. Reviews cite settlement disputes and disagreements over the coverage period, including whether coverage was active when the incident occurred.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Michigan Businesses

An insurer may understand that you manufacture parts without realizing that your technicians also install them inside customer plants. That difference can affect your policy and whether you meet a buyer’s insurance terms. Compare general liability insurance in Michigan options using a complete description of how you work, not a broad industry label.

How to Choose the Best General Liability Insurance in Michigan

To get general liability insurance that's right for your Michigan business takes more than comparing rates. These six steps help you pin down your priorities, narrow your options and confirm pricing lines up with your actual operations before you commit.

  1. 1
    Optimize your payment and coverage structure

    Your risk profile determines which general liability policy fits. Most Michigan small businesses carry $1 million per occurrence and $2 million aggregate, which is enough to meet common general liability requirements.

    Ask yourself:

    • Does winter bring more slip-and-fall accidents?
    • Are off-season months lighter on income, which could strain annual payments?
    • Do products cross state lines or ship into Canada?
    • Do your contracts call for proof of higher coverage limits?

    Monthly and annual payments both work, depending on your cash flow. A Traverse City marina that runs May through September needs monthly payments that match its income. A Dearborn tool shop with steady year-round income can pay annually and save 5% to 10%. Choose limits, a payment schedule and a deductible that suit your business.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2
    Choose your primary priority

    What you should weigh most comes down to your situation today:

    • Affordability: Do you work under fixed-price supply contracts in Michigan? Then price should come first, since a large renewal increase would cut into the margin you planned on.
    • Customer experience: Automotive customers often ask for proof of insurance before you can set foot on their property. If a slow certificate or policy update could hold up a job, put service first.
    • Coverage options: Planning to install products at customer sites or bid on bigger industrial contracts? Then weigh policy fit more heavily, because your insurer has to offer the limits or endorsements those jobs call for.
  3. 3
    Shortlist two to three providers

    Limit your shortlist to two or three providers so the detailed comparison stays manageable. Eliminate any insurer that won't cover all your regular operations. A Michigan manufacturer that makes parts and installs them at customer plants needs both activities included. Of the rest, keep those that appear strongest on your chosen priority.

  4. 4
    Double-check for dealbreakers before investing more time

    Some problems make a policy unusable for the way you work, even when the price looks great. Rule out any provider if one of these sounds familiar:

    • Your technicians install equipment at customer plants, but the insurer covers only shop work. If a service you regularly provide is left out, the policy doesn't fit.
    • You make or sell products, but the policy excludes injuries and property damage that happen once the product has left your business. That removes a big piece of your protection.
    • Clients give you one business day to prove coverage, but the insurer takes several days. You could lose the start date.
    • A current contract needs higher limits or an additional insured endorsement, and the provider can't add either. You wouldn't qualify for that contract.
  5. 5
    Compare your finalists using the same three lenses

    Next, line up the insurers that passed the dealbreaker check and compare what they told you. When two are neck and neck, your top priority makes the call.

    • Affordability: Did the provider tell you what could push your renewal price up, and how much warning you'd get? If the answer was vague, the low starting rate is harder to believe.
    • Customer experience: See how quickly each one got back to you. Check whether you could use the answer right away or had to keep asking follow-up questions.
    • Coverage options: Pose the same change to every insurer, like raising your limits for a bigger contract. Ask if it can update your current policy and what that would involve.
  6. 6
    Use quotes as the final confirmation step

    Tell every finalist the same thing about what your business does, and ask each for the same limits and the endorsements your contracts require. When you compare business insurance quotes, you'll see what each one charges for the same coverage. A quote that's far lower deserves a question. Ask the insurer to explain the gap, and make sure nothing you requested got left out.

Best Small Business General Liability Insurance in Michigan: Bottom Line

NEXT, The Hartford, Simply Business, biBerk and Thimble are the best general liability insurance providers in Michigan, though the right match depends on your industry, business size and how you operate.

Best General Liability Insurance for Small Business in Michigan Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

While general liability coverage is an important part of your coverage mix, the best Michigan small business insurance policy usually includes other coverage types. I've put together some resources so you can see our recommended providers for the different coverages you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com