Best Business Insurance Companies For Mobile App Development

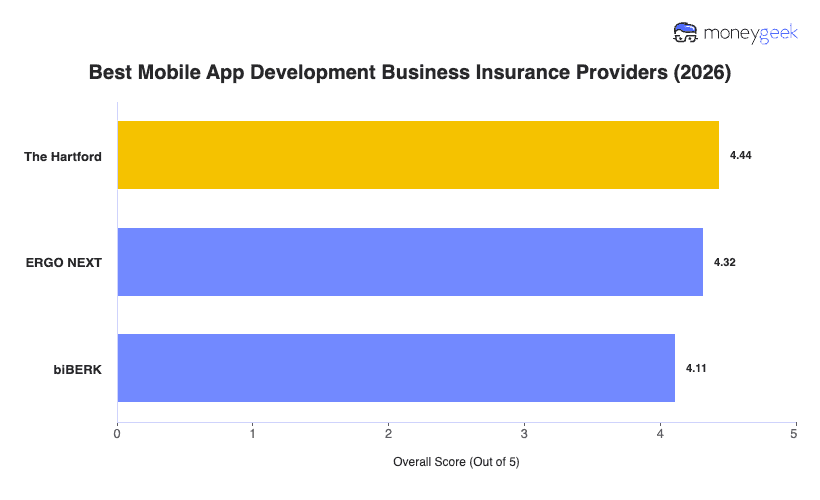
My analysis ranked these companies as the best small business insurers for mobile app developers:

  • Choose if you want the lowest rates and the broadest coverage: The Hartford
  • Choose if you need fast coverage and full online policy management: ERGO NEXT
  • Choose if you run a small team and prefer buying online: biBERK

Mobile app development insurance can look straightforward on a quote sheet until a claim tied to a client's app failure, a breach traced to your code or a contract dispute over scope reveals what your policy actually covers. My rankings are built on three things: what you'll actually pay, what happens when you need help and whether the coverage holds up when it counts. I scored each provider across affordability (50%), customer experience (30%) and coverage options (20%), weighted that way because premium cost determines what a solo developer or small studio can realistically sustain, but a cheap policy with weak claims support or narrow tech E&O terms defeats the purpose.

This is what made up my analysis of popular insurers, which was assisted (not run) by AI:

  • Affordability: I pulled quotes isolating pricing factors across technology and IT sub-industries, all 50 states (plus DC), employee count (5 ranges from 0 to 49), 16 vehicle types (for commercial auto) and six of the most common coverage types, extrapolating 500,000+ estimates to build a full pricing picture for mobile app development businesses specifically.
  • Customer Experience: 300,000+ reviews, forum conversations and industry research were aggregated and manually parsed to identify the patterns that made customers enjoy and dislike service from each insurer. I also went through what an actual mobile app development business owner would go through for all providers analyzed, testing their quoting experiences and policy management tools (excluding claims due to limitations).
  • Coverage Options: I read the fine print of policy terms, isolated the exclusions and hidden costs that affect mobile app developers (like technology services definitions, retroactive date restrictions and cyber sub-limits), and documented every option available for all providers to determine which has the best coverage for your business now and as your studio grows.
The Hartford

The Hartford: Best Overall, Best for Lowest Rates and Broadest Coverage

On The Hartford's site
checkmarkpros
  • 25% below sub-industry average pricing

  • FailSafe bundles Tech E&O and cyber

  • In-house claims adjusters and dedicated agent

closecons
  • No online self-service purchasing option

  • Binding takes longer than digital competitors

  • Policy changes require calling your agent

COMPANY HIGHLIGHTS

At 25% below the sub-industry average, The Hartford costs less than any other provider in this analysis for mobile app developers. Its FailSafe Tech E&O policy combines professional liability and data privacy coverage under a single policy, so a client claiming your code caused a breach doesn't generate two separate claims with two separate adjusters. It also writes cyber, workers' comp, general liability and commercial property through one carrier, which matters when enterprise contracts require coordinated limits across multiple coverage types.

The tradeoff is that everything runs through an agent. You can't quote, bind or pull a COI through a self-service portal, and if a client contract lands Friday with proof of insurance due Monday, that agent dependency creates real friction. Policy changes follow the same path.

Read Our Review: The Hartford Business Insurance Review

ERGO NEXT

ERGO NEXT: Best for Speed and Self-Service

On ERGO NEXT's site
checkmarkpros
  • Quote to COI in roughly 10 minutes

  • Ranks first for customer experience

  • 10% discount stacking professional liability

closecons
  • Cyber underwritten by Coalition, not in-house

  • No dedicated agents for tech businesses

  • Professional liability caps at $1M per claim

COMPANY HIGHLIGHTS

If you are a freelance developer or a small studio that needs proof of insurance before a contract conversation ends, ERGO NEXT is built for that speed. Backed by Munich Re, it ranks first for customer experience in my analysis, and the entire process from quoting to downloading a shareable COI runs through its app or web portal without speaking to anyone. Stacking professional liability onto an existing policy triggers a 10% discount, which brings the combined cost closer to what you would pay for each coverage separately through other carriers.

Where ERGO NEXT falls short is with more complex coverage needs. Professional liability maxes out at $1M per claim and $2M aggregate, which won't satisfy enterprise MSAs that specify higher limits. Cyber runs through Coalition rather than ERGO NEXT's own underwriting, so a contested cyber claim adds a third party to the process. If your clients sit in regulated industries and their contracts push coverage terms beyond the standard, you'll hit those ceilings.

Read Our Review: ERGO NEXT Business Insurance Review

biBerk

biBERK: Best for Small Studios Buying Direct

checkmarkpros
  • Berkshire Hathaway backed, A++ AM Best

  • Fully online quoting and binding

  • No broker fees or agent middleman

closecons
  • Ranks fifth for customer experience

  • Weaker coverage breadth than top two

  • Limited tech-specific policy customization

COMPANY HIGHLIGHTS

biBERK is Berkshire Hathaway's direct-to-business carrier, and that structure removes the broker layer entirely. You quote, bind and manage your policy online, and the A++ AM Best rating behind it means the financial backing on your claim is among the strongest in the industry. For a two or three person app development studio that needs professional liability and GL without navigating an agent relationship, biBERK keeps the process simple and the overhead low.

The simplicity comes with limits. biBERK's coverage options are narrower than what The Hartford or ERGO NEXT offer for technology businesses, and it ranks fifth in customer experience in my analysis. If you need tech-specific endorsements, higher cyber limits or policy terms tailored to the way software engagements actually work, those gaps will surface. It handles the basics well for small operations that don't carry complex contract requirements.

Read Our Review: biBerk Business Insurance Review

What Types of Insurance Do Mobile App Development Need?

Unlike most small businesses, your primary liability has nothing to do with physical work or a storefront. It lives entirely in contracts and code. Every app you deliver creates professional accountability to a client, and every app that handles user data creates breach exposure that follows you long after the project closes. Those two realities put professional liability and cyber insurance at the center of your coverage stack, regardless of whether you freelance from a home office or run a 15-person studio.

The other policies depend on how your operation is structured. The table below breaks down the coverages that apply to mobile app development businesses, ordered by how central each one is to the way this industry creates risk.

Defense costs and settlements when a client claims your code, missed deadline or failed deliverable caused them financial harm
Every app developer should carry this before signing a client contract

Roughly 53% of tech companies face a professional liability claim within five years, with average lawsuit costs running between $100,000 and $500,000 in legal fees and settlements.

Breach notification costs, regulatory penalties, forensic investigation and third-party claims when user data in an app you built is compromised
Any developer who stores client credentials, handles API keys or builds apps that collect personal information

Third-party breaches doubled year-over-year to 30% of all incidents in 2025, and a single breach traced to a vulnerability in your code can trigger notification costs, client indemnification and regulatory response simultaneously.

Claims and legal costs when a client or visitor is injured at your office or when you damage someone's property during an on-site visit
If clients visit your workspace, you attend their offices for sprint reviews or you exhibit at trade shows and conferences
Most enterprise MSAs require proof of GL before work starts, and even a straightforward injury claim from a client visit to your office can generate five-figure defense costs.
Medical bills and lost wages for employees injured on the job, including repetitive strain injuries from sustained computer work
The moment you hire your first employee in most states, including part-time or contract developers who qualify as employees

Nearly 946,500 workers reported musculoskeletal disorders in 2023, and developers are particularly susceptible to carpal tunnel and repetitive strain during intense sprint cycles.

Damage or loss to your development workstations, test device libraries, servers and office contents from fire, theft or other covered events
If you lease office space, maintain a dedicated home office setup or own equipment your renter's or homeowner's policy excludes
A five-person studio can easily carry $50,000 or more in workstations, monitors and test devices that a landlord's policy does not cover and a homeowner's policy may exclude for business use.
Bundles general liability and commercial property into a single policy, often at a lower combined premium than purchasing each separately
Small studios that need both GL and property coverage and want to simplify their insurance into fewer policies
A BOP covers both third-party liability and your own property losses in one policy, reducing total premium and administrative overhead for small operations.
Extra liability protection that kicks in after your primary policy reaches its limit
When an enterprise contract or client engagement requires combined limits above what your base GL or professional liability policies provide
A single disputed app failure that reaches end users at scale can generate claims that blow past standard $1M or $2M primary limits, especially when the app handles financial transactions or regulated data.
mglogo icon

WHY GETTING MOBILE APP DEVELOPMENT INSURANCE IS IMPORTANT

The gap between what insurance costs and what a single claim costs makes the math straightforward. Professional liability for an app developer runs about $74 per month. One client dispute over a failed integration or missed delivery that reaches litigation can cost $100,000 to $500,000 in legal fees and settlement before you factor in the lost revenue from a project that stalls while the claim plays out. Cyber exposure follows the same pattern at a larger scale. The average U.S. data breach cost hit $10.22 million in 2025, and while a small studio's breach won't reach that figure, the notification costs, regulatory penalties and client indemnification from a single incident can easily reach six figures. Carrying coverage before the first claim arrives is what separates a recoverable setback from a business-ending event.

How Much Does Mobile App Development Business Insurance Cost?

Cyber insurance drives the highest premiums for app developers at $154 per month because of the direct breach exposure your work creates through client data, API credentials and user information flowing through the apps you build. Whether you work in regulated verticals like healthcare or fintech, the size of your active user base and your average contract value are the three factors that move your premium most. Overall, mobile app development business insurance costs average $59 per month across all coverage types.

Here's an overview of costs for common coverage types:

What Are These Costs Based On?

Our business insurance calculator below can give you a more tailored estimate based on your business details. It also connects you directly with a provider match when you're ready to get quotes.

Mobile App Development Insurance Cost Calculator
Select Coverage Type
Select Employee Count
Select Vehicle Type
Select State
Average Monthly Cost—

How To Buy The Best Mobile App Development Business Insurance

The first document to pull before you do anything else is the insurance section of your most recent client contract. That contract, not a generic coverage checklist, sets the floor for what you actually need. I've outlined the full process below step by step, and you can download the mobile app development business insurance buying worksheet to keep everything organized across providers.

  1. 1

    Identify Required Coverages

    Your client contracts are where most coverage requirements live for app developers. Pull the insurance section from your most demanding MSA or statement of work and note every coverage type, limit and endorsement it specifies. Enterprise clients will often require you to name them as additional insured through a policy endorsement, which is a separate step from simply handing over a certificate of insurance (COI). If you build for healthcare clients, check whether their contracts also require a HIPAA business associate agreement alongside your standard proof of coverage.

    Read More: Business Insurance Requirements

  2. 2

    Map Your Business Risks to Coverage

    Walk through a specific scenario and test which policy would actually respond. Say a former client discovers that an authentication flaw in the app you built exposed their users' personal data six months after launch. Your general liability policy won't cover it because no one was physically injured. Cyber insurance covers the breach notification and regulatory response, while professional liability covers the client's claim that your defective code caused the damage. Run that exercise for every meaningful risk your work creates and flag anything without a clear policy match.

  3. 3

    Set Appropriate Limits For Your Risk

    Your limits should reflect the combined exposure across all active projects, not just your largest contract. If you carry three concurrent engagements worth $200,000 each and a code failure on one triggers claims on the other two, a $250,000 professional liability limit won't cover the total exposure. Size your Tech E&O to the sum of what could go wrong simultaneously, and size your cyber limits to the volume and sensitivity of the data your apps actually handle.

    Read More: How Much Business Insurance Do I Need?

  4. 4

    Research Providers Specific to Your App Development Business

    Not every carrier understands how technology engagements create liability. A provider unfamiliar with app development may define covered technology services too narrowly, exclude software-related claims from cyber coverage or write professional liability terms that don't account for how scope disputes and code defects actually trigger claims. Confirm that each insurer on your list writes Tech E&O and cyber for software businesses specifically before requesting any quotes.

  5. 5

    Compare Pricing and Quotes Apples to Apples

    Look up what app developers typically pay for your coverage types and firm size so you have a baseline going in. Then request quotes using identical limits, deductibles and endorsements across every provider. A policy that costs $20 less per month but narrows your retroactive date or carries a higher cyber deductible is not a real savings.

  6. 6

    Review Your Policy Before Buying

    Read the technology services definition in your Tech E&O policy before signing. If it doesn't explicitly include mobile application development, custom software or the specific services you deliver, a claim could be denied on the basis that your work falls outside covered activities. Verify that your retroactive date reaches back far enough to cover all active and recently completed projects, and confirm the named insured matches your legal business name exactly.

  7. 7

    Reassess Your Needs As Your Business Changes

    Landing your first enterprise client in a regulated industry, hiring your first developer or taking on a project that carries a contract value above anything you've handled before are all triggers to revisit your coverage. Moving from consumer apps to healthcare or fintech work changes your risk profile in ways that affect both your Tech E&O terms and your cyber limits. Review your policies at least once per year and before any major contract renewal.

Mobile App Development Insurance: FAQ

Beyond what this guide covers, I've answered the most common remaining questions app developers have before purchasing business insurance.

Best Mobile App Development Business Insurance: The Bottom Line

When comparing quotes, look beyond the price. Two policies can cost the same but cover mobile app development very differently. One Tech E&O policy may include custom app development, while another may limit coverage to IT consulting. Cyber policies can also differ in whether they cover issues tied to code delivered to clients or only data stored on your own systems. Before you start shopping around, here are my top overall picks for mobile app developers.

Best Mobile App Development Business Insurance Chart

Get Mobile App Development Business Insurance Quotes

Use our matching tool below to find providers that fit your mobile app development business. From there, you can get quotes and compare coverage directly on their site.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources