


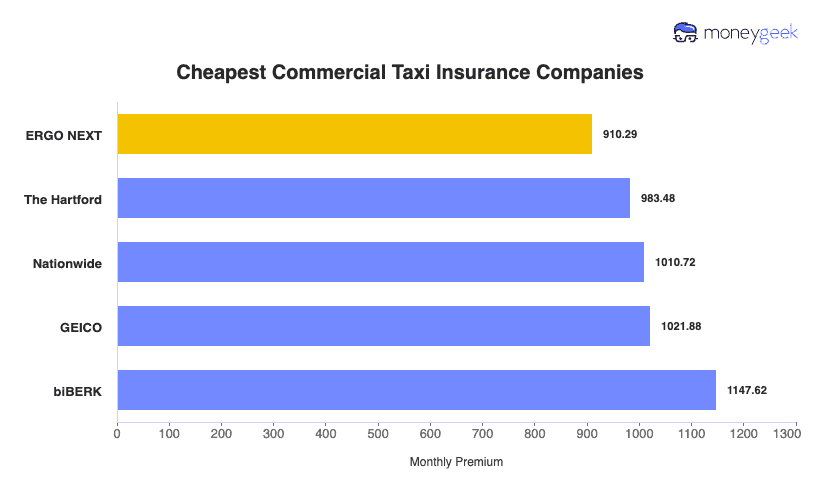
Progressive Commercial ranks as the best commercial auto insurer for taxis with a 4.62 overall score and the lowest rates at $910/month. The Hartford leads in customer experience with a 4.6 score. Nationwide offers solid bundling options at $1,011/month. Start with quotes from all three to find your best fit.
Best Taxi Insurance for Small Business
Progressive Commercial, The Hartford and Nationwide offer the best cheap commercial taxi insurance, with rates starting at $910 monthly.
Get matched to top commercial taxi insurance providers below.
Select state
Updated: September 8, 2026
Advertising & Editorial Disclosure
Best Commercial Taxi Insurance Companies
| Progressive Commercial | 4.62 | $910 | 4.27 | 4.99 |
| The Hartford | 4.56 | $983 | 4.60 | 4.96 |
| Nationwide | 4.33 | $1,011 | 4.40 | 4.38 |
| biBERK | 4.32 | $1,148 | 4.32 | 4.77 |
| GEICO | 4.14 | $1,022 | 4.06 | 4.19 |
MoneyGeek scored commercial taxi insurance providers across three weighted factors: Affordability (40%), Customer Experience (30%) and Coverage & Terms (30%). We analyzed 100/300/100 liability with $1,000 deductible for comp and collision quotes from 5 major insurers across all 50 states. Rankings updated quarterly using rate data current as of November 2025.
Read our full methodology for more details.

Progressive
Best Cheap Commercial Taxi Insurance for Owner-Operators
MoneyGeek Rating
4.6/ 5
4.7/5Affordability
4.3/5Customer Experience
5/5Coverage Points
Average Cost
$882/monthOur Survey: Claims Process
3.9/5Our Survey: Likely to Recommend to Others
4.8/5

The Hartford
Cheapest Commercial Taxi Insurance for Small Fleets
MoneyGeek Rating
4.6/ 5
4.4/5Affordability
4.6/5Customer Experience
5/5Coverage Points
Average Cost
$948/monthOur Survey: Claims Process
4.5/5Our Survey: Likely to Recommend to Others
4.5/5

Nationwide
Best Value Taxi Insurance for Small Business Owners
MoneyGeek Rating
4.1/ 5
4/5Affordability
4.1/5Customer Experience
4.2/5Coverage Points
Average Cost
$984/monthOur Survey: Claims Process
3.9/5Our Survey: Likely to Recommend to Others
4.3/5
Cheapest Commercial Taxi Insurance Companies
Progressive Commercial offers the cheapest commercial auto insurance for taxis in 35 states, with rates as low as $563/month in Maine. The Hartford leads in 11 states and Nationwide in 4 states. Find your state below and start with a quote from the cheapest carrier.
Data filtered by:
Select
| Alabama | The Hartford | $707 |
| Alaska | Progressive Commercial | $846 |
| Arizona | Progressive Commercial | $890 |
| Arkansas | The Hartford | $765 |
| California | Progressive Commercial | $1,019 |
| Colorado | Progressive Commercial | $977 |
| Connecticut | Progressive Commercial | $1,011 |
| Delaware | The Hartford | $860 |
| Florida | Progressive Commercial | $1,127 |
| Georgia | Progressive Commercial | $789 |
| Hawaii | Progressive Commercial | $668 |
| Idaho | Progressive Commercial | $627 |
| Illinois | Progressive Commercial | $974 |
| Indiana | Progressive Commercial | $776 |
| Iowa | Nationwide | $665 |
| Kentucky | The Hartford | $817 |
| Louisiana | The Hartford | $1,242 |
| Maine | Progressive Commercial | $563 |
| Maryland | GEICO | $1,020 |
| Massachusetts | Progressive Commercial | $1,018 |
| Michigan | Progressive Commercial | $1,048 |
| Minnesota | Progressive Commercial | $889 |
| Mississippi | Progressive Commercial | $765 |
| Missouri | Progressive Commercial | $948 |
| Montana | The Hartford | $711 |
| Nebraska | Nationwide | $707 |
| Nevada | Progressive Commercial | $907 |
| New Hampshire | Progressive Commercial | $613 |
| New Jersey | GEICO | $1,005 |
| New Mexico | Progressive Commercial | $806 |
| New York | Progressive Commercial | $1,292 |
| North Carolina | Progressive Commercial | $737 |
| North Dakota | The Hartford | $639 |
| Ohio | Progressive Commercial | $775 |
| Oklahoma | The Hartford | $749 |
| Oregon | Progressive Commercial | $848 |
| Pennsylvania | Progressive Commercial | $899 |
| Rhode Island | Progressive Commercial | $1,044 |
| South Carolina | Progressive Commercial | $794 |
| South Dakota | Nationwide | $902 |
| Tennessee | The Hartford | $854 |
| Texas | Progressive Commercial | $973 |
| Utah | Progressive Commercial | $695 |
| Vermont | Nationwide | $589 |
| Virginia | Progressive Commercial | $849 |
| Washington | Progressive Commercial | $1,000 |
| West Virginia | The Hartford | $786 |
| Wisconsin | Nationwide | $730 |
| Wyoming | The Hartford | $721 |
Data Source
Rates based on 100/300/100 liability with $1,000 deductible for comp and collision. Data current November 2025.
How Much Does Commercial Taxi Insurance Cost on Average?
Commercial auto insurance costs for taxis are around $983 monthly ($11,794 annually) on average for 100/300/100 liability with $1,000 deductible for comp and collision. Your state drives the biggest price gap: Maine operators pay $651/month while New York businesses pay $1,549/month.
Average Monthly Premium | $983 |
Average Annual Premium | $11,794 |
Lowest State (Maine) | $651/month |
Highest State (New York) | $1,549/month |
Monthly Range | $651 - $1,549 |
Data Source
Rates shown are state averages across all providers. Average % Savings compares your state to the $988/month national average. Rates based on 100/300/100 liability with $1,000 deductible for comp and collision. Data current November 2025.
Factors That Affect Commercial Taxi Insurance Costs
Eight factors determine your commercial taxi insurance premium. Review each factor below to identify where you can lower your rate.
 Passenger Capacity and Vehicle Configuration
Standard 4-passenger sedans cost less to insure than 6-passenger minivans or wheelchair-accessible paratransit vehicles. Minivans and SUVs used as hackney carriages pay 15% to 25% more due to higher passenger counts. ADA-compliant vehicles may qualify for accessibility discounts of 5% to 10%.
 Service Type and Operating Territory
Airport ground transportation and highway driving increase accident exposure compared to hotel shuttle or corporate account routes. Urban hackney operators in New York, Chicago or Los Angeles pay 40% to 60% more than suburban or rural cab services. App-based dispatch services face variable conditions across shifting territories.
 Chauffeur Experience and Licensing
Chauffeurs with 5+ years of for-hire experience earn 10% to 20% lower premiums than new hackney operators. Clean MVR records (no accidents or violations in 3 years) qualify for preferred rates. Each at-fault accident adds 20% to 40% to your premium for 3 to 5 years.
 Hours of Operation
Late-night and overnight metered fare operations (10 PM to 6 AM) pay 20% to 35% higher premiums than daytime-only services. Weekend bar-close shifts add 10% to 15% due to increased impaired driver exposure. 24/7 hackney services pay the highest rates but can negotiate volume discounts with 5+ cabs.
 Fleet Size and Business Structure
Single-vehicle independent operators pay the highest per-unit rates. Fleets of 2 to 4 medallions save 5% to 10% through multi-vehicle discounts. Dispatch companies with 5 to 10 cabs qualify for fleet pricing with 15% to 25% savings.
 Annual Mileage and Trip Volume
Full-time hackney operators driving 50,000+ miles annually pay 25% to 40% more than part-time drivers logging 20,000 miles. Carriers may request odometer readings or telematics data to verify mileage. High fare volume with frequent passenger pickups increases risk in congested urban zones.
 Claims History and Loss Runs
Zero claims earns 10% to 15% claims-free discounts. One at-fault passenger injury claim adds 15% to 25% to premiums. Two or more claims in 3 years can increase rates 30% to 50% or trigger non-renewal.
 Vehicle Age, Value and Safety Equipment
Newer cabs cost more to insure due to higher replacement values but may qualify for safety discounts. Vehicles over 10 years old have lower physical damage premiums but may exceed TLC age limits. Dashcams reduce premiums 5% to 15%; GPS tracking and telematics earn 10% to 20% discounts.
Commercial Taxi Insurance Requirements
Commercial auto insurance requirements for taxis fall under state and local regulation, not federal FMCSA jurisdiction. Hackney carriages transporting fare-paying passengers operate under city and state taxi and limousine commission (TLC) rules. Check the tables below for your state's minimums before purchasing coverage.
Coverage Types Required for For-Hire Taxi Operations
Commercial Auto Liability | Bodily injury and property damage to third parties including fare-paying passengers | $100,000 to $500,000 CSL or 100/300/100 split | All states, TLC commissions |
Hired and Non-Owned Auto | Liability for rented or borrowed cabs used in metered fare operations | Match primary limits | Many taxi commissions |
Physical Damage (Collision) | Damage to your cab from accidents | Actual cash value | Lenders if financed |
Physical Damage (Comprehensive) | Theft, fire, vandalism, weather damage to your hackney vehicle | Actual cash value | Lenders if financed |
Uninsured/Underinsured Motorist | Protection when at-fault driver lacks coverage for passenger injuries | $25,000 to $100,000 | 22 states require UM/UIM |
Personal Injury Protection (PIP) | Medical expenses, lost wages regardless of fault for chauffeur and riders | $10,000 to $50,000 | 12 no-fault states |
Medical Payments (MedPay) | Medical expenses for chauffeur and fare-paying passengers | $1,000 to $10,000 | Some states, recommended |
Hackney Carriage Licensing and Insurance Requirements
Requirement | Details |
|---|---|
State Liability Minimums | California: City-regulated, typically $750,000 CSL for livery vehicles. New York: $100,000+ per person (NYC TLC requires higher for medallion cabs). Florida: County varies, typically 100/300/50 to $300,000 CSL. Texas: City varies, $500,000 common for metered fare operations. Illinois: $350,000+ (Chicago specific rules for hackney permits). Arizona: $250,000 with UM required. Nevada: 250/500/50 (gaming commission regulated for casino ground transportation). |
Taxi Medallion or Hackney Permit | Most cities require a taxi medallion, hackney badge or livery permit to operate legally. NYC medallions historically cost $1 million+ (now $80,000 to $200,000 post-TNC disruption). Other cities charge $500 to $5,000 for permits. Proof of for-hire insurance required before permit issuance. |
Taximeter Certification | Taximeters must be inspected and sealed by city weights and measures departments. Annual or biannual certification required. Metered fare rates set by local taxi and limousine commission. Tampering results in permit revocation. |
Vehicle Inspection | Annual or semi-annual safety inspections required for hackney carriages. Some cities mandate specific vehicle age limits (5 to 10 years maximum). Wheelchair accessibility and paratransit requirements in some jurisdictions. Roof light and livery markings inspected. |
Chauffeur Licensing | Standard driver's license (no CDL required for vehicles under 26,001 lbs with 1 to 7 passengers). Chauffeur's license, hackney badge or TLC driver permit required in most cities. Background check and fingerprinting mandatory. Drug testing in many jurisdictions. English proficiency and geographic knowledge tests in some markets. |
Insurance Filing Requirements | Certificate of Insurance (COI) filed with taxi and limousine commission. 30-day cancellation notice to TLC required. Some cities require specific endorsements naming the city as certificate holder. Policy must remain active for medallion or hackney permit validity. |
UM/UIM Requirements by State | Required in 22 states: Arizona, California, Connecticut, Illinois, Kansas, Maine, Maryland, Massachusetts, Minnesota, Missouri, Nebraska, New Jersey, New York, North Dakota, Oregon, Rhode Island, South Carolina, South Dakota, Vermont, Virginia, West Virginia, Wisconsin. Limits vary from $25,000 to matching liability limits. |
PIP/No-Fault Requirements | Required in 12 states: Delaware, Florida, Hawaii, Kansas, Kentucky, Maryland, Massachusetts, Michigan, Minnesota, New Jersey, New York, Utah. Coverage ranges $10,000 to $50,000. Pays medical expenses regardless of fault for chauffeur and passengers. |
Airport Ground Transportation Authority | Separate permits required for airport curbside pickups in most cities. Additional insurance requirements common (often $1 million+ CSL for airport livery). Background checks and vehicle inspections specific to airport operations. Annual ground transportation fees range $500 to $2,000. Queue permits and staging area access fees apply. |
Disclaimer
Taxi insurance requirements are regulated at the state and local level. Verify current requirements with your city's taxi and limousine commission (TLC), state insurance department and local business licensing office.
How To Get The Best Cheap Commercial Taxi Insurance
Follow these five steps to cut taxi cab insurance costs 25% to 40% while maintaining proper for-hire coverage.
- 1Compare Quotes From Multiple Insurers
Contact Progressive Commercial, The Hartford and Nationwide, plus one specialty for-hire livery insurer. Get quotes 30 to 45 days before your medallion renewal for better rates. Compare quotes using identical coverage limits (100/300/100 liability with $1,000 deductible) to get an accurate picture.
- 2Verify Coverage Meets TLC Requirements
Call your city's TLC to confirm current liability minimums, usually $100,000 to $500,000 CSL for hackney carriages. Check whether your state requires UM/UIM and PIP coverage. Get a Certificate of Insurance (COI) to file with your taxi commission before renewing your medallion.
- 3Lower Your Insurance Risk
Put dashcams in all cabs to cut premiums 5% to 15%. Add GPS tracking for 10% to 20% off. Make all chauffeurs take defensive driving courses. Hire only operators with clean MVR records. Keep detailed vehicle maintenance records for underwriting reviews.
- 4Stack Available Discounts
Bundle commercial taxi insurance with general liability to save 15% to 20%. Pay annually to avoid monthly installment fees. You get multi-vehicle discounts with two or more medallions. Keep a clean claims record for better rates.
- 5Review Your Policy Every Year
Get new quotes 30 to 45 days before your medallion renews and compare them to your current rate. Update your policy when you add or remove cabs. Ask about new discounts like telematics or hackney industry associations at each renewal.
Commercial Taxi Insurance for Small Business: Bottom Line
Progressive Commercial offers the cheapest commercial taxi insurance at $882 monthly, saving $70 versus the $952 industry average. Your state determines the biggest price difference: Maine hackney operators pay $643 monthly while New York medallion holders pay $1,544. Compare quotes from Progressive Commercial, The Hartford and one additional carrier to find your lowest rate.
Commercial Taxi Insurance for Small Businesses: FAQ
Here are answers to the most common questions taxi operators ask about coverage and costs:
Commercial taxi insurance averages $952 monthly ($11,424 annually) for 100/300/100 liability with $1,000 deductible. Costs range from $643 monthly in Maine to $1,544 in New York. Progressive Commercial offers the lowest rates at $882 monthly. Your premium depends on service territory, chauffeur records and claims history.
Taxi cab insurance covers bodily injury and property damage liability when your chauffeur causes an accident involving fare-paying passengers. Standard policies include collision coverage, comprehensive coverage for theft and hired/non-owned auto for temporary vehicles. Optional add-ons include uninsured motorist protection and medical payments.
Yes. Taxi cab insurance costs $531 monthly more than personal auto coverage on average. Hackney carriages drive 50,000+ miles annually versus 12,000 to 15,000 personal miles and operate in congested urban areas. For-hire passenger transport creates injury liability that personal policies exclude.
Yes. Every state requires commercial auto insurance for for-hire livery vehicles. Personal auto policies exclude business use and deny claims if you transport fare-paying passengers. Operating a cab without commercial coverage results in fines up to $10,000, medallion revocation and personal liability. Most TLCs require proof of hackney insurance before issuing your permit.
Compare quotes from at least three carriers to find rates $70 to $223 below average. Progressive Commercial, The Hartford and Nationwide offer the lowest taxi premiums nationally. Raise your collision deductible to $1,000 to save $100 to $150 monthly. Bundle with general liability for 15% to 20% discounts.
About Mark Flores

Mark Flores is a Business Insurance Content Writer at MoneyGeek, where he focuses on commercial auto, commercial property, cyber and specialty business insurance coverage. His work simplifies coverage terms, gives business owners a strong baseline for expected costs, and narrows down policies and providers tailored to your operation, regardless of complexity.
Before joining MoneyGeek’s business insurance team, Mark worked as a Senior Content Writer at Clutch.co, where he produced structured B2B reviews and provider analyses based on client interviews, company research and service evaluation. That experience shaped his approach to business insurance content, especially when comparing insurers, explaining coverage differences and translating complex policy features into practical guidance for small business owners.
Mark also spent nearly 4 years as a digital marketing specialist serving small-business clients across industries such as home services, manufacturing and education. That background gives him practical context for how businesses evaluate vendors, manage operational needs and make purchasing decisions.
At MoneyGeek, he applies this research and evaluation experience to build guides that help transportation sectors, those with complex property-related risks (such as hotels and retail stores), and those most at risk of a cyberattack get the coverage they need at a reasonable price.
Linkedin: https://www.linkedin.com/in/mark-jason-flores-7844634a/
Contact Email: mark.flores@moneygeek.com