

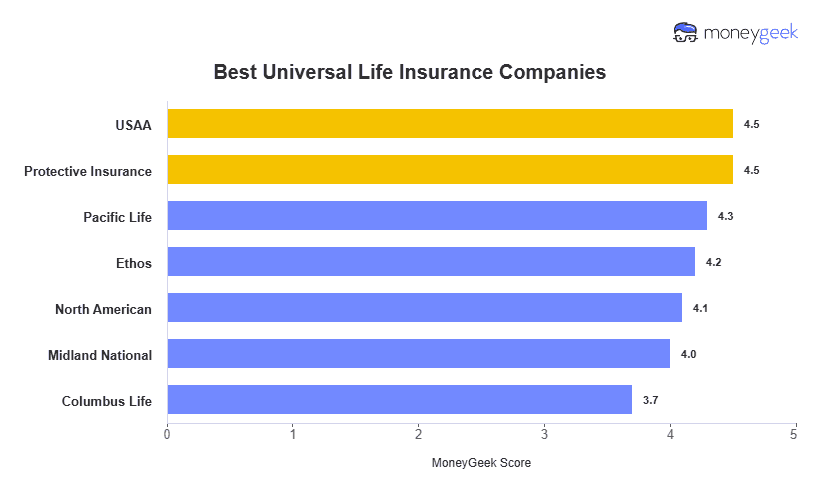
USAA is the best universal life insurance company overall based on its combination of pricing, coverage options, financial strength and customer experience. Protective has the lowest rates across most ages we reviewed, while Ethos leads for indexed universal life insurance, and North American is our top pick for seniors.
Best Universal Life Insurance Companies (2026)
USAA is the best universal life insurance company overall, while Protective has the lowest rates in our analysis. Pacific Life is our top pick for people in poor health, and Ethos leads for indexed universal life with no-exam underwriting.
Compare universal life insurance rates from top providers.
Select age group
Updated: October 2, 2026
Advertising & Editorial Disclosure
Key Takeaways
USAA is the best universal life insurance company overall, combining an A++ AM Best financial strength rating, a low 0.12 NAIC complaint index and a broad range of rider options.
Protective Life has the lowest universal life insurance rates in our analysis across most age groups, averaging $251 per month for a 40-year-old woman and $292 for a man purchasing a $500,000 policy.
Universal life insurance rates increase with age. A 20-year-old woman pays $124 per month with Protective for $500,000 in coverage, compared with $600 at age 60. That's a 384% increase. Carrier pricing differences also widen at older ages, so comparison shopping is important.
Universal life insurance policies require active management. Underfunding your policy or earning lower-than-expected credited interest can increase the amount you need to pay later or cause the policy to lapse. Ask for an illustration showing guaranteed values before you buy.
Best Universal Life Insurance Companies
Why You Can Trust Our Rankings
MoneyGeek evaluated 20 universal life insurance companies using thousands of quotes, financial strength data, customer experience metrics and policy details. We scored insurers across three factors:
- Affordability (50%): Premiums across ages, health profiles, tobacco status and coverage amounts.
- Customer Experience (30%): Complaint data, financial strength, customer satisfaction and the application experience.
- Coverage Options (20%): Policy types, coverage limits, issue ages, riders and other benefits.
Our scores are editorially independent and are not influenced by our partners. Read more in our full Life Insurance Methodology.
Overall | USAA | $300 (Female), $310 (Male) | $10 million | 0-90 | 4.5 |
Cheapest | Protective Insurance | $251 (Female), $292 (Male) | $50 million | 18-85 | 4.5 |
Poor Health | Pacific Life | $265 (Female), $307 (Male) | $10 million | 0-79 | 4.3 |
Indexed Universal | Ethos | $267 (Female), $326 (Male) | $1 million | 20-65 | 4.2 |
Seniors | North American | $269 (Female), $314 (Male) | $5 million | 0-85 | 4.1 |
Flexible Premium Options | Midland National | $269 (Female), $313 (Male) | $10 million | 0-85 | 4 |
Survivorship Universal Life | Columbus Life | $300 (Female), $363 (Male) | $1 million | 0-79 | 3.7 |
* Rates shown are for 40-year-old nonsmokers with average weight and health ratings purchasing a $500,000 policy. Actual premiums will vary depending on your individual profile, health status, coverage needs and insurer underwriting guidelines.
USAA
Best Overall
MoneyGeek Rating
4.5/ 5
4.7/5Affordability
3.9/5Customer Experience
4.8/5Coverage
Average Monthly Rate
$300 (Female), $310 (Male)Max Coverage
$10 millionAges
0-90

Protective
Cheapest Universal Life Insurance
MoneyGeek Rating
4.5/ 5
5/5Affordability
3.5/5Customer Experience
4.5/5Coverage
Average Monthly Rate
$251 (Female), $292 (Male)Max Coverage
$50 millionAges
18-85

Pacific Life
Best for Poor Health
MoneyGeek Rating
4.3/ 5
4.4/5Affordability
3.6/5Customer Experience
4.8/5Coverage
Average Monthly Rate
$265 (Female), $307 (Male)Max Coverage
$10 millionAges
0-79

Ethos
Best Indexed Universal Life Insurance
MoneyGeek Rating
4.2/ 5
3.6/5Affordability
5/5Customer Experience
5/5Coverage
Average Monthly Rate
$267 (Female), $326 (Male)Max Coverage
$1 millionAges
20-65
North American
Best for Seniors
MoneyGeek Rating
4.1/ 5
4.1/5Affordability
3.7/5Customer Experience
4.6/5Coverage
Average Monthly Rate
$269 (Female), $314 (Male)Max Coverage
$5 millionAges
0-85

Midland National
Best for Flexible Premium Options
MoneyGeek Rating
4.0/ 5
3.9/5Affordability
3.9/5Customer Experience
4.4/5Coverage
Average Monthly Rate
$269 (Female), $313 (Male)Max Coverage
$10 millionAges
0-85
Columbus
Best for Survivorship Universal Life
MoneyGeek Rating
3.7/ 5
3.6/5Affordability
3.6/5Customer Experience
4.3/5Coverage
Average Monthly Rate
$300 (Female), $363 (Male)Max Coverage
$1 millionAges
0-79
How Does Universal Life Insurance Work?
Universal life insurance is a permanent policy that combines a death benefit with a cash value savings component. Unlike term life, it doesn't expire after a set period. Unlike whole life, premiums and death benefits are adjustable, which gives you flexibility but also requires active management. If premiums are underfunded or credited interest underperforms projections, the policy can lapse, sometimes decades after purchase.

TYPES OF UNIVERSAL LIFE INSURANCE
- Traditional universal life: Earns interest based on rates set by the insurer and lets you adjust premiums and the death benefit.
- Indexed universal life insurance (IUL): Credits interest based partly on the performance of a market index, subject to caps, participation rates and floors.
- Variable universal life (VUL): Lets you invest cash value in market-based subaccounts. This creates greater growth potential and greater investment risk.
- Guaranteed universal life (GUL): Gives lifetime coverage with guaranteed premiums and minimal cash value. GUL carries the lowest lapse risk of the four types because the death benefit guarantee doesn't depend on cash value performance.
How to Choose the Best Universal Life Insurance Policy
Choose a universal life insurance policy by weighing cost, flexibility and long-term value. Focus on these factors when comparing providers and policies.
- Financial strength ratings: Because you may hold the policy for decades, consider the insurer’s long-term financial strength. Look for carriers with AM Best ratings of A or higher. All seven carriers on our list meet this standard, ranging from A (Excellent) to A++ (Superior).
- Premium flexibility tradeoff: Lower premiums today can leave you with a smaller cash value buffer later. If you minimize premiums in early years and credited interest underperforms projections, you may need to pay more in later years to keep your policy from lapsing. Consider funding the policy with a buffer. Compare quotes from at least three insurers to find low rates.
- Policy illustrations: Ask every carrier for a 20-year and 40-year illustration before buying. These projections show how your cash value and death benefit hold up at the guaranteed crediting rate, not just the current rate. An IUL that looks strong at current returns may look very different at the guaranteed minimum. Compare guaranteed values, not just current projections.
- Cost of insurance (COI) escalation: COI charges increase every year as you age. In the early decades, this may be manageable, but by your 70s and 80s, COI can consume most of your cash value if the policy isn't well-funded. Ask carriers how COI is structured and when it accelerates most sharply.
- Cash value growth: For traditional UL, compare credited interest rates and minimum guarantees. For IUL, compare the participation rate, cap rate and floor rate, not just the headline participation percentage. A 125% participation rate with a low cap may outperform a 100% participation rate with no cap in flat or moderate markets.
- Rider availability: Check whether the policy includes an accelerated death benefit rider, which lets you access a portion of the death benefit if you're diagnosed with a terminal illness. Chronic illness riders and guaranteed insurability options are worth adding if you expect your health to change. Not all life insurance riders are available on all policy types, so confirm before applying.
How Much Does Universal Life Insurance Cost?
Universal life insurance costs increase with age and vary considerably between insurers. A 40-year-old woman pays $251 per month with Protective for a $500,000 universal policy compared with $600 at age 60, a 139% increase. For men, the same policy rises from $292 to $709, a 143% increase.
Carrier rate differences also widen with age. Among the companies in our list, the gap between the lowest and highest monthly rate for women is $76 at age 20 and $223 at age 60. Over 20 years, that adds up to a difference of $18,240 for a 20-year-old and $53,520 for a 60-year-old.
USAA | $185 (F), $190 (M) | $300 (F), $310 (M) | $835 (F), $851 (M) | $1,275 (F), $1,431 (M) |
Protective Insurance | $124 (F), $148 (M) | $251 (F), $292 (M) | $600 (F), $709 (M) | $1,156 (F), $1,459 (M) |
Pacific Life | $135 (F), $158 (M) | $265 (F), $307 (M) | $673 (F), $790 (M) | N/A |
Ethos | $109 (F), $131 (M) | $267 (F), $326 (M) | $823 (F), $994 (M) | N/A |
North American | $127 (F), $152 (M) | $269 (F), $314 (M) | $715 (F), $868 (M) | $1,150 (F), $1,310 (M) |
Midland National | $127 (F), $152 (M) | $269 (F), $313 (M) | $715 (F), $868 (M) | $1,150 (F), $1,310 (M) |
Columbus Life | $135 (F), $157 (M) | $300 (F), $363 (M) | N/A | N/A |
* For ages 20, 40 and 60, rates shown are for $500,000 in coverage while rates shown for age 80 are for $250,000 in coverage. Note that Columbus only offers up to $250,000 in coverage at age 60. Your rates will vary based on your health profile, age, policy type and underwriting process.
UNIVERSAL LIFE INSURANCE FEES
Universal life insurance costs more than the premium alone. Policy charges are deducted from premium payments or cash value and can greatly affect long-term policy performance.
- Cost of Insurance: Pays for the insurance portion of the policy and increases as you age.
- Administrative Charges: Covers policy maintenance and other insurer expenses.
- Premium Loads: Some insurers deduct a portion of each premium before crediting the remainder to the policy.
- Surrender Charges: May apply if you cancel the policy or withdraw a large amount of cash value during the early years of your policy.
- Rider Charges: Optional benefits can increase policy costs.
- Investment Expenses: Variable universal life policies may include expenses tied to their investment subaccounts.
Review your policy illustration for the specific charges that apply to your contract rather than comparing premiums alone.
Estimate Your Universal Life Insurance Cost
Use our free universal life insurance calculator to estimate monthly premiums by age, gender, tobacco use and coverage amount.
Select Age
Select Gender
Select Coverage Level
Select Smoking Status
Average Monthly Rate—
Select Age
Average Monthly Rate—
Select Gender
Select Coverage Level
Select Smoking Status
Best Universal Life Insurance: Bottom Line
USAA and Protective are the strongest starting points for most people seeking universal life insurance. USAA leads on financial stability with an A++ AM Best rating and a 0.12 NAIC complaint index. Protective undercuts it on price at nearly every age group but has the lowest J.D. Power score on our list at 597.
For buyers in their 60s and beyond, North American and Midland National price later life stages most competitively, both averaging $1,150 per month for 80-year-old women versus $1,275 for USAA on the same coverage.
If you want indexed UL without a medical exam and a fully digital process, Ethos is the only carrier on our list that delivers all three. Confirm your target coverage amount is available at your age before applying.
Before buying a policy, get quotes from at least three carriers and ask each for a 40-year illustration at the guaranteed crediting rate.
Frequently Asked Questions
Have questions about universal life insurance? Our answers help you make the right decision.
Universal life insurance provides lifetime coverage. You get flexibility in the death benefit and premiums, so you build cash value. Some policies include a no-lapse guarantee and minimum interest rate guarantees. Use the cash value to pay premiums, make withdrawals, take out a loan or cash out the policy when you no longer need coverage.
Universal life insurance takes ongoing attention. Premiums and cash value depend on how the policy is funded and how credited interest performs, so ignoring it for long periods can lead to problems. If returns fall short, you may need to add more money to keep coverage in place.
Cash value growth can be slow in the early years and may lag behind other long-term financial options. Without regular check-ins, a policy can quietly drift toward underfunding and eventually lapse.
Universal life insurance is worth it if you fund it consistently and review it every few years. For a pure death benefit at the lowest cost, guaranteed universal life or term life cost less in our analysis. If you want cash value growth with less active monitoring, whole life's fixed structure is a better fit. UL works best for people who want premium flexibility and plan to stay involved in managing the policy.
Yes, you can take a loan against the cash value in your universal life policy, often up to about 90% of the cash surrender value. The loan charges interest around 4% to 8% per year, depending on the insurer.
Any loan balance you don’t repay reduces the death benefit dollar for dollar. If the loan and interest grow too large compared to the remaining cash value, the policy can lapse.
Universal life insurance lets you adjust premium payments and death benefits over time, which gives you flexibility but requires active management to avoid lapse. Whole life insurance uses fixed premiums and grows cash value at a guaranteed rate, so it's more predictable but less flexible. If you miss a universal life premium, your cash value absorbs the cost and the policy can eventually lapse. A whole life policy stays in force as long as you pay the fixed premium.
Learn more: Universal vs. Whole Life Insurance
Related Articles





About Patrick Bryant

Patrick Bryant is the Vertical Lead for Life and Health Insurance at MoneyGeek, where he researches insurance products, writes consumer guides and oversees provider scoring methodologies that are reviewed quarterly to reflect current market conditions and carrier data. He has analyzed more than 50 life insurance carriers across multiple policy types and collected thousands of quotes nationwide to compare pricing, coverage and underwriting requirements.