2026 Ethos Life Insurance Review: Rates, Pros & Cons


Ethos is an online life insurance broker that connects applicants with policies from its partner carriers. It's a good fit for people who want same-day, no-exam approval. Its indexed universal life rates run 14% to 15% below the national average in our analysis, and every policy includes free estate planning tools. However, its term life premiums run 16% to 48% above average depending on coverage level.

Get a personalized life insurance quote in seconds.

Select age group

At a Glance: Ethos Life Insurance Review

Ethos

Ethos

MoneyGeek Rating
4.2/ 5
4.5/5Affordability
3.9/5Customer Experience
3.9/5Coverage Points
  • Avg. Monthly Rate

    $54 (F), $72 (M)
  • Ages Supported

    20-65 (Term), 20-85 (IUL), 55-80 (Whole), 65-85 (Final Expense)

What Ethos Does Best

Ethos is one of the few online brokers offering indexed universal life insurance without a medical exam. Its IUL rates run 14% to 15% below the national average across all coverage levels. Every IUL policy includes two living benefit riders at no extra cost: the Care4Life Accelerated Death Benefit for critical, chronic and terminal illnesses, and a Lifetime Income Rider that can convert accumulated cash value into retirement income.

Every Ethos policy includes free access to will and living trust creation through its estate planning tools. No other carrier in our analysis includes this benefit. For people who need both life insurance and basic estate planning, Ethos covers both in a single product.

If one carrier declines your application, Ethos automatically routes it to the next best offer in its carrier network rather than issuing an outright denial. This makes Ethos worth trying first for people who aren't sure if they'll qualify elsewhere. The online application takes less than 10 minutes, and most applicants receive a same-day decision.
Ethos Drawbacks

Ethos term life premiums are 16% to 48% above the national average, depending on coverage level and gender. Policyholders who qualify through full underwriting will find lower rates with Banner Life or Transamerica.

Ethos's whole life product is a guaranteed issue final expense policy capped at $25,000, available to applicants ages 55 to 80. It's not a traditional cash-value policy suited for income replacement or long-term wealth building. If you want higher whole life coverage limits or stronger cash value growth, you have better options with USAA, Gerber Life or Protective.

Ethos doesn't have live chat support or a mobile app, which can make policy management after purchase inconvenient. Coverage is also unavailable in New York, and the carrier does not have traditional or variable universal life insurance will need to consider another provider.

Ethos Life Insurance Policy Options

Ethos offers term life insurance, guaranteed whole life (final expense) and indexed universal life insurance. Policies are issued through one of several carrier partners, including Ameritas, Banner Life, Protective Life, TruStage, North American and Aflac. Applicants don't choose their carrier. Instead, Ethos assigns one based on your eligibility and responses to the health questionnaire.

Ethos Term Life Insurance

  • Max coverage: $3 million (ages 20-50), $500,000 (ages 51-75)
  • No-exam policy: Yes (simplified issue)
  • Terms lengths: 10, 15, 20, 30 years
  • Ages supported: 20-65
  • Average monthly premium: $54 (women), $72 (men) for a 20-year, $500,000 policy
  • Application decision: Usually within minutes

Ethos term life insurance is a good fit for people who want fast, no-exam coverage without a lengthy underwriting process. Ethos pulls third-party data from MIB Group records, motor vehicle records and prescription databases to verify your health questionnaire responses, so most applicants don't need an in-person exam. Rates run higher than the national average in our analysis, but the tradeoff is a faster application and no medical exam.

If you qualify for lower rates or need higher coverage limits, you can also apply for a fully underwritten policy through one of Ethos' carrier partners, with approval taking one to four weeks. Every policy includes a 30-day money-back guarantee, no cancellation fees and free will and estate planning tools.

Ethos Guaranteed Whole Life Insurance

  • Max coverage: $25,000
  • No-exam policy: Yes (guaranteed, with no exam or health questions required)
  • Ages supported: 55-80
  • Average monthly premium: $112 (woman), $127 (man) for a $15,000 policy at 65 years old
  • Graded death benefit: Yes, two years
  • Application decision: Usually within minutes

Ethos guaranteed whole life insurance is designed for seniors who may not qualify for traditional coverage because of their age or health. Available to applicants ages 55 to 80, these policies provide up to $25,000 in permanent coverage. They're best suited for final expenses like funeral costs, medical bills or other end-of-life expenses. Approval is guaranteed, with no medical exam or health questions, and most applicants receive a decision within minutes.

Like most guaranteed issue policies, Ethos includes a two-year graded death benefit. If the insured dies from natural causes during the first two years, beneficiaries receive the premiums paid plus interest instead of the full death benefit. After the waiting period, the full benefit is paid for all covered causes of death. Premiums remain level for life, coverage begins after your first payment and every policy includes a 30-day money-back guarantee.

Ethos Indexed Universal Life Insurance

  • Max coverage: $1 million
  • No-exam policy: Yes (simplified issue))
  • Ages supported: 20-85
  • Average monthly premium: $54 (woman), $72 (man) for a $500,000 policy at 40 years old
  • Application decision: Usually within minutes
  • Included riders: Care4Life Accelerated Death Benefit and Lifetime Income rider
  • Optional riders: Accidental death and disability

Ethos indexed universal life (IUL) insurance is a good option if you want permanent coverage with the potential to build cash value. Unlike term life insurance, IUL doesn't expire as long as your policy stays in force, and it allows you to adjust your premium payments within policy guidelines as your financial needs change. Based on our rate analysis, Ethos IUL policies cost 14% to 15% less than the national average across all coverage levels, the company's most competitively priced product.

Applicants ages 20 to 85 can qualify online without a medical exam by answering health and lifestyle questions. You can allocate cash value among nine market index options while benefiting from caps and floors that help limit downside risk. Every policy includes the Care4Life Accelerated Death Benefit rider for critical, chronic and terminal illness, along with a Lifetime Income rider that can convert accumulated cash value into retirement income. You can also borrow or withdraw from the policy's cash value, though doing so reduces the death benefit and may cause your policy to lapse if the remaining cash value becomes too low.

Ethos’s Life Insurance Riders

Life insurance riders are extra benefits you can add to a policy to fill gaps or give your loved ones more financial stability. Ethos keeps its rider options limited by design, prioritizing straightforward coverage. Available riders include:

Accelerated Death Benefit
Lets policyholders access part of the death benefit early if diagnosed with a terminal illness.
Care4Life Accelerated Death Benefit
Expands early access to the death benefit for critical, chronic or terminal illness.
Lifetime Income Rider
Converts accumulated policy value into a stream of retirement income later in life.
Accidental Death Benefit Rider
Pays an additional benefit if the insured dies from a covered accident.
Waiver of Premium
Waives premium payments if the insured becomes totally disabled. Available on select policies for an additional cost.
Return of Premium
Refunds premiums paid if the insured outlives the term. Available on select 25- and 30-year term policies.
Child Term Rider
Provides term life coverage for the insured's children up to age 25. Available on select term policies for an additional cost.

Guaranteed Insurability

Buy additional coverage at certain life events, such as marriage or the birth of a child, without a medical exam.

Long-Term Care

Use a portion of your death benefit to pay for long-term care expenses. The death benefit is reduced by any amount accessed.

Ethos Life Insurance Cost

We pulled thousands of life insurance quotes from more than 30 companies based on age, health classification, tobacco use, coverage amount and policy type. Ethos rates run above the national average for term and guaranteed whole life but are 14% to 15% below average for IUL policies.

Ethos sets premiums based on your age, gender, coverage amount, term length, health class, tobacco use, ZIP code and credit history. Its simplified underwriting process also uses MIB records, motor vehicle reports, family medical history and prescription data to verify your application. Your final rate is determined without a medical exam.

Ethos Term Life Rates

Ethos term life insurance rates run 16% to 48% above the national average depending on coverage level and gender. If keeping monthly costs low is your priority, Banner Life and Transamerica have more competitive term rates for healthy applicants willing to go through full underwriting.

Term Life Rates by Coverage

$100,000
$21

+$5 (32%)

$28

+$9 (47%)

$250,000
$36

+$8 (28%)

$48

+$13 (38%)

$500,000
$54

+$8 (16%)

$72

+$13 (22%)

$750,000
$95

+$28 (41%)

$126

+$41 (48%)

$1,000,000
$120

+$33 (39%)

$159

+$49 (45%)

* Rates based on 40-year-old nonsmokers with average health on a 20-year term policy.

Term Life Rates by Age

20
$31
+$1 (+3%)
$42
+$6 (+16%)
30
$32
+$1 (+5%)
$43
+$6 (+16%)
40
$54
+$8 (+16%)
$72
+$13 (+22%)
50
$127
+$25 (+24%)
$166
+$29 (+21%)
60
$359
+$72 (+25%)
$510
+$115 (+29%)

* Rates based on nonsmokers in average health with a 20-year, $500,000 term policy.

Ethos IUL Rates

Ethos IUL rates run consistently 14% to 15% below the national average across every coverage level for both genders. That discount holds regardless of whether you're buying $100,000 or $1 million in coverage. If you're interested in an IUL policy, Ethos is among the more affordable options in our analysis.

$100,000
$48
-$8 (-15%)
$59
-$9 (-14%)
$250,000
$121
-$21 (-15%)
$147
-$23 (-14%)
$500,000
$242
-$42 (-15%)
$295
-$46 (-14%)
$750,000
$363
-$63 (-15%)
$442
-$69 (-14%)
$1,000,000
$484
-$84 (-15%)
$590
-$92 (-14%)

* Rates shown are for 40-year-old nonsmokers in average health.

Ethos Guaranteed Life Insurance Rates

Ethos guaranteed whole life rates run 4% to 24% above the national average, with the gap widest at the $15,000 and $20,000 coverage levels. For seniors comparing final expense options, Physicians Mutual and Gerber Life have lower rates at comparable coverage amounts, though Ethos's 30-day money-back guarantee and free estate planning tools are differentiators neither of those carriers includes.

$5,000
$37

+$6 (17%)

$42

+$2 (4%)

$10,000
$67

+$7 (11%)

$93

+$13 (17%)

$15,000
$112

+$22 (24%)

$127

+$10 (9%)

$20,000
$149

+$29 (24%)

$169

+$13 (8%)

$25,000
$183

+$34 (23%)

$215

+$20 (10%)

* Rates shown are for 65-year-old nonsmokers.

Ethos Customer Experience

  • Consumer complaints: Ethos's carrier partners collectively receive fewer complaints than the industry average, per NAIC data. Banner Life holds a complaint index of 0.16, TruStage 0.62 and Ameritas 1.5. A ratio below 1.0 means fewer complaints than expected for a company of that size.
  • Review forums: Ethos holds a 4.9 out of 5 Trustpilot rating. Most reviewers praise the application process, though some report dissatisfaction with pricing and post-application communication. Because claims are processed by carrier partners, not Ethos directly, the post-claim experience depends on which carrier underwrites your policy.
  • Financial strength: Ethos's partner carriers collectively hold AM Best ratings of A (Excellent) or higher, which means they're financially positioned to pay future claims.
ethos life insurance application
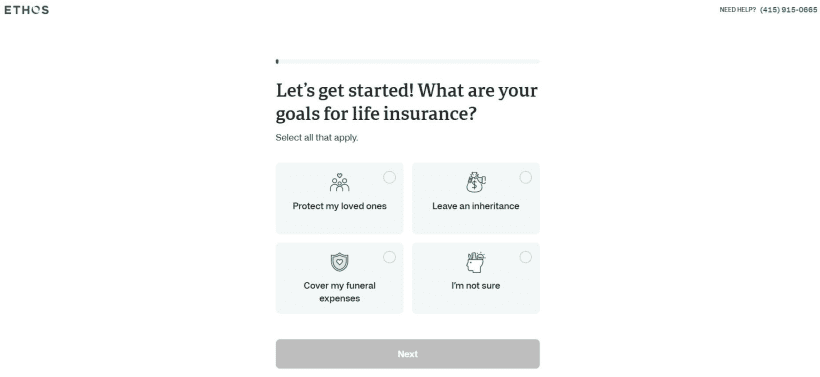
  • Application process: We found the online application process to be straightforward, completing it in under 10 minutes without a medical exam. Its approval process automatically moves you to the next best option if you're declined by one carrier, helping to prevent outright denials.
  • Customer support: You can reach Ethos by phone at 415-915-0665 or by email at support@ethoslife.com. Customer service hours are 8 a.m. to 6 p.m. CT.
mglogo icon
OUR EXPERIENCE WITH ETHOS CUSTOMER SERVICE

We called Ethos customer service during business hours and reached a representative within one minute. The agent politely answered our questions about coverage limits and how the Care4Life Accelerated Death Benefit applies to chronic illness claims. Ethos offers support only by phone and email at support@ethoslife.com, with no live chat or mobile app.

How to Get Ethos Life Insurance

Ethos runs a fully online application with no agent required. You can also apply by phone at 415-915-0665 if you'd prefer to speak with someone during the process. Most applicants get a decision the same day, and coverage starts after the first payment. The process is straightforward:

  1. 1
    Review your coverage needs

    Ethos asks about your financial dependents, outstanding debts and estate plan during the application, then recommends a policy length and coverage amount. You can use an in-app sliding scale to adjust the suggested coverage amount and compare quotes before moving forward. Knowing your budget upfront speeds up the process.

  2. 2
    Get an online quote

    Enter your age, health details and coverage amount on the Ethos website to generate an instant life insurance quote. The quote tool shows you options based on your profile.

  3. 3
    Complete the application and health questionnaire

    Answer health and lifestyle questions online. Most applicants won’t need a medical exam. Depending on your responses, Ethos may ask follow-up questions or require full underwriting, which can add a few days to the process.

  4. 4
    Review your approval and activate coverage

    Most simplified-issue applicants receive same-day approval. Once approved, review your policy documents, confirm any optional riders and submit your first payment. Coverage begins immediately after payment is processed.

Ethos Life Insurance vs. Other Insurers

Ethos
Indexed Universal Life (IUL) Insurance
Term, IUL, Guaranteed Whole, Final Expense
$54 (F), $72 (M)
A+
4.2
Banner Life
Term Life Insurance
Term, Universal
$37 (F), $46 (M)
A+
4.5
Nationwide
No-Exam Life Insurance
Term, Whole, Universal, IUL
$45 (F), $56 (M)
A+
4.5
USAA
Whole & Universal Life Insurance
Term, Whole, Universal, IUL
$38 (F), $48 (M)
A++
4.7
Transamerica
Final Expense Insurance
Term, Whole, Final Expense
$37 (F), $46 (M)
A
4.5

Ethos ranks as MoneyGeek's top pick for indexed universal life insurance based on three factors: a no-exam application with coverage up to $1 million, built-in living benefit riders at no extra cost and IUL rates that run 14% to 15% below the national average. No other carrier in our comparison combines all three in a single product.

For term life, Ethos isn't the most competitive option on price. Among the 21 term life insurance companies we analyzed, Ethos ranked as the second-most expensive for both men and women.

For whole life policies, USAA, Gerber Life and Protective have higher coverage limits and stronger cash value structures than Ethos's $25,000 guaranteed whole life maximum. Ethos's whole life product works best as a final expense solution for people ages 55 to 80, not as a primary wealth-building vehicle.

Is Ethos Right For You?

Ethos life insurance works well for specific buyer profiles and isn't the right fit for others:

  • Consider Ethos if you want IUL coverage without a medical exam. Ethos is one of the few online brokers offering indexed universal life through simplified issue underwriting. Rates are 14% to 15% below the national average, and living benefit riders are included at no extra cost. No other provider in our comparison combines all three.
  • Consider Ethos if you want life insurance and estate planning in one place. Every Ethos policy includes free access to will and living trust creation, a benefit no other provider in our analysis provides at no additional cost.
  • Consider Ethos if you're unsure whether you'll qualify. If one carrier declines your application, Ethos can route it to another carrier in its network instead of ending the process.
  • Consider Ethos if you're a senior looking for final expense coverage. Its guaranteed whole life policy serves applicants ages 55 to 80 with up to $25,000 in permanent coverage without health-based approval requirements. A 30-day money-back guarantee and free estate planning tools add value at comparable coverage levels.
  • Consider a competitor if your priority is the lowest term life rate. Ethos term premiums run 16% to 48% above the national average in our analysis.
Compare Life Insurance Rates

Ensure you're getting the best rate for your insurance. Compare quotes from the top insurance companies.

Ethos Insurance Reviews: FAQ

MoneyGeek scored Ethos using rate data for our baseline profile of a 40-year-old male nonsmoker in average health seeking $500,000 in coverage on a 20-year term. The MoneyGeek Score weights affordability at 50%, customer experience at 30% and coverage options at 20%. Customer experience ratings draw from customer reviews, J.D. Power life insurance study scores, AM Best financial strength ratings and NAIC complaint indexes.

Learn more: MoneyGeek Life Insurance Review Methodology

More Life Insurance Reviews

About Patrick Bryant


Patrick Bryant, Vertical Lead, Life & Health Insurance, MoneyGeek

Patrick Bryant is the Vertical Lead for Life and Health Insurance at MoneyGeek, where he researches insurance products, writes consumer guides and maintains the scoring methodologies behind our provider comparisons. He analyzed more than 50 life insurance carriers across multiple policy types, collecting thousands of quotes nationwide to evaluate rates, coverage options and underwriting factors. His methodologies are reviewed quarterly to reflect current market conditions and carrier data.