

Missouri homeowners pay rates below the national average. MoneyGeek analyzed premiums, J.D. Power satisfaction scores and coverage options from major insurers to find the best home insurance companies in Missouri.
Best Homeowners Insurance Companies in Missouri
Updated: September 11, 2026
Advertising & Editorial Disclosure
Missouri's Top Home Insurance Companies: Key Takeaways
AAA is the best home insurance provider in Missouri with a score of 4.6 out of 5 from our review team.
USAA, State Farm, American Family and Nationwide rank high for homeowners insurance in Missouri based on affordable rates, strong customer service and reliable coverage.
The best insurer for your home depends on your coverage needs, budget and preferred features like claims service or discount availability.
What Are the Best Home Insurance Companies in Missouri?
AAA ranks first for Missouri homeowners with the state's lowest premiums and above-average customer satisfaction. USAA, State Farm, American Family and Nationwide complete the top five, excelling in areas like military-focused service, premium coverage quality and local agent networks.
AAA | 4.6 | $1,617 | Most Missouri homeowners |
USAA | 4.8 | $2,464 | Military families |
State Farm | 4.3 | $2,944 | Customer satisfaction |
American Family | 4.1 | $4,340 | Financial stability |
Nationwide | 4.0 | $2,584 | Digital tools |
*Our ratings consider various combinations of coverage levels, home features and homeowner details to identify the best overall options. Rankings may differ based on your profile.
**Although USAA earned the highest score, we didn't rank it No. 1 due to its eligibility requirements.

AAA
MoneyGeek Rating
4.6/ 5
5/5Affordability
3.8/5Customer Experience
5/5Coverage
J.D. Power Customer Satisfaction Score
N/AFrom the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$1,617Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
USAA
MoneyGeek Rating
4.8/ 5
4.6/5Affordability
5/5Customer Experience
4.9/5Coverage
J.D. Power Customer Satisfaction Score
737/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$2,464Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
State Farm
MoneyGeek Rating
4.3/ 5
4.4/5Affordability
4.3/5Customer Experience
3.7/5Coverage
J.D. Power Customer Satisfaction Score
657/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$2,944Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible

American Family Insurance
MoneyGeek Rating
4.1/ 5
4.1/5Affordability
4.5/5Customer Experience
3.5/5Coverage
J.D. Power Customer Satisfaction Score
643/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$4,340Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible

Nationwide
MoneyGeek Rating
4.0/ 5
4.6/5Affordability
4.2/5Customer Experience
1.7/5Coverage
J.D. Power Customer Satisfaction Score
641/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$2,584Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
Best Missouri Home Insurance by City
AAA is the top provider in 10 cities, including Kansas City, Saint Louis, Columbia, Springfield, Independence, Blue Springs, Branson, Wentzville, Morrisville and Lilbourn. Annual premiums are from $1,282 in Wentzville to $1,825 in Kansas City.
| Blue Springs | AAA | $1,676 |
| Branson | AAA | $1,709 |
| Columbia | AAA | $1,467 |
| Independence | AAA | $1,802 |
| Kansas City | AAA | $1,825 |
| Lilbourn | AAA | $1,437 |
| Morrisville | AAA | $1,716 |
| Saint Louis | AAA | $1,484 |
| Springfield | AAA | $1,692 |
| Wentzville | AAA | $1,282 |
Cheapest Missouri Home Insurance Companies
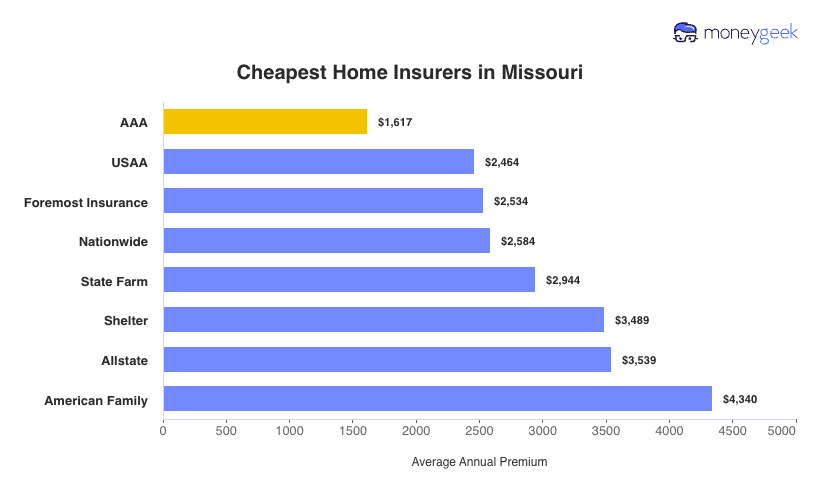
Home insurance in Missouri runs Missouri homeowners pay $2,939 a year, 15% less than the national average of $3,467. At $1,617 a year, AAA offers the state's most affordable home insurance, 45% under the state average. USAA follows at $2,464 a year, available only to military members, veterans and their families. Premium costs vary by insurer: American Family charges 25% more than the national average.
Guide to Finding the Best Missouri Home Insurance Company
Look at providers based on your coverage needs, budget and service preferences.
 Compare Quotes Strategically
Get quotes from at least three to five insurers. Premiums among top Missouri providers range from $1,617 to $4,340 a year. Price alone doesn't tell the full story. The cheapest policy might leave coverage gaps when you file a claim after severe weather or other covered losses.
 Check Customer Satisfaction Metrics
Research complaint ratios through Missouri's Department of Insurance, Financial Institutions and Professional Registration. Then look at J.D. Power scores among leading Missouri insurers, which run from 641 to 737 against the 642 industry average. Recent customer reviews that detail claims handling during tornado season matter more than policy purchase experiences alone.
 Evaluate Coverage Needs
Base your coverage on replacement cost, not market value. That distinction matters in Missouri, where construction costs surge after tornadoes and flooding. Review extended or guaranteed replacement cost options alongside optional protections like wind/hail coverage and flood insurance that address your home's specific weather risks.
 Match Service Preferences to Provider Strengths
State Farm and other insurers with local agent networks suit homeowners who want face-to-face support. USAA and other digital-first insurers suit those who prefer online policy management. Skip paying premium prices for services you won't use.

MISSOURI HOME INSURANCE RISKS
Missouri is among the top states for tornado frequency, according to the National Weather Service. Standard homeowners insurance covers tornado and wind damage to your property, but it doesn't cover flood damage. You'll need separate flood insurance through your insurer or the National Flood Insurance Program.
Top-Rated Home Insurance Companies in Missouri: FAQ
Explore our FAQ section for answers to common questions about selecting the right Missouri home insurance provider for your needs.
Yes, you need separate flood insurance in Missouri. You can purchase flood insurance through your current insurer or the National Flood Insurance Program.
Missouri homeowners pay $2,939 annually for home insurance, which is 15% less than the national average of $3,467.
Replacement cost coverage pays to rebuild your home or replace belongings at current prices. Actual cash value coverage subtracts depreciation from claim payments.
Yes, you can get home insurance with a trampoline or swimming pool, but Missouri insurers consider these features liability risks. Many companies require higher premiums, additional liability coverage or safety equipment like nets and padding for trampolines or fencing with self-closing gates for pools. Some insurers may exclude coverage for these features entirely. Consider securing at least $300,000 in liability coverage to protect against potential accidents.
Our Methodology: Determining the Best Missouri Home Insurers
Missouri homeowners deal with tornado risks, hurricane exposure and fluctuating construction costs. Our ranking system weighs affordable premiums, quality coverage and reliable claims handling.
We scored insurers across three factors:
Affordability (55%): We compared rates for identical coverage across major providers and evaluated discount availability.
Customer satisfaction (30%): J.D. Power ratings, Trustpilot reviews and app feedback reveal how insurers handle claims after storms damage your home.
Coverage options (15%): We assessed add-on availability, including water backup protection and inland flood options for Missouri's risks.
Our Sample Profile
Rates reflect a homeowner aged 41-60 with good credit and no prior claims insuring a 2,500-square-foot home built in 2000. Coverage includes $250,000 dwelling coverage, $125,000 personal property coverage, $200,000 personal liability coverage and a $1,000 deductible.
Your rates will vary based on your home's age, location, claims history and credit score.
About Mark Fitzpatrick

Mark Fitzpatrick is a licensed Property and Casualty (P&C) Insurance Producer in Connecticut and MoneyGeek's resident expert in insurance and economics. In nearly a decade covering the insurance market at LendingTree and MoneyGeek, he's analyzed hundreds of carriers and millions of rates across auto, home, renters, health and life insurance.
His work has appeared in The Washington Post, The New York Times and NPR. He draws on independent cost and consumer experience data, and no insurance company partnerships affect his recommendations.
Mark studied at Boston College and later earned a master's in economics and international relations from Johns Hopkins University. He worked in financial risk management at State Street before joining MoneyGeek. He's also a five-time “Jeopardy!” champion.
Sources
- National Weather Service. "National Weather Service." Accessed September 20, 2026.