Michigan homeowners pay rates well below the national average. MoneyGeek analyzed premiums, J.D. Power satisfaction scores and coverage options from major insurers to find the best home insurance companies in Michigan.
Best Homeowners Insurance Companies in Michigan
Auto-Owners ranks No. 1 in our review of the best home insurance in Michigan, followed by USAA and Chubb.
See if you're overpaying for home insurance below.

Updated: September 15, 2026
Advertising & Editorial Disclosure
Auto-Owners is the best home insurance provider in Michigan with a score of 4.6 out of 5 from our review team.
USAA, Chubb, State Farm and Farmers rank high for homeowners insurance in Michigan based on reliable coverage, positive customer service and affordable rates.
The best insurer for your home depends on your coverage needs, budget and preferred features like claims service or discount availability.
What Are the Best Home Insurance Companies in Michigan?
Auto-Owners earned our top ranking for Michigan homeowners, posting the state's lowest premiums and high customer satisfaction scores. USAA, Chubb, State Farm and Farmers round out the top five. Their strengths include military-focused coverage, competitive pricing and established local networks.
Auto-Owners | 4.6 | $400 | Most Michigan homeowners |
USAA | 4.7 | $1,970 | Military families |
Chubb | 4.5 | $1,808 | Digital management |
State Farm | 4.2 | $1,956 | Local agent network |
Farmers | 4.1 | $2,063 | Specialized coverage |
*Our ratings consider various combinations of coverage levels, home features and homeowner details to identify the best overall options. Rankings may differ based on your profile.
**Although USAA earned the highest score, we didn't rank it No. 1 due to its eligibility requirements.

Auto-Owners
J.D. Power Customer Satisfaction Score
621/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$400Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
- pros
Strong financial stability with high industry ratings
Most affordable rates for Michigan homeowners
Comprehensive coverage options
consSlower claims process
Limited availability in some areas
Gaps in service coverage in some Michigan regions
Auto-Owners charges Michigan homeowners just $400 per year. The insurer stands out for its replacement cost coverage on personal belongings, paying full value rather than depreciated amounts after a loss. Auto-Owners includes water backup coverage in its policies, protecting against basement flooding common throughout Michigan.
Auto-Owners charges $400 annually for home insurance in Michigan, 82% less than the state average of $2,195 and 88% the national average of $3,467. Bundle your home policy with auto insurance to save, or reduce premiums by installing security systems.
Older Homes $35 $414 Newer Homes $30 $364 Young Homeowners $35 $419 Senior Homeowners $32 $381 High-Risk Fire Homes $37 $448 Smaller Homes $34 $413 Larger Homes $39 $464 Auto-Owners scored 621 out of 1,000 points in J.D. Power's study, below the 642-point industry average. The company works through independent agents who provide personalized service and local expertise. Auto-Owners' digital tools lag behind some competitors, which matters if you prefer managing your policy online.
Auto-Owners Insurance provides standard homeowners coverage with optional add-ons:
- Guaranteed home replacement cost: Rebuilds your home even if costs exceed your coverage limit
- Water backup coverage: Pays for damage from backed-up sewers or drains with multiple limit options
- Special personal property: Covers items for loss, misplacement, staining or defacing beyond standard protection
- Ordinance or law: Updates your home to current building codes after covered damage
- Homeowners Plus: Bundles appliance leak coverage, higher food spoilage limits, fungi coverage and inflation protection
- Equipment breakdown: Repairs or replaces failed appliances, HVAC systems and computers
- Identity theft expense: Provides up to $15,000 for financial identity restoration costs
- Home cyber protection: Covers data recovery, device restoration and legal counsel after cyber incidents
- Inland flood: Adds flood coverage for low-to-moderate risk homes, including contents and temporary housing

USAA
J.D. Power Customer Satisfaction Score
737/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$1,970Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
- pros
Excellent financial stability ratings
Multiple add-on coverage options for customization
Military-specific coverages address deployment and relocation needs
consSmaller agent network than major competitors
Membership limited to military community and families
Rates run above state average for Michigan homeowners
USAA charges $1,970 a year for home insurance in Michigan, the lowest rate MoneyGeek found among the state's insurers. Personal property claims pay out at replacement cost: full value, not the depreciated amount. Homeowners who rent through Airbnb or similar platforms get home-sharing coverage, a protection most competitors exclude. Deployments and frequent relocations shape how USAA structures its policies for military families.
USAA's $1,970 annual rate in Michigan comes in 10% below the state average of $2,195 and 37% below the national average of $3,467. Bundling home and auto policies cuts costs further. Installing a security system adds another discount.
Older Homes $169 $2,033 Newer Homes $102 $1,229 Young Homeowners $178 $2,137 Senior Homeowners $162 $1,946 High-Risk Fire Homes $184 $2,207 Smaller Homes $153 $1,839 Larger Homes $176 $2,117 USAA scored 737 out of 1,000 in J.D. Power's study, 95 points above the industry average of 642. USAA works digitally rather than through local agents, putting you in direct contact with representatives trained on deployment schedules, PCS moves and other military-specific situations. Online policy management tools work well. The mobile app lacks some features competitors offer.
USAA builds military-focused enhancements into its standard homeowners coverage:
- Replacement cost coverage: Pays full replacement value for personal property without depreciation
- Home-sharing coverage: Protects you when renting your home through Airbnb or VRBO
- Dwelling protection: Covers your home's structure from fire, wind, hail and other covered events
- Personal liability: Pays legal costs and damages if someone sues for injuries on your property
- Additional living expenses: Covers hotel stays and meals while your home undergoes covered repairs
- Personal property protection: Replaces belongings damaged at home or away from your property

Chubb
J.D. Power Customer Satisfaction Score
677/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$1,808Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
- pros
Flexible coverage options you can adjust to your needs
Independent agents offer local expertise and face-to-face service
Digital platform handles policy changes and payments efficiently
consLimited direct purchase options
Rates run slightly higher
Limited coverage availability
Chubb charges Michigan homeowners $1,808 annually for home insurance. Guaranteed replacement cost coverage rebuilds your home at current construction prices, even when storms damage multiple homes in the same region and push rebuilding costs above your policy limit, a real risk in Michigan's tornado-prone areas. Chubb's coverage limits for jewelry, art and collectibles also run higher than standard endorsements offer.
Chubb's $1,808 annual rate beats Michigan's $2,195 state average by 18% and the $3,467 national average by 37%. Two discounts can lower premiums further: bundling home and auto coverage, and installing a security system.
Older Homes $139 $1,667 Newer Homes $128 $1,537 Young Homeowners $152 $1,827 Senior Homeowners $150 $1,797 High-Risk Fire Homes $169 $2,025 Smaller Homes $156 $1,867 Larger Homes $175 $2,099 Independent agents sell Chubb's Michigan policies, customizing coverage based on local property risks and market conditions. Chubb scored 677 out of 1,000 in J.D. Power's study, ahead of the 642-point industry average. Its online platform lets policyholders manage coverage, file claims and pay bills without contacting their agent.
Chubb builds premium add-ons into its standard homeowners coverage:
- Guaranteed replacement cost: Rebuilds your home at current construction prices, even when costs exceed your coverage limit
- Extended personal property coverage: Insures high-value items like jewelry, art and antiques with higher limits than standard policies
- Dwelling coverage: Pays to repair or rebuild your home after fire, wind, hail or other covered damage
- Personal liability protection: Covers legal costs and damages if someone gets injured on your property
- Additional living expenses: Pays for hotels, meals and other costs while your home undergoes covered repairs
- Customizable policy options: Add earthquake coverage, water backup protection or identity theft coverage based on your needs

State Farm
J.D. Power Customer Satisfaction Score
657/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$1,956Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
- pros
Strong financial stability with high ratings from rating agencies
Customizable coverage options
User-friendly digital tools for policy management and claims processing
consRates run above the Michigan state average for premiums
Some add-on coverages unavailable in certain regions
Coverage gaps in select Michigan areas
State Farm charges Michigan homeowners $1,956 annually for home insurance, the lowest rate MoneyGeek found among the state's insurers. Personal property claims pay out at replacement cost: full value, not the depreciated amount. Ice storms, flooding or other disasters that force you out of your home trigger State Farm's additional living expenses coverage, which pays for hotels and meals. Below-average rates paired with this coverage make State Farm worth comparing.
State Farm's $1,956 annual rate in Michigan runs 11% below the state average of $2,195 and 37% below the national average of $3,467. Bundling your home policy with auto insurance cuts costs further. Installing a security system also reduces premiums.
Older Homes $166 $1,989 Newer Homes $122 $1,468 Young Homeowners $165 $1,977 Senior Homeowners $162 $1,945 High-Risk Fire Homes $183 $2,192 Smaller Homes $168 $2,021 Larger Homes $189 $2,271 J.D. Power gave State Farm 657 out of 1,000 points in its study, 15 points above the 642-point industry average. Local agents who understand Michigan's weather risks and housing market handle policies, or you can buy directly online. The website handles quotes and claims well. The mobile app lacks some features competitors offer.
State Farm builds optional add-ons into its standard homeowners coverage:
- Personal property replacement cost: Pays full replacement value for damaged belongings without subtracting depreciation
- Additional living expenses: Covers hotel stays, meals and other costs when covered damage forces you out of your home
- Dwelling coverage: Pays to repair or rebuild your home after fire, wind, hail or other covered damage
- Personal liability: Covers legal costs and damages if someone gets injured on your property
- Medical payments: Pays medical bills for guests injured at your home, regardless of fault
- Other structures: Covers detached garages, sheds, fences and other structures on your property
Farmers
J.D. Power Customer Satisfaction Score
631/1,000From the J.D. Power 2025 U.S. Home Insurance Study, which examines customer satisfaction based on responses from 14,511 homeowners and renters. The average score is 642/1,000.Average Annual Premium
$2,063Based on our methodology's base profile of a policy with $250K in dwelling coverage, $125K in personal property coverage and $200K in liability coverage with a $1,000 deductible
- pros
Specialized coverage for farms, barns and agricultural equipment
A++ AM Best rating shows strong financial backing
Agricultural endorsements most standard insurers don't offer
consJ.D. Power score falls 11 points below industry average
Coverage unavailable in many Michigan regions
Premiums exceed state average
Many home insurance policies exclude sewer and drain backup coverage, a common source of Michigan basement damage. Farmers includes this protection standard, charging $2,063 annually in Michigan. Replacement cost coverage pays full value for personal property after covered losses, not the depreciated amount. Farmers also writes farm and rural property policies for Michigan's agricultural communities, coverage many competitors decline to offer.
Michigan homeowners pay $2,195 a year on average, but Farmers charges 6% less at $2,063, a full 37% below the $3,467 national average. A security system lowers premiums further. Bundling home and auto policies does too.
Older Homes $269 $3,230 Newer Homes $200 $2,396 Young Homeowners $298 $3,581 Senior Homeowners $282 $3,387 High-Risk Fire Homes $329 $3,947 Smaller Homes $302 $3,629 Larger Homes $339 $4,071 J.D. Power scored Farmers 631 out of 1,000 in its study, 11 points below the 642 industry average. Independent agents deliver coverage across Michigan, writing policies for standard homes and for farm and rural properties most insurers won't touch. Digital tools handle routine policy tasks but offer fewer features than tech-focused insurers provide. Agent-centered service is the tradeoff.
Farmers builds optional add-ons for specialized needs into its standard homeowners protection:
- Water backup coverage: Pays for damage when sewers or drains back up into your home
- Replacement cost for personal property: Covers belongings at full replacement value without depreciation
- Dwelling protection: Pays to repair or rebuild your home after fire, wind, hail or other covered damage
- Personal liability: Covers legal costs and damages if someone gets injured on your property
- Additional living expenses: Pays for hotels and meals while your home undergoes covered repairs
- Farm and agricultural coverage: Insures barns, silos, livestock equipment and farming operations
Best Michigan Home Insurance by City
Auto-Owners ranks as the top home insurance provider in nine Michigan cities, among them Detroit, Grand Rapids, Ann Arbor, Lansing and Warren. Annual premiums run from $261 in Ahmeek to $577 in Detroit. Local risk factors and property values drive the difference.
| Ahmeek | Auto-Owners Insurance | $261 |
| Ann Arbor | Auto-Owners Insurance | $385 |
| Detroit | Auto-Owners Insurance | $577 |
| Grand Rapids | Auto-Owners Insurance | $327 |
| Lansing | Auto-Owners Insurance | $337 |
| Pontiac | Auto-Owners Insurance | $442 |
| Sterling Heights | Auto-Owners Insurance | $374 |
| Stockbridge | Auto-Owners Insurance | $323 |
| Warren | Auto-Owners Insurance | $398 |
Cheapest Michigan Home Insurance Companies
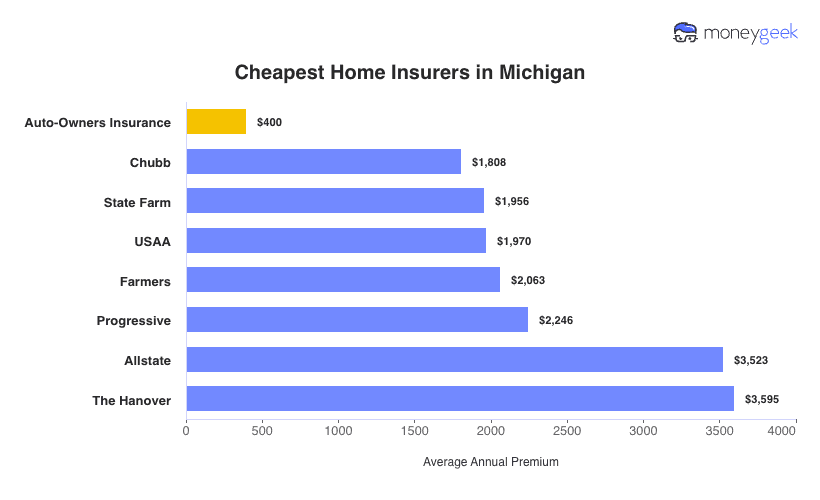
Michigan homeowners pay $2,195 annually for home insurance, 37% less than the national average of $3,467. Auto-Owners offers the state's most affordable home insurance at $400 annually, 82% below the state average. Chubb provides the second-best rates at $1,808 per year, still 18% below average. Premiums vary among insurers. The Hanover represents the high end, charging 4% more than the national benchmark.
Guide to Finding the Best Michigan Home Insurance Company
Compare multiple providers based on your coverage needs, budget and service preferences.
- Compare Quotes Strategically
Get quotes from at least three to five insurers. Premiums among Michigan's top providers range from $400 to $2,063 annually. Price alone won't tell you if a policy covers you. The cheapest option can leave coverage gaps that surface when you file a claim after severe weather or other covered losses.
- Check Customer Satisfaction Metrics
Complaint ratios through the Michigan Department of Insurance and Financial Services are a good starting point. J.D. Power scores among the state's leading insurers range from 621 to 737, against a 642 industry average. Customer reviews about claims handling during Michigan's tornado season matter more than reviews about the purchase experience.
- Evaluate Coverage Needs
Base your coverage on replacement cost, not market value. Construction costs in Michigan surge after flooding and tornadoes hit. Extended or guaranteed replacement cost options are worth reviewing alongside essential protections like flood insurance and wind/hail coverage that match your home's specific risk profile.
- Match Service Preferences to Provider Strengths
Lemonade, Hippo and Root focus on online policy management. Farmers Insurance, State Farm and Allstate maintain strong local agent networks for face-to-face support. Pick based on how you prefer to interact with your insurer, and skip paying for services you won't use.
Michigan experienced over $300 million in flood damage in 2020 alone, according to the Michigan State Police. Flooding is a leading cause of property damage in Michigan, yet many homeowners don't realize their standard insurance policies exclude flood coverage. Your homeowners insurance covers many disasters, but you'll need separate flood insurance through your insurer or the National Flood Insurance Program to protect against flooding.
Get the best rate for your insurance. Compare quotes from the top insurance companies.
Top-Rated Home Insurance Companies in Michigan: FAQ
Explore our FAQ section for answers to common questions about selecting the right Michigan home insurance provider for your needs.
Home insurance covers fallen tree damage to your house when wind, lightning or other covered perils cause the tree to fall. Coverage excludes trees that fell due to rot or neglect. Tree removal is covered only if the tree damaged a structure, and most policies limit coverage to $500 to $1,000 per tree.
Replacement cost coverage pays to rebuild your home or replace belongings at current market prices without factoring in depreciation. Actual cash value coverage deducts depreciation based on your property's age and condition, resulting in lower claim payouts. Actual cash value policies cost less upfront, but you'll pay more out of pocket when filing a claim.
Detroit homeowners pay $577 annually through Auto-Owners, which is 121% higher than the $261 rate in Ahmeek and 76% higher than the $327 rate in Grand Rapids. Annual premiums vary based on local risk factors, property values and city-specific claims history.
Yes, standard homeowners insurance policies in Michigan exclude flood coverage, even for inland properties. Michigan experienced over $300 million in flood damage in 2020 alone, so you'll need separate flood insurance through your insurer or the National Flood Insurance Program to protect against flooding.
Our Methodology: Determining the Best Michigan Home Insurers
Michigan homeowners deal with tornado risks, hurricane exposure and fluctuating construction costs. Our ranking system weighs affordable premiums, quality coverage and reliable claims handling.
We scored insurers across three factors:
Affordability (55%): We compared rates for identical coverage across major providers and evaluated discount availability.
Customer satisfaction (30%): J.D. Power ratings, Trustpilot reviews and app feedback reveal how insurers handle claims after storms damage your home.
Coverage options (15%): We assessed add-on availability, including water backup protection and inland flood options for Michigan's risks.
Our Sample Profile
Rates reflect a homeowner aged 41-60 with good credit and no prior claims insuring a 2,500-square-foot home built in 2000. Coverage includes $250,000 dwelling coverage, $125,000 personal property coverage, $200,000 personal liability coverage and a $1,000 deductible.
Your rates will vary based on your home's age, location, claims history and credit score.
About Mark Fitzpatrick

Mark Fitzpatrick is a licensed Property and Casualty (P&C) Insurance Producer in Connecticut and MoneyGeek's resident expert in insurance and economics. In nearly a decade covering the insurance market at LendingTree and MoneyGeek, he's analyzed hundreds of carriers and millions of rates across auto, home, renters, health and life insurance.
His work has appeared in The Washington Post, The New York Times and NPR. He draws on independent cost and consumer experience data, and no insurance company partnerships affect his recommendations.
Mark studied at Boston College and later earned a master's in economics and international relations from Johns Hopkins University. He worked in financial risk management at State Street before joining MoneyGeek. He's also a five-time “Jeopardy!” champion.
- Michigan State Police. "Michigan State Police." Accessed September 17, 2026.


