Best General Liability Insurance Companies in Washington

I compared average rates of general liability quotes from 10 insurers across 25 Washington industries with limits of $1 million per claim and $2 million total coverage. Price, however, was only the starting point. I also researched how each carrier handled policy and proof-of-insurance updates, so paperwork doesn’t hold up a contract or scheduled job. 

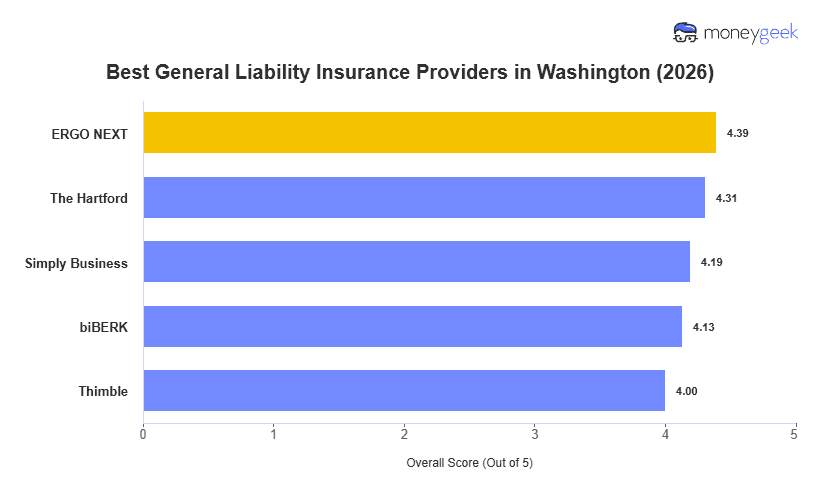
My analysis found that the best general liability insurance providers are:

  • Choose if you offer hands-on services: ERGO NEXT
  • Choose if you're a knowledge-based professional service provider: The Hartford
  • Choose if you want to compare coverage options: Simply Business
  • Choose if you're a solo or independent operators: biBerk
  • Choose if you want short-term or project-based coverage: Thimble

For our Washington general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focused on one-to-four-person businesses, which represent a large share of Washington's small business market. We weighted results for broader industry and location representation across the Puget Sound corridor, Eastern Washington agricultural communities, the Olympic Peninsula and urban centers like Spokane and Tacoma.

We evaluated over 20,000 business profiles and more than 2,300 customer experience data points. We also reviewed coverage contracts and endorsements to compare how insurers served Washington businesses across different industries and regions. We then rated each company across affordability (50%), customer experience (30%) and coverage options and terms (20%). For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Washington, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

2,342

Customer Experiences Analyzed

ERGO NEXT

ERGO NEXT: Best Overall, Best for Hands-On and Service Industries

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT ranks first overall in Washington and is the only provider in our analysis to lead in price and overall quality. It's the most cost-effective option across 16 of 24 Washington industries, with the deepest savings in hospitality and manufacturing (36% below the Washington average), food and beverage (32%) and repair and maintenance (35%).

A fully digital quote from ERGO NEXT takes under 10 minutes, and certificates of insurance are issued at purchase, which means Washington contractors get proof of coverage the same day. Digital tools work well, but live support responsiveness lags behind top options. Claims handling ranks lower too.

Reviews point to recurring complaints about adjuster access and dispute resolution. Coverage includes standard $1 million per occurrence and $2 million aggregate limits, with higher limits available through umbrella. The endorsement menu is narrower than most traditional carriers, which limits options for businesses that need liquor liability, cyber or other specialty coverage.

Learn more: ERGO NEXT Review

The Hartford

The Hartford: Best for Professional and Knowledge Businesses

On The Hartford's site
COMPANY HIGHLIGHTS

The Hartford ranks second overall in Washington because of its coverage depth, competitive general liability rates and post-purchase experience. Besides BOP bundling, businesses can add endorsements like liquor liability, cyber and EPLI. That gives Washington businesses with specialty needs more ways to customize coverage.

The Hartford is most affordable for office-based industries: health care and medical services save 27%, education saves 26%, arts, media and entertainment save 23% and financial services save 19%. The agent-assisted model slows quote speed, and businesses in Eastern Washington or rural areas may see longer timelines than those in the Seattle or Tacoma metro.

Post-purchase reviews point to responsive live support and billing flexibility. On claims, policyholders mention consistent adjuster communication and fair settlements.

Learn more: The Hartford Review

Simply Business

Simply Business: Best for Comparing Coverage Options

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business ranks third overall for general liability in Washington and is the only aggregator in MoneyGeek's analysis. Instead of underwriting policies itself, the platform matches Washington businesses with several carriers in one quote session. That model suits the state's large population of independent contractors and gig workers, who often care more about comparing prices quickly than about one provider's underwriting process.

Your limits and endorsements depend on the carrier you're matched with, so coverage terms vary. Businesses with specialty needs, such as liquor liability or cyber coverage, can look for a carrier that offers them, but the terms aren't guaranteed until you buy.

Because the quotes come from the carriers themselves, the prices are accurate. Policy terms are harder to compare across carriers, though, and sales support is more limited than with a single-carrier insurer. The biggest savings, 16% to 19% below average, go to three industries: retail and product rental, repair and maintenance, and beauty and wellness.

Learn more: Simply Business Review

biBerk

biBerk: Best for Solo and Independent Service Operators

COMPANY HIGHLIGHTS

biBerk ranks fourth overall in Washington with competitive premiums, though it scores lower for customer experience and coverage flexibility. Cleaning businesses save 19%, fitness services save 21% and recreation and sports businesses save 18%. It's also the most affordable option for solopreneurs, who pay 10% less on premiums.

biBerk's digital-direct model, backed by Berkshire Hathaway, removes the need for an agent. The quote and purchase process is transparent, with clear pricing and no sales pressure. Post-sale reviews reflect recurring complaints about support access and slow endorsement processing, and claims handling ranks mid-pack. Standard limits are $1 million per occurrence and $2 million aggregate, but biBerk doesn't offer liquor liability, cyber or EPLI.

Learn more: biBerk Review

Thimble

Thimble: Best for Short-Term and Project-Based Coverage

COMPANY HIGHLIGHTS

Thimble is the only provider in our analysis offering short-term general liability policies and ranks fifth overall in Washington. Business owners can buy coverage by the job, day, week or month. That structure fits Washington's freelancers, seasonal contractors and gig workers who don't need year-round coverage. Among the general industries in Washington, the two that see the most savings are construction (22%) and manufacturing (19%).  

Thimble's quote flow is built for speed, and contractors can get covered quickly for a single job. Claims handling ranks lower because of recurring complaints about initiation difficulty and slow resolution. Policies include standard $1 million per occurrence and $2 million aggregate limits, with higher amounts available for eligible businesses. Tools and equipment can be added, but other common endorsements like cyber liability and HNOA aren't available.

Learn more: Thimble Review

What Determines the Best General Liability Insurance for Washington Businesses

Before comparing general liability insurance carriers in Washington, describe everything your business actually does and where that work happens. A marine supplier that also installs equipment at customer docks shouldn’t be quoted as a retail-only operation. Use that full description and your toughest client contract to test whether an insurer fits.

How to Choose the Best General Liability Insurance in Washington

Compare general liability providers using more than monthly rates. These six steps guide your decision in a logical order, so you evaluate the right factors at the right time and get general liability insurance coverage that matches your Washington business.

  1. 1

    Optimize your payment and coverage structure

    Base your general liability coverage and payment plan on where your work takes place, who your clients are and how your liability exposure builds over the year.

    Questions to ask yourself:

    • Does your work take place on client property, public land or permitted job sites, where Washington contractors, landscapers and trade workers are exposed to third-party liability?
    • Does your Washington business license, commercial lease or any client contract require minimum general liability limits?
    • Is your work seasonal? Eastern Washington harvest equipment operators, ski resort vendors and Puget Sound fishing charters take on most of their exposure in a short window.
    • Can your business pay out of pocket for a single incident, such as a slip in a retail space, damage to a client's irrigation system or a dispute over a completed job?

    A Whidbey Island farm stand that hosts weekend visitors can get by with standard GL limits. A Renton aerospace parts supplier taking on larger commercial contracts may need higher limits to meet client general liability requirements and cover its greater exposure.

    If your cash flow can absorb it, paying annually lowers your total cost. A higher deductible can also lower your premium, as long as you can pay that amount without disrupting your business.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2

    Choose your primary priority

    Choose your priority based on your finances, how complex your operations are and how much support you expect from an insurer.

    • Cost predictability comes first if your business operates on tight or seasonal margins. A Wenatchee apple orchard equipment operator or a Methow Valley outdoor guide service that brings in most of its revenue in a few months can't absorb a sudden renewal increase. When your budget has little room, stable premiums are worth more than the lowest starting rate.
    • Service quality comes first when your work depends on quick paperwork, fast policy updates or responsive claims service. A Bellevue facilities management company with several client sites or a Tri-Cities event rental company with back-to-back bookings needs an insurer that issues certificates and processes changes without delays that can cost contracts.
    • Coverage depth comes first when your business is growing, taking on larger clients or entering higher-risk work. A Grays Harbor marine contractor expanding into commercial port work or a Spokane general contractor adding service lines should review its general liability limits, since its current limits and endorsements may fall behind its real exposure.
  3. 3

    Shortlist two to three providers

    Check eligibility before you look at price. Find out whether each insurer accepts all of your regular activities, especially farm operations open to visitors or marine work at customer docks. Then keep the two or three qualifying providers that best fit your priority and contract requirements.

  4. 4

    Double-check for dealbreakers before investing more time

    Make sure each provider meets every one of your non-negotiables:

    • Does the provider write policies for your industry in Washington? Some insurers cover standard retail or office businesses but turn down or heavily surcharge marine contractors, timber operations near wildfire areas or businesses that use agricultural chemicals.
    • Can the insurer cover a business of your revenue and payroll size? Some set eligibility limits that rule out growing trade businesses or companies with several locations.
    • Can the provider issue a certificate of insurance the same day or the next day? A Walla Walla event caterer or a Lewis County logging subcontractor may need proof of coverage right away.
    • Will your coverage still apply as your business grows? If you work on both sides of the Cascades or in several counties, confirm the policy covers you statewide without restricting service areas.
  5. 5

    Compare your finalists using the same three lenses

    Rate each of your two or three finalists on price, service and coverage. A provider that does well in one area but falls short in another can cause problems at renewal or when you file a claim.

    • Pricing consistency matters through the whole policy cycle. A Columbia River commercial fisherman's catch volume changes from season to season, and a Spokane contractor's payroll can jump mid-project. Both need an insurer that adjusts mid-term and reprices at renewal without surprises. If a provider can't explain a rate increase, treat that as a red flag.
    • Service quality matters most when something changes. Certificate turnaround, policy changes and claims response tell you more about a provider than its quote process does. A Puget Sound marine surveyor adding a vessel type or a Port Angeles hospitality business picking up a new venue contract can't afford delays when coverage details change.
    • Coverage flexibility decides whether the policy can grow with your business. A Kennewick solar installer expanding into commercial rooftop work will probably outgrow a basic GL policy, and so will an Olympia environmental consultant adding state agency contracts. Both may need higher per-occurrence and aggregate limits and new endorsements, so confirm the provider can add them without a new policy.
  6. 6

    Use quotes as the final confirmation step

    Confirm your choice with quotes from each finalist for the same limits and endorsements, based on a complete description of your work. Compare business insurance quotes to see what each insurer charges for the same operations and coverage terms. If one quote comes in much lower, check whether it leaves out part of your work or a required endorsement before you treat it as the better deal.

    If you install equipment at docks or invite customers onto your farm, get written confirmation that the quote covers those activities, and review the exclusions before you choose.

Best Small Business General Liability Insurance in Washington: Bottom Line

ERGO NEXT, The Hartford and Simply Business are the top-ranked general liability insurers in Washington. The right one for you depends on your type of business, how it's structured and which coverage add-ons it may need over time.

The strongest choice balances pricing stability over the full policy cycle, service quality across documentation and claims and real coverage depth rather than the lowest quote at sign-up. That alignment keeps the policy matched to actual risk exposure and day-to-day operations in Washington.

Best General Liability Insurance For Small Business in Washington Chart

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com