Best Professional Liability Insurance (E&O) Companies in Washington, D.C.

Our analysis of Washington, D.C. professional liability insurers found three providers that consistently outperformed the rest on affordability, coverage fit and overall score.

  1. ERGO NEXT: Ranking first across 13 of 18 industries in the district, this insurer covers more of the D.C. market's professional landscape than any other provider in the study. Its fully digital platform lets you buy a policy in about 10 minutes, manage it online around the clock and pull a certificate of insurance instantly without calling anyone. ERGO NEXT performs best for D.C. businesses in healthcare, construction, real estate, marketing, arts, fitness, pet care and cleaning services, though businesses in consulting, financial services, education and hospitality will find better-ranked options elsewhere.
  2. The Hartford: More than 200 years of underwriting experience shows up in the claims department, where The Hartford earns consistent marks for how it processes and pays out professional liability claims. It's the top-ranked insurer in Washington, D.C. for consultants, financial services firms, real estate professionals, educators and marketing businesses, making it a strong fit for the district's large concentration of professional services firms. D.C. healthcare providers and other professional services businesses, where The Hartford ranks ninth, are better served by another carrier on this list.
  3. Simply Business: Rather than underwriting policies itself, Simply Business works as a marketplace, pulling quotes from carriers including Hiscox, Travelers, Liberty Mutual and Markel so D.C. businesses can compare options in one application. That model gives it an edge for businesses that want coverage options side-by-side before committing. It ranks at the top of the D.C. market for consulting, financial services, fitness and healthcare businesses, but arts, media and recreation businesses will find stronger fits with other providers.

These three providers cover most Washington, D.C. businesses well, but no ranked list accounts for every business's specific risk profile, coverage limits or industry nuances. Comparing business insurance options directly and getting quotes from more than one carrier gives you the clearest read on what's actually right for your business.
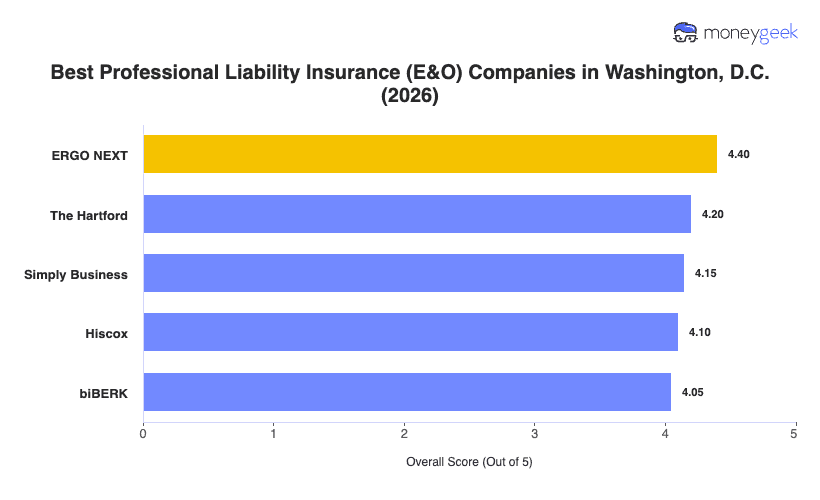
ERGO NEXT4.4021$57
The Hartford4.2094$48
Simply Business4.1563$60
Hiscox4.1087$54
biBERK4.05109$60

How to Get the Best Professional Liability Insurance in Washington, D.C.

Getting professional liability coverage in D.C. varies by industry, client type and where in the district you operate. These seven steps walk through it.

  1. 1

    Check your DC licensing board requirements first

    Some D.C. professions build insurance into the licensing process. Childcare providers must file proof of general liability, umbrella and abuse coverage with OSSE, and contractors must show a general liability certificate to the Department of Licensing and Consumer Protection before a license issues. Verify any insurer through the D.C. Department of Insurance, Securities and Banking database.

  2. 2

    Assess your coverage needs based on your work and clients

    Your risk tier depends on the complexity of your work, the size of your contracts and the exposure a claim could create. Use those factors to gauge how much professional liability insurance you need, since D.C. federal and enterprise contracts often set $1M-per-occurrence minimums.

  3. 3

    Work with a local agent who knows the DC market

    Coverage needs shift by neighborhood, from advice-driven claims around Capitol Hill to construction and healthcare exposure in NoMa and Navy Yard. A local agent also understands D.C.'s no-tort-reform, no-caps litigation environment that keeps some specialty premiums among the highest in the country.

  4. 4

    Get quotes from at least three insurers and compare coverage details

    Two policies at the same premium can differ sharply in exclusions and how the deductible applies. Confirm the retroactive date goes back far enough to cover your prior work, especially if you switch carriers mid-contract.

    Read More: What Does Professional Liability Insurance Cover?

  5. 5

    Research providers beyond price

    Confirm the carrier is licensed to write professional liability in the district, then check its claims record and AM Best financial strength rating. D.C. associations such as the D.C. Bar and the Medical Society of the District of Columbia can point you to profession-specific carriers.

  6. 6

    Consider bundling with other business coverage

    Pairing professional liability with general liability or a BOP often cuts your total premium 10% to 15% versus buying separately. Many D.C. consulting firms, nonprofits and trade associations already need both, so bundling is usually the practical structure.

  7. 7

    Do not let your coverage lapse, and understand tail coverage

    D.C. professional liability is almost always written claims-made, so the active policy when a claim is filed is the one that responds. Before you cancel or switch, buy tail coverage or confirm your new carrier offers nose coverage for prior acts.

Best Washington, D.C. Professional Liability Insurance (E&O): Bottom Line

The right professional liability policy in Washington, D.C. comes down to matching coverage to the actual risk your work creates, not just buying the cheapest option. ERGO NEXT earns the top overall rating in the district, but your industry, your clients and the contract minimums they impose should weigh as heavily as any ranking. Get quotes from at least three carriers, compare what each policy actually covers, and factor in D.C.'s no-tort-reform, no-caps environment when you set your limits.

Best Professional Liability Insurance Washington, D.C. Chart

Professional Liability Insurance DC: FAQ

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com


Sources