

Erie Insurance is the cheapest car insurance in West Virginia at $37 a month for minimum coverage and $95 a month for full coverage. Erie holds the lowest rate across most driver profiles in the state, including after speeding tickets ($103/month), texting violations ($103/month) and at-fault accidents ($113/month). State Farm is the most affordable option after a DUI ($129/month) and for senior drivers ($127/month). For a full comparison of service, claims handling and coverage options, see the best car insurance in West Virginia table below.
Cheapest Car Insurance in West Virginia for 2026
Contributions by 6+ experts

Updated: November 12, 2026
Advertising & Editorial Disclosure
Erie Insurance | $37 | 4.90 | |
Erie Insurance | $95 | 4.90 | |
Erie Insurance | $322 | 4.90 | |
Erie Insurance | $284 | 4.90 | |
State Farm | $127 | 3.82 | |
Westfield Insurance | $28 | 4.16 | |
Westfield Insurance | $241 | 4.16 | |
Erie Insurance | $103 | 4.90 | |
Erie Insurance | $113 | 4.90 | |
State Farm | $129 | 3.82 |
Cheapest Car Insurance by Coverage Type in West Virginia
The cheapest car insurance in West Virginia for minimum coverage is Erie Insurance at $37 a month ($444 yearly). Westfield Insurance is the second lowest at $38 a month. For full coverage, Erie is the most affordable at $95 a month ($1,140 a year), with Westfield next at $121 a month, a difference of $26 a month or $312 a year. At $95 a month plus rate reductions from Rate Lock feature, Erie is the cheapest and best choice for full coverage in West Virginia.
| Erie Insurance | $37 | $95 | 4.9 |
| Westfield Insurance | $38 | $121 | 4.16 |
| State Farm | $50 | $122 | 3.82 |
| Farmers | $89 | $164 | 3.54 |
| Progressive | $97 | $150 | 3.9 |
Your Next Step:
Get your real quotes from trusted insurance providers.
Cheapest Car Insurance for Teens and Young Adults in West Virginia
Erie Insurance is the cheapest car insurance for teens in West Virginia at $322 a month for a 16-year-old male and $284 a month for a 16-year-old female, holding the lowest rate through age 18. Westfield Insurance shows the lower rate from 19 through most of the young adult range, with both carriers converging at $178 at age 25. The full breakdown by age is in the table below.
Erie also offers ERIE Rate Lock, a feature Westfield doesn't have, which keeps your rate from increasing at renewal even after a claim as long as you do not change your drivers, vehicles or address.
Rates drop significantly as young drivers build experience. A 16-year-old male pays $322 today while a driver with the same profile at 25 pays $178, a $144 difference. The carrier that is cheapest in this table shifts across age groups, which means it is worth getting new quotes at renewal once a teen has built a few years of clean driving history.
| 16 | Erie Insurance | $322 | Erie Insurance | $284 |
| 17 | Erie Insurance | $309 | Erie Insurance | $272 |
| 18 | Erie Insurance | $293 | Erie Insurance | $261 |
| 19 | Westfield Insurance | $263 | Westfield Insurance | $253 |
| 20 | Westfield Insurance | $252 | Westfield Insurance | $243 |
| 21 | Westfield Insurance | $242 | Westfield Insurance | $178 |
| 22 | Westfield Insurance | $235 | Westfield Insurance | $178 |
| 23 | Westfield Insurance | $226 | Westfield Insurance | $178 |
| 24 | Erie Insurance | $183 | Westfield Insurance | $178 |
| 25 | Westfield Insurance | $178 | Westfield Insurance | $178 |
Cheapest Car Insurance for Seniors in West Virginia
State Farm offers the cheapest car insurance for seniors in West Virginia at $127 a month for full coverage. Westfield Insurance is the second lowest at $143 a month, $16 more. Westfield is not worth the extra $192 a year, especially because it does not offer programs such as State Farm's Drive Safe & Save, which gives a 10% discount immediately when a senior enrolls, bringing the $127 rate to $114 a month and saving $13 a month or $156 a year on the spot.
Additionally, Drive Safe & Save can lower the rate by up to 30%. At the full 30% Drive Safe & Save discount, the $127 rate drops to $89 per month, saving $456 per year. Drive Safe & Save cannot raise the rate based on driving data. State Farm also offers a Mature Driver Discount for seniors 55 and older who complete a State Farm-approved defensive driving course. Ask a State Farm agent about current eligibility and the discount amount in West Virginia.
| State Farm | $127 | $1,521 | 4.05 |
| Westfield Insurance | $143 | $1,720 | 4.16 |
| Farmers | $152 | $1,821 | 3.98 |
| Progressive | $190 | $2,284 | 3.84 |
| Allstate | $237 | $2,840 | 3.47 |
Cheapest Car Insurance in West Virginia by City
Westfield Insurance is the cheapest car insurance in West Virginia for minimum coverage across every city in this table. Rates range from $28 a month in Martinsburg to $35 a month in Huntington, a $7 difference across the state. The city you live in changes what Westfield charges, but not which carrier to quote first. That $7 range is far smaller than the $58 difference between Erie's minimum and full coverage rate. Where you live matters less than what coverage level you choose.
| Martinsburg | Westfield Insurance | $28 | $334 |
| Clarksburg | Westfield Insurance | $29 | $354 |
| Fairmont | Westfield Insurance | $29 | $348 |
| Morgantown | Westfield Insurance | $29 | $345 |
| Oak Hill | Westfield Insurance | $29 | $347 |
| Vienna | Westfield Insurance | $29 | $351 |
| Weirton | Westfield Insurance | $29 | $345 |
| Lewisburg | Westfield Insurance | $30 | $360 |
| Nitro | Westfield Insurance | $30 | $366 |
| Parkersburg | Westfield Insurance | $30 | $356 |
| Beckley | Westfield Insurance | $31 | $373 |
| Bluefield | Westfield Insurance | $31 | $375 |
| Princeton | Westfield Insurance | $31 | $375 |
| Charleston | Westfield Insurance | $32 | $386 |
| Dunbar | Westfield Insurance | $32 | $380 |
| Elkins | Westfield Insurance | $32 | $387 |
| South Charleston | Westfield Insurance | $32 | $380 |
| St. Albans | Westfield Insurance | $32 | $385 |
| Wheeling | Westfield Insurance | $32 | $380 |
| Huntington | Westfield Insurance | $35 | $414 |
Why Is Car Insurance So Expensive in West Virginia?
West Virginia drivers face the highest likelihood of an animal collision in the country, a position the state has held for more than a decade, according to State Farm's annual animal collision data. The odds of filing an animal collision claim in West Virginia are 1 in 40, compared to a national average of 1 in 145. Animal collisions, overwhelmingly deer strikes, file as comprehensive claims. Minimum coverage pays nothing toward a deer strike. Only full coverage does.
That risk is built into rates across the state. Drivers can offset it by enrolling in a telematics program. Erie's ERIE Rate Lock keeps the rate from increasing at renewal even after a comprehensive claim. State Farm's Drive Safe & Save and Westfield's MissionSafe can both lower the base rate for safe drivers, regardless of ZIP code.
Cheapest Car Insurance for Bad Credit Score Drivers in West Virginia
Westfield Insurance is the cheapest car insurance in West Virginia for drivers with bad credit at $241 a month for full coverage and $79 a month for minimum coverage. Erie Insurance is the second lowest at $243 a month for full coverage, just $2 more than Westfield. With only $2 a month between Westfield and Erie, both are worth getting a quote from.
For a bad credit driver, the most useful question is what each carrier can do while credit is still recovering. Westfield's MissionSafe lowers the rate based on driving behavior, not credit score. The 10% enrollment discount immediately brings the $241 rate down to $217, saving $24 a month or $288 a year. At the average 20% renewal discount, the rate drops to $193 a month, saving $48 a month or $576 a year. Erie at $243 does not have an equivalent program that lowers the rate while credit is poor. Its advantage is long-term: when credit improves, Erie's clean-credit rate is $95 a month compared to Westfield's $121.
| Westfield Insurance | $79 | $241 | 4.29 |
| Erie Insurance | $106 | $243 | 4.79 |
| Progressive | $188 | $365 | 4.38 |
| Farmers | $212 | $442 | 4.03 |
| Allstate | $234 | $480 | 4.07 |

HOW CREDIT SCORE AFFECTS WEST VIRGINIA CAR INSURANCE
West Virginia has no rule protecting drivers from rate increases at renewal if credit worsens, and no rule that automatically lowers the rate when credit improves. Credit affects both new policies and renewals here. That means improving credit is not enough on its own. Getting new quotes after credit recovers is what captures the lower rate. Erie charges $95 a month for full coverage with good credit. A bad-credit driver paying $243 a month with Erie is paying $148 more. Once credit improves, switching to Erie's clean-credit rate saves $1,776 a year.
Cheapest Car Insurance for High-Risk Drivers in West Virginia
The cheapest car insurance in West Virginia for high-risk drivers depends on the violation. Erie is cheapest after a speeding ticket and texting while driving at $103 a month, adding $8 to its $95 clean-record rate. After an at-fault accident, Erie is again the most affordable at $113 a month, adding $18 over its clean rate. After a DUI, State Farm is cheapest at $129 a month, the one violation where Erie does not hold the lowest rate.
State Farm is the most affordable option after a DUI in West Virginia at $129 a month for full coverage, just $7 more than its $122 clean-record rate. Erie is the second lowest at $145 a month, $16 more than State Farm. Neither First Accident Forgiveness nor Rate Lock applies to DUI rate increases, so there is no Erie-specific benefit that justifies the $16 gap. State Farm is the right call here.
Erie's First Accident Forgiveness means the first at-fault accident does not trigger a rate increase for Erie customers who have been with the company for at least three years without an at-fault accident. For a driver currently paying $95 a month with a clean record, that protection is worth having before an accident happens.
| At-Fault Accident | Erie Insurance | $113 | $46 | 4.9 |
| DUI | State Farm | $129 | $54 | 4.45 |
| Speeding Violation | Erie Insurance | $103 | $40 | 4.9 |
| Texting While Driving | Erie Insurance | $103 | $40 | 4.9 |
How to Get Cheaper Car Insurance in West Virginia
Most drivers in West Virginia pay more than they need to because they haven't compared carriers, matched coverage to their vehicle's value or looked into discount programs. The gap between the right and wrong decisions here is significant. Switching to Erie from the most expensive carrier saves $55 a month. Choosing minimum over full coverage saves another $58. Violations, credit and telematics programs can each shift the final rate further. These six steps show how to work each one.
- 1Compare at least three West Virginia insurers and save up to $55 a month
Get quotes from Erie, State Farm and Westfield before renewing. The difference between the cheapest and most expensive full coverage option in West Virginia is $55 a month: Erie at $95 versus Progressive at $150, or $660 a year. Rates shift at every renewal, so don't assume last year's best option still holds.
- 2Match your coverage level to your vehicle's value and save $58 a month
Check your vehicle's current value before your next renewal. If it's worth less than $6,960, dropping to minimum coverage may save more than the policy could pay out in a claim over ten years. Full coverage costs $58 more a month than minimum at Erie, or $696 a year. Use the car insurance calculator to run the numbers for your vehicle.
- 3Bundle home and auto with the same carrier
Bundling home and auto with the same insurer earns a multi-policy discount at most West Virginia companies. Compare bundled rates at best home and auto bundle before renewing either policy separately.
- 4Get new quotes when your violation ages off and recover up to $18 a month
Get new quotes when three to five years have passed from the violation date. West Virginia insurers typically apply rate increases for three to five years from the policy renewal following the violation. A speeding ticket or texting while driving violation adds $8 a month at Erie. An at-fault accident adds $18. Both may clear before the five-year mark. Checking at three years is the right time to quote.
- 5Improve your credit score before renewal and recover $148 a month
Improve your credit before your next renewal date, then get new quotes at Erie. West Virginia permits credit as a rating factor. Westfield charges $241 a month for bad credit. Erie charges $95 a month for good credit. Switching to Erie once credit improves recovers $148 a month, or $1,776 a year.
- 6Ask your carrier about discount programs
Erie, State Farm and Westfield each offer ways to lower the base rate beyond what the table shows.
- Erie Insurance: Available through independent agents. Ask your Erie agent about multi-policy, multi-vehicle and driver training discounts. Specific percentages vary by agent and policy and are not published.
- State Farm: Drive Safe & Save gives 10% off immediately when a driver enrolls, bringing the $122 full coverage rate to $110 and saving $12 a month or $144 a year. At the maximum 30% discount at renewal, the rate drops to $85, saving $37 a month or $444 a year. The rate cannot go up from Drive Safe & Save data.
- Westfield Insurance: MissionSafe gives 10% off the $121 full coverage rate immediately upon enrollment, bringing it to $109 and saving $12 a month or $144 a year. At the average 20% renewal discount, the rate drops to $97, saving $24 a month or $288 a year.
Should You Get Minimum or Full Coverage in West Virginia?
Full coverage is worth it for most West Virginia drivers. Erie's full coverage costs $58 more a month than minimum, or $696 a year. That extra money adds collision and comprehensive, which pay for damage to your own car. Without them, if you cause an accident or your car is stolen or damaged by weather, the repair bill is yours.
If your car is worth less than $6,960, the cost of full coverage over ten years could exceed what you'd recover in a total-loss payout. Drivers with a car loan or lease need full coverage as a condition of their financing. Use the West Virginia car insurance calculator to see where your vehicle lands.
Is Minimum Coverage a Risk in West Virginia?
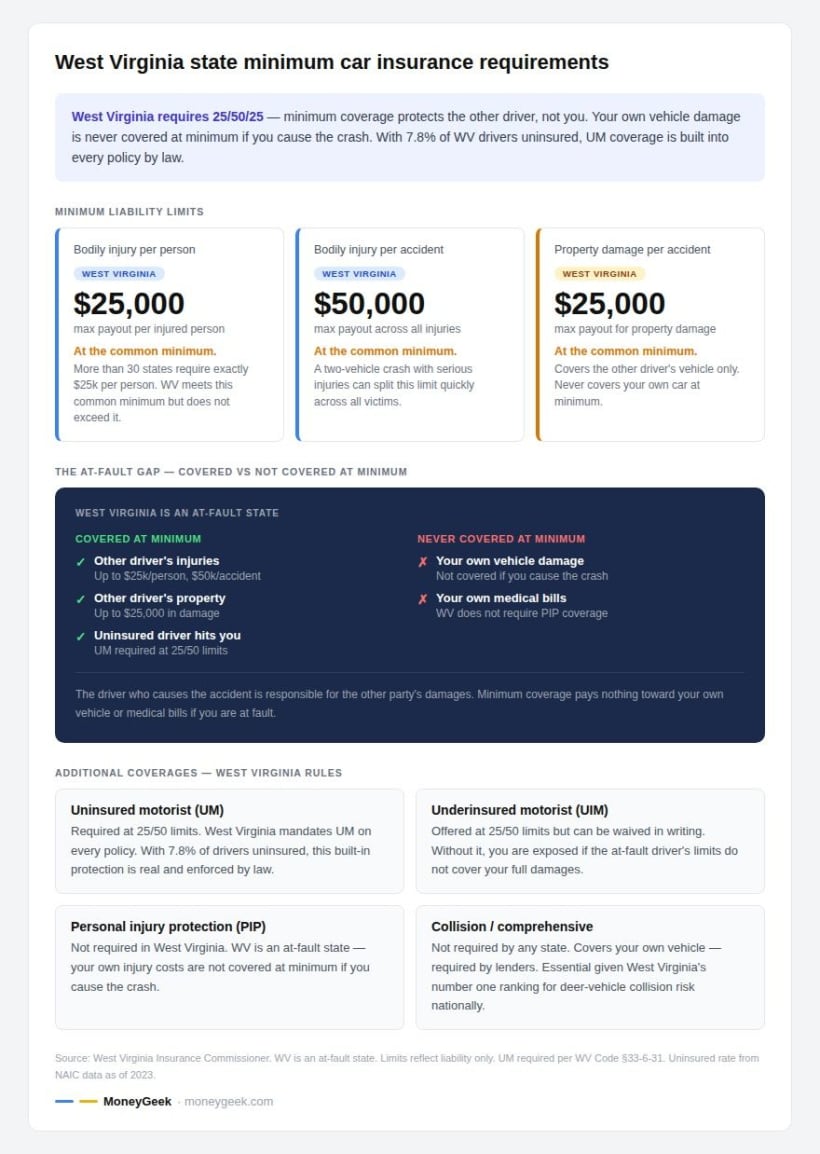
West Virginia's minimum is 25/50/25: $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. Every policy must include uninsured motorist coverage at matching limits. Underinsured motorist coverage is offered at the same limits and can be waived in writing, but keeping it is the right call for most drivers. West Virginia does not require personal injury protection.
West Virginia is an at-fault state, meaning the driver who causes the accident is responsible for the other party's damages. Minimum coverage pays nothing toward the at-fault driver's own vehicle. Only collision and comprehensive, which come with full coverage, protect it. West Virginia's 7.8% uninsured driver rate is below the national average of roughly 14%, so the UM requirement in minimum coverage provides real protection without the heightened exposure drivers face in higher-uninsured states.
State Minimum Requirement in West Virginia
MoneyGeek analyzed car insurance rates in West Virginia using data from Quadrant Information Services, collected from state insurance filing records across all residential ZIP codes in West Virginia. Carriers must file rates with the state regulator before charging them. These are filed rates, not estimates or quote approximations.
The baseline driver profile is a 40-year-old male driving a 2012 Toyota Camry LE with a clean record, good credit and 12,000 annual miles. Full coverage uses 100/300/100 liability with a $1,000 deductible. Minimum coverage meets West Virginia's 25/50/25 liability requirement plus mandatory UM/UIM at 25/50. Profile variations include young drivers ages 16 to 25 on individual policies, a senior driver starting at age 65, violation profiles with one driving record variable changed at a time, and a poor-credit profile. USAA is excluded from all tables. It is available only to military members, veterans and immediate family. Eligible drivers should include USAA in any quote comparison.
West Virginia is an at-fault state with no personal injury protection requirement. West Virginia does not require SR-22 filings after a DUI. Reinstatement after a DUI requires completing the Safety and Treatment Program, paying a reinstatement fee and, where applicable, installing an ignition interlock device. West Virginia permits credit as a rating factor. Gender is a permitted rating factor in West Virginia. West Virginia's 7.8% uninsured driver rate is sourced from NAIC data as of 2023.
MoneyGeek scores carriers on three factors: affordability (60% of score, normalized rates across all carriers within each driver profile), customer experience (30%, based on J.D. Power survey results, NAIC complaint index, AM Best financial strength ratings, agent network ratings and Google Business ratings) and coverage options (10%, based on the breadth of available add-ons and included benefits). The Overall MoneyGeek Score shown in summary tables reflects this composite. Customer experience sub-scores shown in section-level tables reflect the customer experience component only and differ from the overall score.



About Mark Fitzpatrick

Mark Fitzpatrick is a licensed Property and Casualty (P&C) Insurance Producer and MoneyGeek's resident expert in insurance and economics. In nearly a decade covering the insurance market at LendingTree and MoneyGeek, he's analyzed hundreds of carriers and millions of rates across auto, home, renters, health and life insurance.
His work has appeared in The Washington Post, The New York Times and NPR. He draws on independent cost and consumer experience data, and no insurance company partnerships affect his recommendations.
Mark studied at Boston College and later earned a master's in economics and international relations from Johns Hopkins University. He worked in financial risk management at State Street before joining MoneyGeek. He's also a five-time “Jeopardy!” champion.
Sources
- Insurance Information Institute. "Facts + Statistics: Auto insurance." Accessed November 10, 2026.
- Insurance Information Institute. "Facts + Statistics: Hurricanes." Accessed November 10, 2026.
- Insurance Information Institute. "Facts + Statistics: Uninsured motorists." Accessed November 10, 2026.
- National Insurance Crime Bureau. "Vehicle Thefts Surge Nationwide in 2023." Accessed November 10, 2026.
- JD Power. "Satisfaction with Auto Insurance Claims Strained by Higher Deductibles, More Total Losses, JD Power Finds." Accessed November 10, 2026.
- JD Power. "It’s Now a Buyer’s Market for Auto Insurance, JD Power Finds." Accessed November 10, 2026.