

Term life insurance has a fixed term and a lower price, but no cash value component. Whole life insurance covers the policyholder's entire life at a higher premium and includes a cash value component that accumulates over time.
Term Life vs. Whole Life Insurance: Key Differences and How to Choose
Term life insurance costs less than whole life insurance because it covers you for a set number of years and has no cash value, which is a savings component that may grow over time.
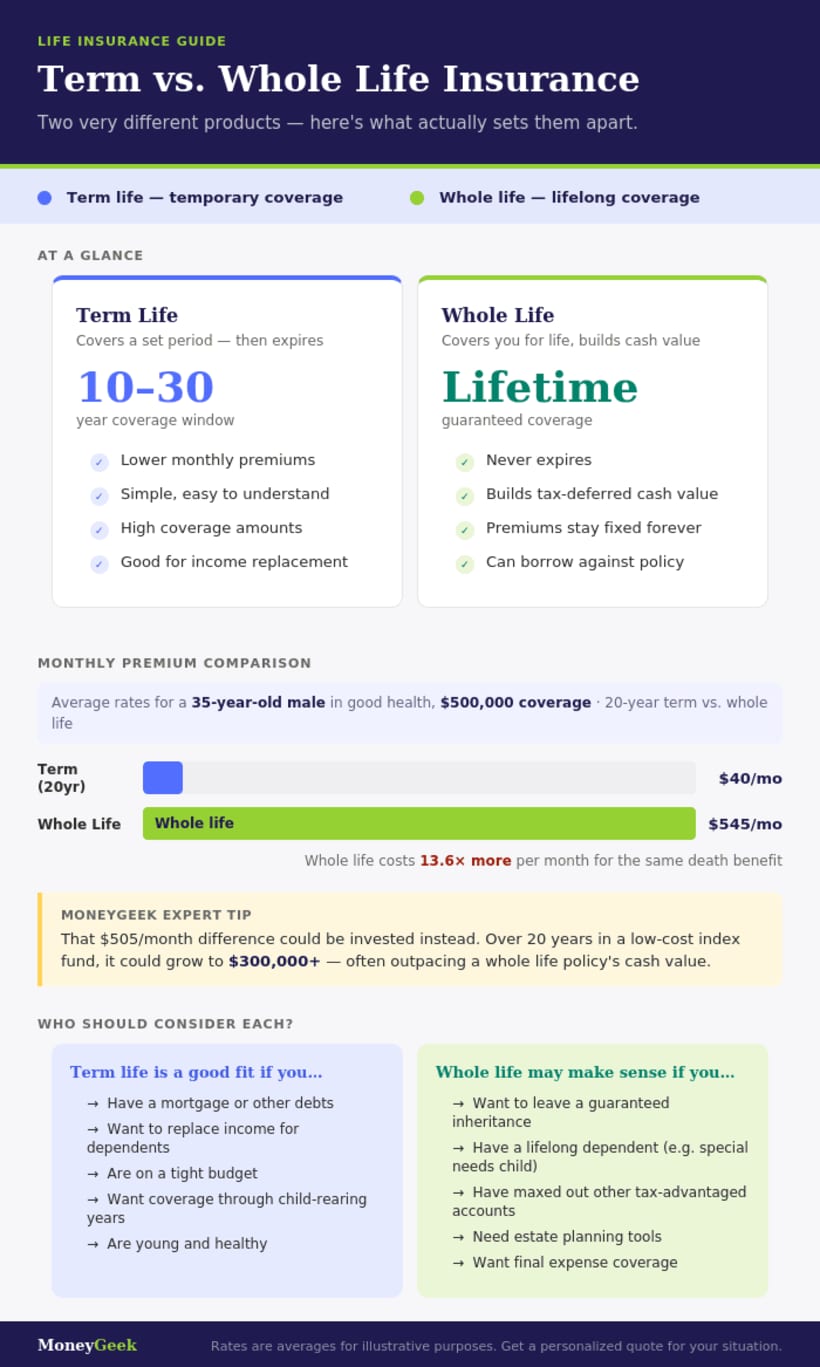
A 35-year-old man buying $500,000 in coverage pays an average of $40 a month for a 20-year term vs. $545 a month for whole life, per MoneyGeek's rate analysis of quotes across multiple carriers. That's the same amount of coverage for $505 less per month.
For most buyers, term life is the stronger financial choice. Whole life is worth the higher premium only when coverage must last a lifetime.
Select age group
Updated: September 14, 2026
Advertising & Editorial Disclosure
Key Takeaways
Term life: Temporary coverage for a set period of 10 to 30 years. Your premium (the monthly amount you pay to keep the policy active) stays fixed for the term, and your beneficiaries (the people you name to receive the payout) get a death benefit if you die during the policy window. Term life builds no cash value, which keeps its premiums lower than any permanent policy.
Whole life: Permanent coverage that lasts your entire life, as long as premiums are paid. Your beneficiaries receive a death benefit regardless of when you die. It also builds cash value (a savings component inside the policy) at a fixed rate; that value is accessible through loans or withdrawals while you're alive. Premiums are three to 14 times higher than comparable term coverage, depending on the buyer's age, per MoneyGeek's rate analysis.
The core difference is coverage duration and cost. Term life offers the same death benefit at a fraction of whole life's cost: an average of $40 a month vs. $545 for a healthy 35-year-old buying $500,000 in coverage, per MoneyGeek's rate analysis. Whole life costs more and is the right choice only when coverage must last a lifetime, such as for estate planning or a lifelong dependent.
Differences Between Term and Whole Life Insurance
Coverage duration | Fixed period (10–30 years) | Lifetime |
Premiums | Lower | Higher |
Cash value | None | Grows at a guaranteed fixed rate |
Premium structure | Fixed during term; increases at renewal | Fixed for life |
Investment component | None | Cash value grows tax-deferred |
Policy loans (ability to borrow against the policy while keeping it active) | Not available | You can borrow against cash value |
Death benefit taxation | Paid out income-tax-free | Paid out income-tax-free |
Dividend eligibility (whether policyholders receive a share of annual profits) | Not available | Available through mutual insurers, which are companies owned by policyholders rather than shareholders (not guaranteed) |
Estate planning utility | Expires with the term; no payout if coverage ends before death | Doesn't expire; the death benefit can fund trusts and skips probate |
Best for | Young families and budget-conscious buyers covering a specific financial period | Buyers who need permanent coverage for estate planning or a lifelong dependent |
Types of Term Life Insurance
- Level term life insurance: The death benefit and premium are set at the start and stay fixed for 10, 20 or 30 years. It's the most common type of term life, suited to buyers who need stable coverage for a defined period.
- Decreasing term life insurance: Homeowners use it to cover a mortgage: the death benefit tracks the declining balance, and premiums stay level throughout the term.
- Annual renewable term life insurance: Renews each year with premiums that rise as you age. Best for short-term coverage needs of one to three years, since it becomes more expensive than level term over longer periods.
- Convertible term life insurance: Converts from term to permanent coverage without requiring a new medical exam. Best for buyers who want the option to lock in permanent coverage later without new health underwriting (insurer’s evaluation process).
Types of Whole Life Insurance
- Traditional whole life insurance: Locks in fixed premiums, a set death benefit and steady cash value growth at a guaranteed rate. Best for buyers who want simple, predictable permanent coverage.
- Variable whole life insurance: Cash value is placed into sub-accounts that work like mutual funds, meaning returns depend on market performance and are not guaranteed. Best for buyers who are comfortable with investment risk in exchange for higher growth potential.
- Single-premium whole life insurance: The entire premium is paid in one upfront lump sum in exchange for a guaranteed death benefit and immediate cash value. Best for buyers who have a large sum available and want immediate permanent coverage with no ongoing payments.
- Limited payment whole life insurance: Premiums are paid over a fixed number of years, such as 10 or 20, after which lifetime coverage continues with no further payments required. Best for buyers who want lifelong coverage but prefer to finish paying premiums early.
Cost of Term Life vs. Whole Life
Whole life costs more than term at every age, and the dollar gap grows through your 50s: from about $300 a month at 25 to over $1,700 a month at 60 for $500,000 in coverage.
After 65, rising term rates compress the gap, though buyers in that range still pay several hundred dollars more per month for whole life.
The rates below are averages of quotes we collected for $500,000 in coverage; term figures reflect 20-year level-term policies.
25 | Female | $28 | $310 | $282 |
Male | $34 | $364 | $330 | |
30 | Female | $29 | $399 | $370 |
Male | $36 | $444 | $408 | |
35 | Female | $34 | $490 | $456 |
Male | $40 | $545 | $505 | |
40 | Female | $46 | $605 | $559 |
Male | $55 | $667 | $612 | |
45 | Female | $66 | $767 | $701 |
Male | $84 | $856 | $772 | |
50 | Female | $95 | $1,025 | $930 |
Male | $128 | $1,146 | $1,018 | |
55 | Female | $143 | $1,322 | $1,179 |
Male | $201 | $1,505 | $1,304 | |
60 | Female | $250 | $1,738 | $1,488 |
Male | $254 | $2,052 | $1,798 | |
65 | Female | $415 | $1,844 | $1,429 |
Male | $591 | $2,043 | $1,452 | |
70 | Female | $844 | $2,617 | $1,773 |
Male | $1,132 | $2,908 | $1,776 |
Rates shown are averages for nonsmokers of average height, weight and health.
Term vs. Whole Life Insurance: Pros and Cons
Benefits of Term Life vs. Whole Life
Benefits of term life insurance:
- Lower cost: Term life costs less than whole life because coverage is temporary and no cash value accumulates. Lower premiums keep coverage affordable for most buyers and leave room to direct the savings toward other financial goals.
- Fixed death benefit: The payout amount stays the same for the entire term, unlike decreasing term policies, where the benefit shrinks over time. Your family knows exactly what they'll receive.
- Level premiums: Premiums are locked in for the length of the term. Your rate won't change even if your health does after the policy is issued.
- Rider eligibility: Term policies qualify for riders (optional add-ons that expand or adjust coverage). Riders let buyers customize coverage beyond a standard death benefit, though available options vary by insurer.
Benefits of whole life insurance:
- Lifetime coverage: Whole life covers the policyholder for life as long as premiums are paid.
- Cash value: Whole life policies build cash value that the policyholder can borrow against or withdraw at any time. Growth is tax-deferred.
- Guaranteed death benefit: Pays regardless of when the policyholder dies.
- Fixed premiums: Premiums stay the same for the life of the policy.
- Dividend eligibility: Policyholders at mutual insurers may receive dividends when the company turns a profit. Dividends aren't guaranteed.
- Estate planning utility: Whole life doesn't expire, so it can anchor an estate plan in ways term life can't.
Drawbacks of Term Life vs. Whole Life
Drawbacks of term life insurance:
- Limited duration: Coverage ends when the term does. Renewing or buying a new policy costs more as you age.
- No cash value: Pays only a death benefit with no savings or investment component.
- Premiums increase at renewal: Applies to annual renewable term policies.
- Fewer options: Fewer riders and coverage adjustment options than whole life.
Drawbacks of whole life insurance:
- Higher cost: Depending on the buyer's age, whole life premiums are three to 14 times higher than comparable term coverage. A 35-year-old buying $500,000 in whole life pays an average of $505 more per month than for a comparable term policy. Over 20 years, that gap totals more than $121,000 in additional premiums.
- Lower investment returns: Cash value grows at a fixed rate set by the insurer, which has historically trailed market returns on investments like index funds.
- Rigid payment schedule: The policy lapses if premiums stop. Partial underpayments typically reduce the death benefit rather than cancel coverage.
- Cash value stays with the insurer at death: Any cash value left in the policy at death goes to the insurer. Beneficiaries receive the stated death benefit only, not the death benefit plus the accumulated cash value.
Should You Get Term or Whole Life Insurance?
Term life is better for most buyers. Whole life is the right fit when permanent coverage is required.
Term life is the better fit when:
- Keeping premiums low is the priority.
- Coverage is needed for a specific window, such as while a mortgage is outstanding or until children are financially independent.
- You're the primary income earner for a young family on a tight budget.
- The policy's only job is to provide a death benefit, not build savings.
- The premium savings will go into a 401(k), IRA or index fund instead.
Whole life is the better fit when:
- The policyholder needs coverage that doesn't expire, regardless of when death occurs.
- A dependent, such as a child with a disability, will need financial support for life.
- Life insurance is part of an estate plan (the strategy for distributing assets after death), and a permanent death benefit can fund a trust or leave a direct inheritance without the risk of coverage lapsing.
- You've maxed out contributions to a 401(k) or IRA and want a tax-deferred place to grow savings beyond those limits.
- The premium, which runs three to 14 times higher than a comparable term policy, is a payment you can sustain for life.

WHOLE VS. TERM LIFE INSURANCE FOR SENIORS
For seniors, the decision depends on financial obligations and long-term goals. Term life is a better fit when specific debts or time-limited obligations remain. Whole life is a better fit for estate planning or legacy purposes.
Buy Term and Invest the Rest
"Buy term and invest the rest" means getting a lower-cost term policy for death benefit coverage and directing the premium savings into a 401(k) (an employer-sponsored retirement savings account), an IRA (an individual retirement savings account) or an index fund.
Term premiums are much lower than whole life rates, and market-linked investments have historically outpaced the fixed returns on whole life cash value. For buyers who consistently invest the difference, historical index fund returns have generally exceeded whole life cash value growth rates.
The strategy has real limitations. It requires consistent follow-through over many years, and the premium savings often get spent rather than invested. The approach also doesn't account for the risk of becoming uninsurable when term coverage expires or the effect of a market downturn near the end of the policy term.
Whole life's guaranteed premiums and permanent death benefit justify the higher cost for buyers who value certainty. The cash value component adds a predictable, tax-deferred savings element that doesn't exist in term policies.
Switching Life Insurance Policies
Life insurance needs change, and switching policies is more common than most people think. Here's how each direction works.
- Switching from term to whole life: A convertible term policy allows the switch without a new medical exam. This is a common path for buyers whose needs have become permanent, such as when a health change makes future underwriting difficult or estate planning becomes a priority.
- Switching from whole to term life: The switch lowers premiums but gives up accumulated cash value. The right time is when major obligations are gone: the mortgage is paid and dependents are financially independent. Any surrender value above the total premiums paid in may be taxable. Consult a tax professional before making the change.
- Laddering policies: Some buyers pair a permanent whole life base with one or more term layers on top. The whole life policy covers lifelong needs. A 20-year term layer covers a larger temporary need, like a mortgage or income replacement during peak earning years. As each term layer expires, total coverage decreases in line with shrinking obligations. The whole life base stays in place.
Alternatives to Term and Whole Life Insurance
Term and whole life are the two most common types of life insurance. Two other permanent options are worth knowing if whole life's fixed structure doesn't fit your goals: universal life insurance and indexed universal life insurance (IUL). Both provide lifelong coverage but give you more flexibility in how premiums and cash value work.
Universal life insurance is permanent coverage with adjustable premiums and an adjustable death benefit. Cash value growth is tied to a market interest rate rather than a fixed rate, so returns can rise or fall. This is useful when your income varies year to year, but the policy requires more active management than whole life.
Indexed universal life insurance (IUL) links cash value growth to a stock market index, like the S&P 500. A floor protects against losses in down years. A cap limits gains in strong years, so total returns are bounded in both directions. IUL offers more growth potential than traditional whole life, but the product structure is more complex and varies across carriers.
Both types are permanent policies and cost more than term life. Comparing policies across carriers is harder than with a standard term policy because cash value projections vary by insurer and product structure. MoneyGeek covers each in detail: IUL vs. Whole Life Insurance and Universal vs. Whole Life Insurance.
Term vs. Whole Life Insurance: FAQ
For most buyers, term life delivers the same death benefit at a lower cost. Whole life earns the higher premium when coverage must last a lifetime or the policyholder has maxed out retirement accounts and wants a tax-deferred place to grow additional savings.
Yes. Whole life cash value is accessible in three ways. You can surrender the policy for its accumulated cash value minus any surrender charges (fees the insurer deducts for early cancellation). You can take a policy loan against the cash value while keeping the policy active. Or you can make a partial withdrawal without canceling the policy entirely.
Your beneficiaries receive the policy's death benefit, not the death benefit plus the cash value. If you die without withdrawing or borrowing the accumulated cash value, the insurer keeps it. This is one of the most commonly misunderstood features of whole life insurance.
For most people with straightforward coverage needs, no. Term life provides the same death benefit protection at a fraction of the cost. Whole life is worth it if you need permanent coverage, have a lifelong dependent, want a guaranteed tax-deferred savings vehicle after maxing out retirement accounts or are using life insurance as part of an estate plan.
When a term policy expires, coverage ends. If you're still alive, your beneficiaries receive nothing from that policy. To continue coverage, you can apply for a new policy at a higher rate because you're older. A guaranteed renewal clause, if your policy includes one, lets you renew year by year without new underwriting (the insurer's process of reviewing your health history to set your rate).
If your health has changed since you bought the policy, converting to permanent coverage before the conversion deadline is the strongest path. No new medical exam is required.
There's no universal age. Let a term policy lapse when the financial obligations it was covering no longer exist. For example, the mortgage is paid and anyone who depended on your income is now financially independent. A buyer who takes out a 20-year policy in their mid-30s usually reaches that point in their mid-50s. If permanent coverage needs have emerged before then, converting before the term expires is the stronger move over canceling.
Two situations call for a switch to whole life. A health change is the most urgent: if your term policy is within a few years of expiring and you've been diagnosed with a condition that would raise your rates or disqualify you from new coverage, switching before the conversion window closes may be the only path to permanent coverage without new underwriting.
A shift in financial goals is the second trigger. If estate planning or a lifelong dependent has become a priority, whole life can serve those needs in ways an expiring term policy cannot.
MoneyGeek collected quotes for $500,000 in coverage for term and whole life insurance. Rates are for nonsmokers in average health. Term figures are based on 20-year level term policies. Whole life figures are for traditional whole life policies with level premiums. Individual rates vary by health class, state and insurer, so a personalized quote will differ from the averages shown here.
Related Pages


About Mark Fitzpatrick

Mark Fitzpatrick is a licensed Property and Casualty (P&C) Insurance Producer and MoneyGeek's resident expert in insurance and economics. In nearly a decade covering the insurance market at LendingTree and MoneyGeek, he's analyzed hundreds of carriers and millions of rates across auto, home, renters, health and life insurance.
His work has appeared in The Washington Post, The New York Times and NPR. He draws on independent cost and consumer experience data, and no insurance company partnerships affect his recommendations.
Mark studied at Boston College and later earned a master's in economics and international relations from Johns Hopkins University. He worked in financial risk management at State Street before joining MoneyGeek. He's also a five-time “Jeopardy!” champion.