Updated: September 10, 2026

Advertising & Editorial Disclosure

Best Commercial Auto Insurance Companies for Vans

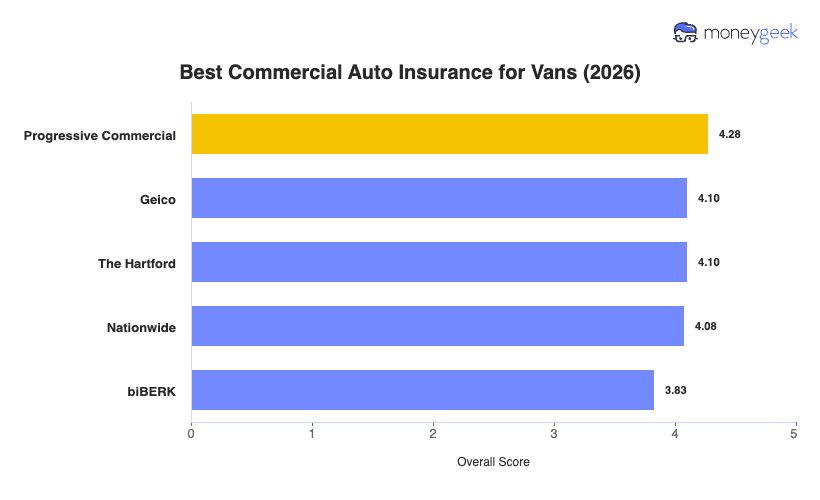
I looked at what van operators actually pay, how broad each policy runs and how easy each carrier makes it to buy a policy, manage it and get paid when a claim hits. Van work carries risks a standard auto policy wasn't built for, from cargo and equipment losses to hired-driver accidents and per-passenger injury exposure, so I weighed price against coverage depth and claims support to build my list of the best commercial auto insurance for vans. My top five picks are:

  • Choose if you want the best all-around pick: Progressive Commercial
  • Choose if you want a fast, digital-first policy: GEICO
  • Choose if you want the deepest coverage: The Hartford
  • Choose if you want strong agricultural fleet pricing: Nationwide
  • Choose if you want basic coverage issued fast: biBERK

I scored providers on the three things that decide whether a van policy actually works out: what you pay, how well you're covered and how the carrier performs when you need help. The rate data came from more than 700,000 business profiles across 22 industry categories, so pricing reflects everything from a single-van owner-operator to a multi-vehicle fleet instead of one national average. For customer experience, I drew on over 180,000 data points from reviews, forum discussions and industry research, covering the full policy lifecycle: buying, managing and filing claims.

Each provider's overall score weights affordability at 50%, customer experience at 30% and coverage options at 20%, since price is where most van operators start but rarely where the decision should end. See our full methodology.

95%

% of Small Businesses Covered

Over 220,588

Business Profiles Studied

22,058

Customer Experiences Analyzed

Progressive

Progressive Commercial: Best Overall, Best for Fleet Operations

COMPANY HIGHLIGHTS

Progressive Commercial is my overall pick for van coverage because it pairs the best rates in the group with top marks for customer service. It's the largest commercial auto insurer in the U.S. by written premium and has held that spot for over a decade, backed by a fully digital purchase, same-day coverage and the Snapshot ProView fleet telematics platform. At $159 per month on average, it runs 16% below the market average across 20 of 22 industry categories, and it prices 26% or more below average in manufacturing, food and beverage and healthcare. The rate edge thins out in agriculture, consulting and tech, where Progressive prices above average. Its coverage options rank fourth of five, so operations that need deep policy customization will find more at The Hartford.

Learn More: Progressive Business Insurance Review

GEICO

GEICO: Best for Low-Risk Business Areas

COMPANY HIGHLIGHTS

GEICO is my pick for small van operators who want coverage fast, prefer to manage everything digitally and would rather never call an agent. The whole experience is built around self-service: online quoting, same-day coverage, instant certificates of insurance and an app that handles policy changes, driver updates and claims from a phone. It averages $193 per month, 2% above the market average overall, but prices 6% to 16% below average in cleaning services, hospitality, education, transportation and other professional services. It's less competitive in real estate, childcare and healthcare, where rates run 21% to 31% above average. Its commercial claims also route through a general call center rather than a dedicated commercial unit, which matters for fleets with regular claims exposure.

The Hartford

The Hartford: Best for Coverage Depth

COMPANY HIGHLIGHTS

The Hartford is the strongest option for van operations that want the most comprehensive policy available, even at a higher price. It ranks first in coverage options and second in customer experience, and it's the only carrier in the analysis with a dedicated risk engineering team built into its fleet management program. With over 200 years in commercial insurance, it brings claims specialists, a self-service COI portal and written repair guarantees through its preferred network. At $220 per month on average, it runs 16% above the market average and ranks fourth on affordability, so price-first buyers will find better value with Progressive Commercial. It does rank first overall in agriculture and consulting van coverage, where the coverage structure outweighs the rate premium.

Learn More: The Hartford Business Insurance Review

Nationwide

Nationwide: Best for Agricultural and Specialty Fleets

COMPANY HIGHLIGHTS

Nationwide is my pick for van operations in agriculture, contracting and specialty fleet work, where competitive pricing and a strong coverage structure give it a real edge. Founded in 1926 as Farm Bureau Mutual, it still runs a dedicated agribusiness division with commercial auto programs built for farm operations. It averages $164 per month, 13% below the market average, and ranks first in affordability for agriculture, consulting, recreation and other professional services. Its coverage ranks second, making it the strongest option on policy structure outside of The Hartford. The trade-off is customer experience, where it ranks last of the five, and the purchase requires an agent to finalize rather than closing entirely online.

Learn More: Nationwide Business Insurance Review

biBerk

biBERK: Best for Simple Coverage Needs

COMPANY HIGHLIGHTS

biBERK is my pick for fitness, tech and IT businesses that need basic commercial coverage fast with no broker involved. Founded in 2015 as a Berkshire Hathaway direct-to-business brand, it's built entirely around speed: a full commercial van policy can be quoted, purchased and issued with a certificate of insurance in under 10 minutes, with 24/7 self-service for adding vehicles, updating drivers and managing billing. The trade-off shows up in price and breadth. biBERK averages $212 per month, 12% above the market average, and ranks last on both affordability and coverage. It prices well in fitness (26% below average) and tech and IT (22% below average) but runs 20% to 37% above average in healthcare, construction, repair and maintenance, hospitality and wholesale distribution. It's also only available in 21 states.

Learn More: biBERK Business Insurance Review

Best Commercial Van Auto Insurance Add-Ons

Most van operations start with commercial auto, but that policy only covers the vehicle itself. What's inside the van, who's driving it and the rest of the business usually need their own coverage. Here's how the main pieces fit together for a van-based operation.

Physical damage (collision & comprehensive)
Repair or replacement of your van after a collision, theft, fire, vandalism or weather damage.
Any time the van is financed or leased, since a total loss can leave you owing the lender more than the payout. Smart to carry on owned vans too.
Hired and non-owned auto (HNOA)
Liability when employees drive rented vans or their own vehicles for business errands.
When staff run business trips in personal or rented vehicles. Personal policies routinely exclude business use, so this fills a common gap.
Motor truck cargo
The goods and freight you're hauling for others while they're in transit.
When the operation moves third-party goods, such as delivery, wholesale distribution or healthcare supply runs.
Inland marine (tools & equipment)
Tools, materials and specialized equipment carried in the van, which commercial auto does not cover.
When the business depends on what's inside the van, like a contractor's tools or mounted service gear.
Third-party bodily injury and property damage claims from your everyday operations, off the road.
For nearly every van business, and often required by client contracts and commercial leases.
General liability plus commercial property in one bundled, usually cheaper package.
When you want core coverage in a single placement. The Hartford and biBERK both let you fold van coverage into a BOP.
Medical bills and lost wages when an employee is hurt on the job, including drivers.
Once you have employees. Most states mandate it, so requirements depend on where you operate.

Best Van Commercial Auto Insurance Checklist

Van operators who overpay usually describe the operation wrong at the quote stage and land in the wrong risk class. Working through these steps in order gets you the right policy at the right price and keeps a quote from repricing at underwriting.

  1. 1
    Define Your Risk Profile

    Categorize each van as owned, leased or employee-owned but used for work, and record its primary use, annual mileage and every driver's record. Mileage is a real underwriting factor, and the gap between 10,000 and 25,000 miles a year can push the same van into a higher pricing bracket. Pay extra attention to use classification if you're in healthcare, construction, transportation or cleaning services, since what the van does and carries drives both price and which carriers will write it.

  2. 2
    Determine Your Coverage Requirements

    Once the risk profile is set, figure out what you need beyond the state minimum. For van operations, that usually means:

    • Motor truck cargo when you haul goods or freight for third parties.
    • Collision and comprehensive on any financed or leased van, so a total loss doesn't leave you owing the lender.
    • Hired and non-owned auto when employees drive personal or rented vans for work, since personal policies exclude business use.
    • Higher liability limits for passenger vans, where each occupant in a serious accident is a separate bodily injury claim.
  3. 3
    Research Providers by Industry and Vehicle Type

    Carriers don't price van risk the same way, and the classification conversation happens before the quote. Shortlist the carriers that price well in your industry using the data on this page, then contact them to confirm how they'd classify your specific use: service, delivery, passenger transport or cargo hauling. That classification moves the premium more than any other single factor.

  4. 4
    Evaluate Coverage Quality and Policy Terms

    Comparing commercial auto premiums tells you what a policy costs; comparing terms tells you what it actually delivers. For each shortlisted carrier, review standard versus endorsement-only coverages, available liability limits and any exclusions that could affect a claim. Confirm how the policy handles mid-term additions, since most carriers give a new van 30 days of automatic coverage but you have to notify them before that window closes.

  5. 5
    Get Quotes and Confirm Filing Requirements

    Compare commercial insurance quotes only after narrowing the field, and request at least three so you can compare price and terms together. If a quote comes back high, recheck the vehicle use classification before ruling the carrier out. Two situations trigger extra filings: interstate vans rated over 10,001 pounds need a USDOT number and a federal endorsement, and vans carrying passengers for pay may need state for-hire authority. Tell the carrier upfront so any filings are built into the policy from day one.

Best Commercial Van Insurance: Bottom Line

Selecting the right commercial auto insurance for a van starts with three questions: what the van actually does for the business, which industry it operates in and what a serious accident would actually cost. Those answers narrow the field faster than any rate comparison, because pricing and coverage fit vary more by use case and industry. These factors deserve careful consideration before a single premium is reviewed.

Not every provider fits every business, and the lowest-premium policy isn't always the best value when it leaves gaps in coverage. The service model also matters: a fully digital, self-service experience suits operations that prefer to manage everything online, while agent-supported guidance works better for accounts that benefit from direct contact. Two or three quotes then confirm whether the right fit on paper holds up for the specific fleet and requirements.o and the client disputes that work actually generates.

Best Commercial Auto Insurance for Vans Chart

Best Commercial Auto Insurance for Vans: FAQs

About Mark Flores


Mark Flores, Business Insurance Writer, MoneyGeek

Mark Flores is a Business Insurance Content Writer at MoneyGeek, where he focuses on commercial auto, commercial property, cyber and specialty business insurance coverage. His work simplifies coverage terms, gives business owners a strong baseline for expected costs, and narrows down policies and providers tailored to your operation, regardless of complexity.

Before joining MoneyGeek’s business insurance team, Mark worked as a Senior Content Writer at Clutch.co, where he produced structured B2B reviews and provider analyses based on client interviews, company research and service evaluation. That experience shaped his approach to business insurance content, especially when comparing insurers, explaining coverage differences and translating complex policy features into practical guidance for small business owners.

Mark also spent nearly 4 years as a digital marketing specialist serving small-business clients across industries such as home services, manufacturing and education. That background gives him practical context for how businesses evaluate vendors, manage operational needs and make purchasing decisions.

At MoneyGeek, he applies this research and evaluation experience to build guides that help transportation sectors, those with complex property-related risks (such as hotels and retail stores), and those most at risk of a cyberattack get the coverage they need at a reasonable price.

Linkedin: https://www.linkedin.com/in/mark-jason-flores-7844634a/

Contact Email: mark.flores@moneygeek.com