


ERGO NEXT is the best workers' compensation insurance company in Hawaii. My analysis shows that it's average premium is around 20% lower that the state average, which saves you about $28 each month. It lets you get covered online in a matter of minutes and manage your policy entirely online.
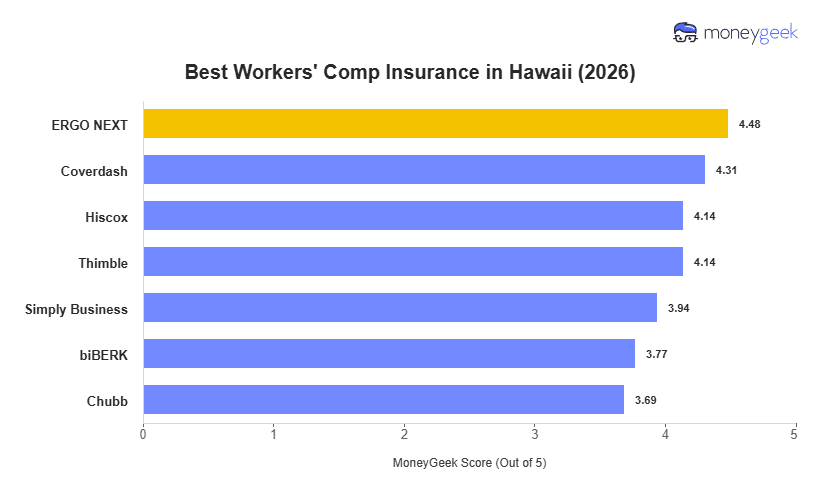
Best Workers' Comp Insurance in Hawaii (2026)
With rates as low as $11 monthly, ERGO NEXT, Coverdash and Hiscox have the best workers' comp insurance in Hawaii.
Our matching tool can connect you to top Hawaii workers' comp insurance providers and help you find your ideal coverage.
Select state
Updated: August 26, 2026
Advertising & Editorial Disclosure
Best Workers' Comp Insurance Companies in Hawaii
| ERGO NEXT | 4.48 | $109 | 1 | 4 |
| Coverdash | 4.31 | $129 | 4 | 1 |
| Hiscox | 4.14 | $131 | 5 | 7 |
| Thimble | 4.14 | $120 | 6 | 6 |
| Simply Business | 3.94 | $148 | 2 | 2 |
MoneyGeek analyzed workers' comp insurance rates and provider performance across Hawaii using small business profiles with one to four employees spanning 408 major industries. Companies earn up to five points in each category in our scoring system. We then use a weighted average of these category scores to calculate a MoneyGeek score out of five.
- Affordability (55%): Based on average payroll for the most common employee code per industry and state classification, priced per employee for a one to four employee business.
- Customer Experience (35%): Evaluates buying (20%), which covers quote access, pricing accuracy and sales support; policy management (30%), which covers payroll reporting, audits, billing and loss control; and claims (50%), which covers FNOL speed, adjuster support, medical access, wage replacement and dispute handling.
- Coverage Options (10%): Assesses coverage completeness (35%), including employers' liability and wage and medical reimbursement; policy flexibility and endorsements (25%); eligibility, state and industry breadth (20%); and policy terms, limits and exclusions (20%).

ERGO NEXT
Best Workers' Comp Insurance in Hawaii
MoneyGeek Rating
4.5/ 5
4.5/5Affordability Score
4.3/5Customer Experience Score
3.8/5Coverage Score
Average Monthly Cost
$109Claims Processing Score
4/5Policy Management Score
4.1/5Buying Process Score
4.4/5

Coverdash
Best Hawaii Workers' Comp Insurance: Runner-Up
MoneyGeek Rating
4.3/ 5
4.1/5Affordability Score
4/5Customer Experience Score
4.9/5Coverage Score
Average Monthly Cost
$129Claims Processing Score
4/5Policy Management Score
4/5Buying Process Score
4/5
Cheapest Workers' Comp Insurance in Hawaii
The Hartford and ERGO NEXT are the cheapest workers' comp insurance companies in Hawaii. The Hartford leads every lower-risk professional category; ERGO NEXT leads most physical and skilled-labor industries
The spread across all industries is the key figure worth noting. Transportation & Logistics runs an average of $331 per month, 30 times more than Financial Services. That gap is larger than what we see in other states, which reflects Hawaii's geographic isolation and the higher cost of medical care and lost wages in the islands.
| Financial Services | The Hartford | $11 | $132 |
| Beauty, Body & Wellness Services | ERGO NEXT | $14 | $168 |
| Marketing & Communications | ERGO NEXT | $15 | $180 |
| Consulting Services | The Hartford | $19 | $228 |
| Real Estate & Property Services | The Hartford | $21 | $252 |
| Other Professional Services | The Hartford | $23 | $276 |
| Tech/IT | The Hartford | $37 | $444 |
| Childcare Services | Coverdash | $41 | $492 |
| Food & Beverage | ERGO NEXT | $46 | $552 |
| Hospitality, Travel & Tourism | The Hartford | $46 | $552 |
| Healthcare & Medical | The Hartford | $49 | $588 |
| Retail & Product Rental | The Hartford | $58 | $696 |
| Nonprofit & Associations | The Hartford | $62 | $744 |
| Pet Care Services | ERGO NEXT | $70 | $840 |
| Education | ERGO NEXT | $74 | $888 |
| Fitness Services | ERGO NEXT | $74 | $888 |
| Repair & Maintenance | ERGO NEXT | $81 | $972 |
| Arts, Media & Entertainment | ERGO NEXT | $105 | $1,260 |
| Recreation & Sports | ERGO NEXT | $123 | $1,476 |
| Cleaning Services | ERGO NEXT | $125 | $1,500 |
| Manufacturing | The Hartford | $166 | $1,992 |
| Agriculture & Natural Resources | ERGO NEXT | $182 | $2,184 |
| Wholesale & Distribution | ERGO NEXT | $212 | $2,544 |
| Construction & Contracting | ERGO NEXT | $258 | $3,096 |
| Transportation & Logistics | ERGO NEXT | $331 | $3,972 |
How to Get Workers' Comp Insurance in Hawaii
Hawaii is a competitive private market so it's important that you look at different factors when you're getting workers' comp insurance. Our guide helps you find a policy and a provider that best suits your needs.
- 1Confirm Hawaii Coverage Requirements
Hawaii generally requires workers’ comp for businesses with at least one employee, whether the worker is full-time, part-time, permanent or temporary. Certain domestic workers, unpaid nonprofit volunteers and qualifying business owners are excluded. Check each worker’s status instead of relying on your total headcount alone.
- 2Identify Your NCCI Class Codes
A hotel, landscaping company and accounting firm will not pay the same rate for every $100 of payroll. NCCI class codes account for those differences in workplace risk. Match your codes to the work your business performs and separate employees only when NCCI rules permit it.
- 3Document Payroll, Employee Count and Claims History
Give insurers an accurate picture of your workforce before requesting quotes. Break out payroll by class code and work location, then obtain loss runs showing your previous claims. Note any temporary workers or owners whose coverage status could affect the premium calculation.
- 4Request Quotes From Multiple Licensed Hawaii Carriers
The Hawaii Disability Compensation Division doesn’t sell workers’ comp, and the state doesn't have a fund from which you can purchase a policy. Because of this, make sure to contact several carriers authorized to write coverage in Hawaii and compare business insurance quotes using identical payroll figures. If you need a carrier list, The Department of Commerce and Consumer Affairs can provide them.
- 5Compare Quality, Not Just Price
Hawaii allows an injured employee to choose a treating physician on the island where they live, although specialist referrals require carrier approval. Favor an insurer that can authorize care promptly and coordinate claims wherever your employees are based. These capabilities may matter more than a small difference in premium.
- 6Complete the Purchase and Set Up Payroll and Audit Reporting
Once coverage starts, organize payroll records in the format your carrier requires for audits. Establish an injury-reporting process as well. Hawaii expects an employer’s WC-1 report to reach the Disability Compensation Division within seven working days after learning of an injury.
- 7Review at Annual Renewal
Treat renewal as a fresh check of your policy rather than an automatic continuation. Compare audited payroll with your original estimate and correct classifications for any work your business added or stopped performing. If your workforce expanded to another island, confirm that the insurer can support claims there.
Best Workers' Compensation Insurance in Hawaii: Bottom Line
ERGO NEXT and Coverdash are Hawaii's top workers' comp providers by overall MoneyGeek score. Hiscox and Thimble are tied for third. ERGO NEXT leads on rate at $109 a month and holds the state's highest customer experience score, while Coverdash earns our top coverage score for employers who need the broadest policy options. Hawaii's seven-provider field is smaller than most states, so comparing all available options is worthwhile before binding coverage.

LEARN MORE ABOUT HAWAII BUSINESS INSURANCE
Hawaii business insurance is more than just having workers' compensation insurance. Whether you're in the tourism or recreational industry or you're construction, you'll likely need more coverages to make sure your have enough financial protection. I've put together resources so you can see which providers are our top choices for different coverage types.
Hawaii Workers' Workers' Compensation Insurance FAQ
ERGO NEXT leads Hawaii as the top workers' compensation insurer in the state with the highest MoneyGeek score and the state's lowest monthly rate at $109. Here are the top five providers in the state based on our analysis:
- ERGO NEXT: $109 a month
- Thimble: $120 a month
- Coverdash: $129 a month
- Hiscox: $131 a month
- biBerk: $146 a month
Hawaii requires workers' comp for all employers with one or more employees. The Hawaii Department of Labor and Industrial Relations, Disability Compensation Division administers the program. Employers who fail to comply face penalties. Hawaii also separately requires temporary disability insurance (TDI), a distinct requirement from workers' comp.
The average cost of workers' comp insurance in Hawaii is $138 per employee monthly, well above the $74 national benchmark. Beauty, Body & Wellness Services ($18 a month) and Financial Services ($18 a month) are the most affordable industries in the state, while Transportation & Logistics has the highest state average of $423 a month.
Hawaii is a competitive private market with no state fund, so employers purchase coverage directly from private insurers. Employers who can't obtain voluntary coverage may access the Hawaii Workers' Compensation Assigned Risk Pool through NCCI. Hawaii's TDI requirement is separate and must be secured independently.
Workers' compensation in Hawaii covers:
- Medical expenses for workplace injuries and occupational illnesses
- Wage replacement benefits during recovery periods
- Permanent disability payments for lasting impairments
- Survivor benefits for families of workers who die from job-related incidents
About Angelique Palenzuela-Cruz

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.
LinkedIn: linkedin.com/in/ma-angela-cruz
Email Contact: angelique.palenzuela@moneygeek.com