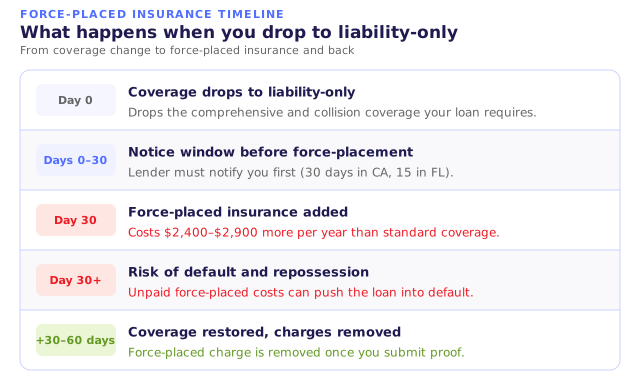


While technically you could buy a liability-only policy, your lender requires full coverage on a financed car throughout the loan term. The rare exceptions apply only to very old vehicles with minimal loan balances.
Why you need full coverage for financed cars:
- Loan agreements require comprehensive and collision coverage. If you drop to liability-only, you're only covered for damage you cause others — not theft, not your own repairs, not a total loss.
- Dropping coverage violates your contract. Your insurer notifies the lender within 30 days if your full coverage lapses. A coverage gap triggers a violation even if every loan payment is current.
- Force-placed insurance kicks in automatically. Your lender buys a policy to cover its interest at a much higher rate than you'd pay on your own and bills the premiums to your loan balance.